

Dow Jones Movement Overview
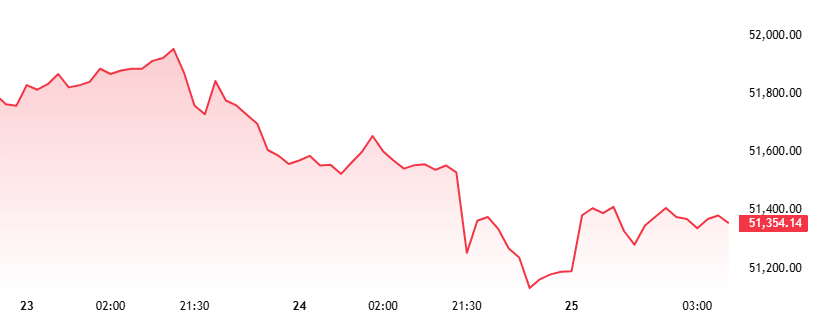
Dow Jones Industrial Average futures slipped 0.1% to 51,652.0 points as of 23:50 GMT on 24 September 2026, extending the index’s pullback after cash trading closed at 51,349.98, down 161.61 points, or 0.31%, on Thursday, its third straight losing session. The drift lower in futures came as soaring Treasury yields and a jump in oil prices weighed on risk sentiment heading into Friday’s session.
Key Driver Behind The Move
Treasury yields remained the dominant force. The 10-year yield crossed 5.2% and briefly touched a fresh 19-year high, while the 30-year yield closed at its highest level since 2004. Several Federal Reserve officials warned this week that further rate increases are likely given persistently sticky inflation, extending the bond selloff that has pressured rate-sensitive names within the Dow throughout the week.
Market Data And Reaction
Oil added to the inflation concerns pressuring futures, with crude jumping more than 3% after a Houthi missile attack on Saudi Arabia. The move was tempered somewhat after Reuters reported that US and Iranian negotiators are discussing a phased deal to reopen the Strait of Hormuz, a report that had already helped the Dow pare its losses during Thursday’s cash session. S&P 500 and Nasdaq 100 futures also drifted lower, tracking the same cross-currents of higher yields and firmer oil.
Broader Market Implications
The move lower in futures reflects a market still digesting multiple, overlapping pressures: a bond rout that shows no sign of easing, an energy market unsettled by renewed Middle East hostilities, and lingering uncertainty over AI-related capital spending after Oracle disclosed a force majeure notice on a major data center project. Traders also awaited details from the Trump-Xi meeting in Washington, where both sides described the talks as productive but offered few specifics on trade or AI cooperation.
What Dow Traders Should Watch
- Whether Friday’s cash open confirms the drift lower signaled in futures
- Any further Federal Reserve commentary on the pace of additional rate hikes
- Confirmation or denial of progress on the reported Hormuz reopening deal
- Details emerging from the Trump-Xi talks on trade and AI, given the two-month extension of their trade truce