

Key Takeaways
An expected RBA hike to 4.85% would reinforce the focus on persistent inflation. With the increase widely anticipated, guidance on further tightening may matter more for the Australian Dollar. Meanwhile, AI financing concerns continue to weigh on technology shares, despite lower oil prices. Today’s Focus: The RBA is widely expected to raise its rate to 4.85% at 11:30 GMT+8. Its forecasts and 12:30 briefing will help shape the next move. At 23:00, US JOLTS and factory orders will provide further checks on hiring demand and investment. |
Global Market Review 03/11/2026
- Monday: Dow rose 0.41% to 51,983.98, while S&P 500 fell 0.51% to 7,541.40 and Nasdaq Composite lost 1.07% to 25,164.32.
- AI financing concerns weighed on technology shares despite lower energy prices.
- Brent settled 7.63% lower at $104.77, and WTI fell 7.36% to $96.46.
- The closing snapshot put gold at $3,946.11 and the Dollar Index at 101.77.
- The 2-year Treasury yield rose 0.6 basis points to 4.594%; the 10-year fell 1.6 basis points to 4.913%.
Economic Calendar
Key Events on November 3 (GMT+8)
- Japan holiday — Culture Day; US midterm elections (US local date)
| Time (GMT+8) | Event | Importance |
|---|---|---|
| 11:30 | RBA Rate Decision and Statement on Monetary Policy | *** |
| 12:30 | RBA Press Conference | ** |
| 23:00 | US JOLTS Job Openings SEP | ** |
| 23:00 | US Factory Orders MoM SEP | ** |
Key Events on November 4 (GMT+8)
- AMD earnings: after the US close on November 3 (early November 4 GMT+8). BoE decision: November 5, 20:00 GMT+8. US payrolls: November 6, 21:30 GMT+8.
| Time (GMT+8) | Event | Importance |
|---|---|---|
| 05:30 | API Crude Oil Stock Change | ** |
| 06:00 | Australia Services and Composite PMI Final OCT | ** |
| 09:45 | China Services and Composite PMI OCT | ** |
| 16:55 | Germany Services and Composite PMI Final OCT | ** |
| 17:00 | Euro Area Services and Composite PMI Final OCT | ** |
| 17:30 | UK Services and Composite PMI Final OCT | ** |
| 18:00 | Euro Area CPI YoY Flash OCT | *** |
| 21:15 | US ADP Employment Change OCT | ** |
| 21:30 | US Trade Balance SEP ; Treasury Quarterly Refunding Announcement | ** |
| 22:45 | US Services and Composite PMI Final OCT | ** |
| 23:00 | US ISM Services PMI OCT | *** |
| 23:30 | EIA Crude Oil Stocks Change | ** |
Markets Analysis 03/11/2026
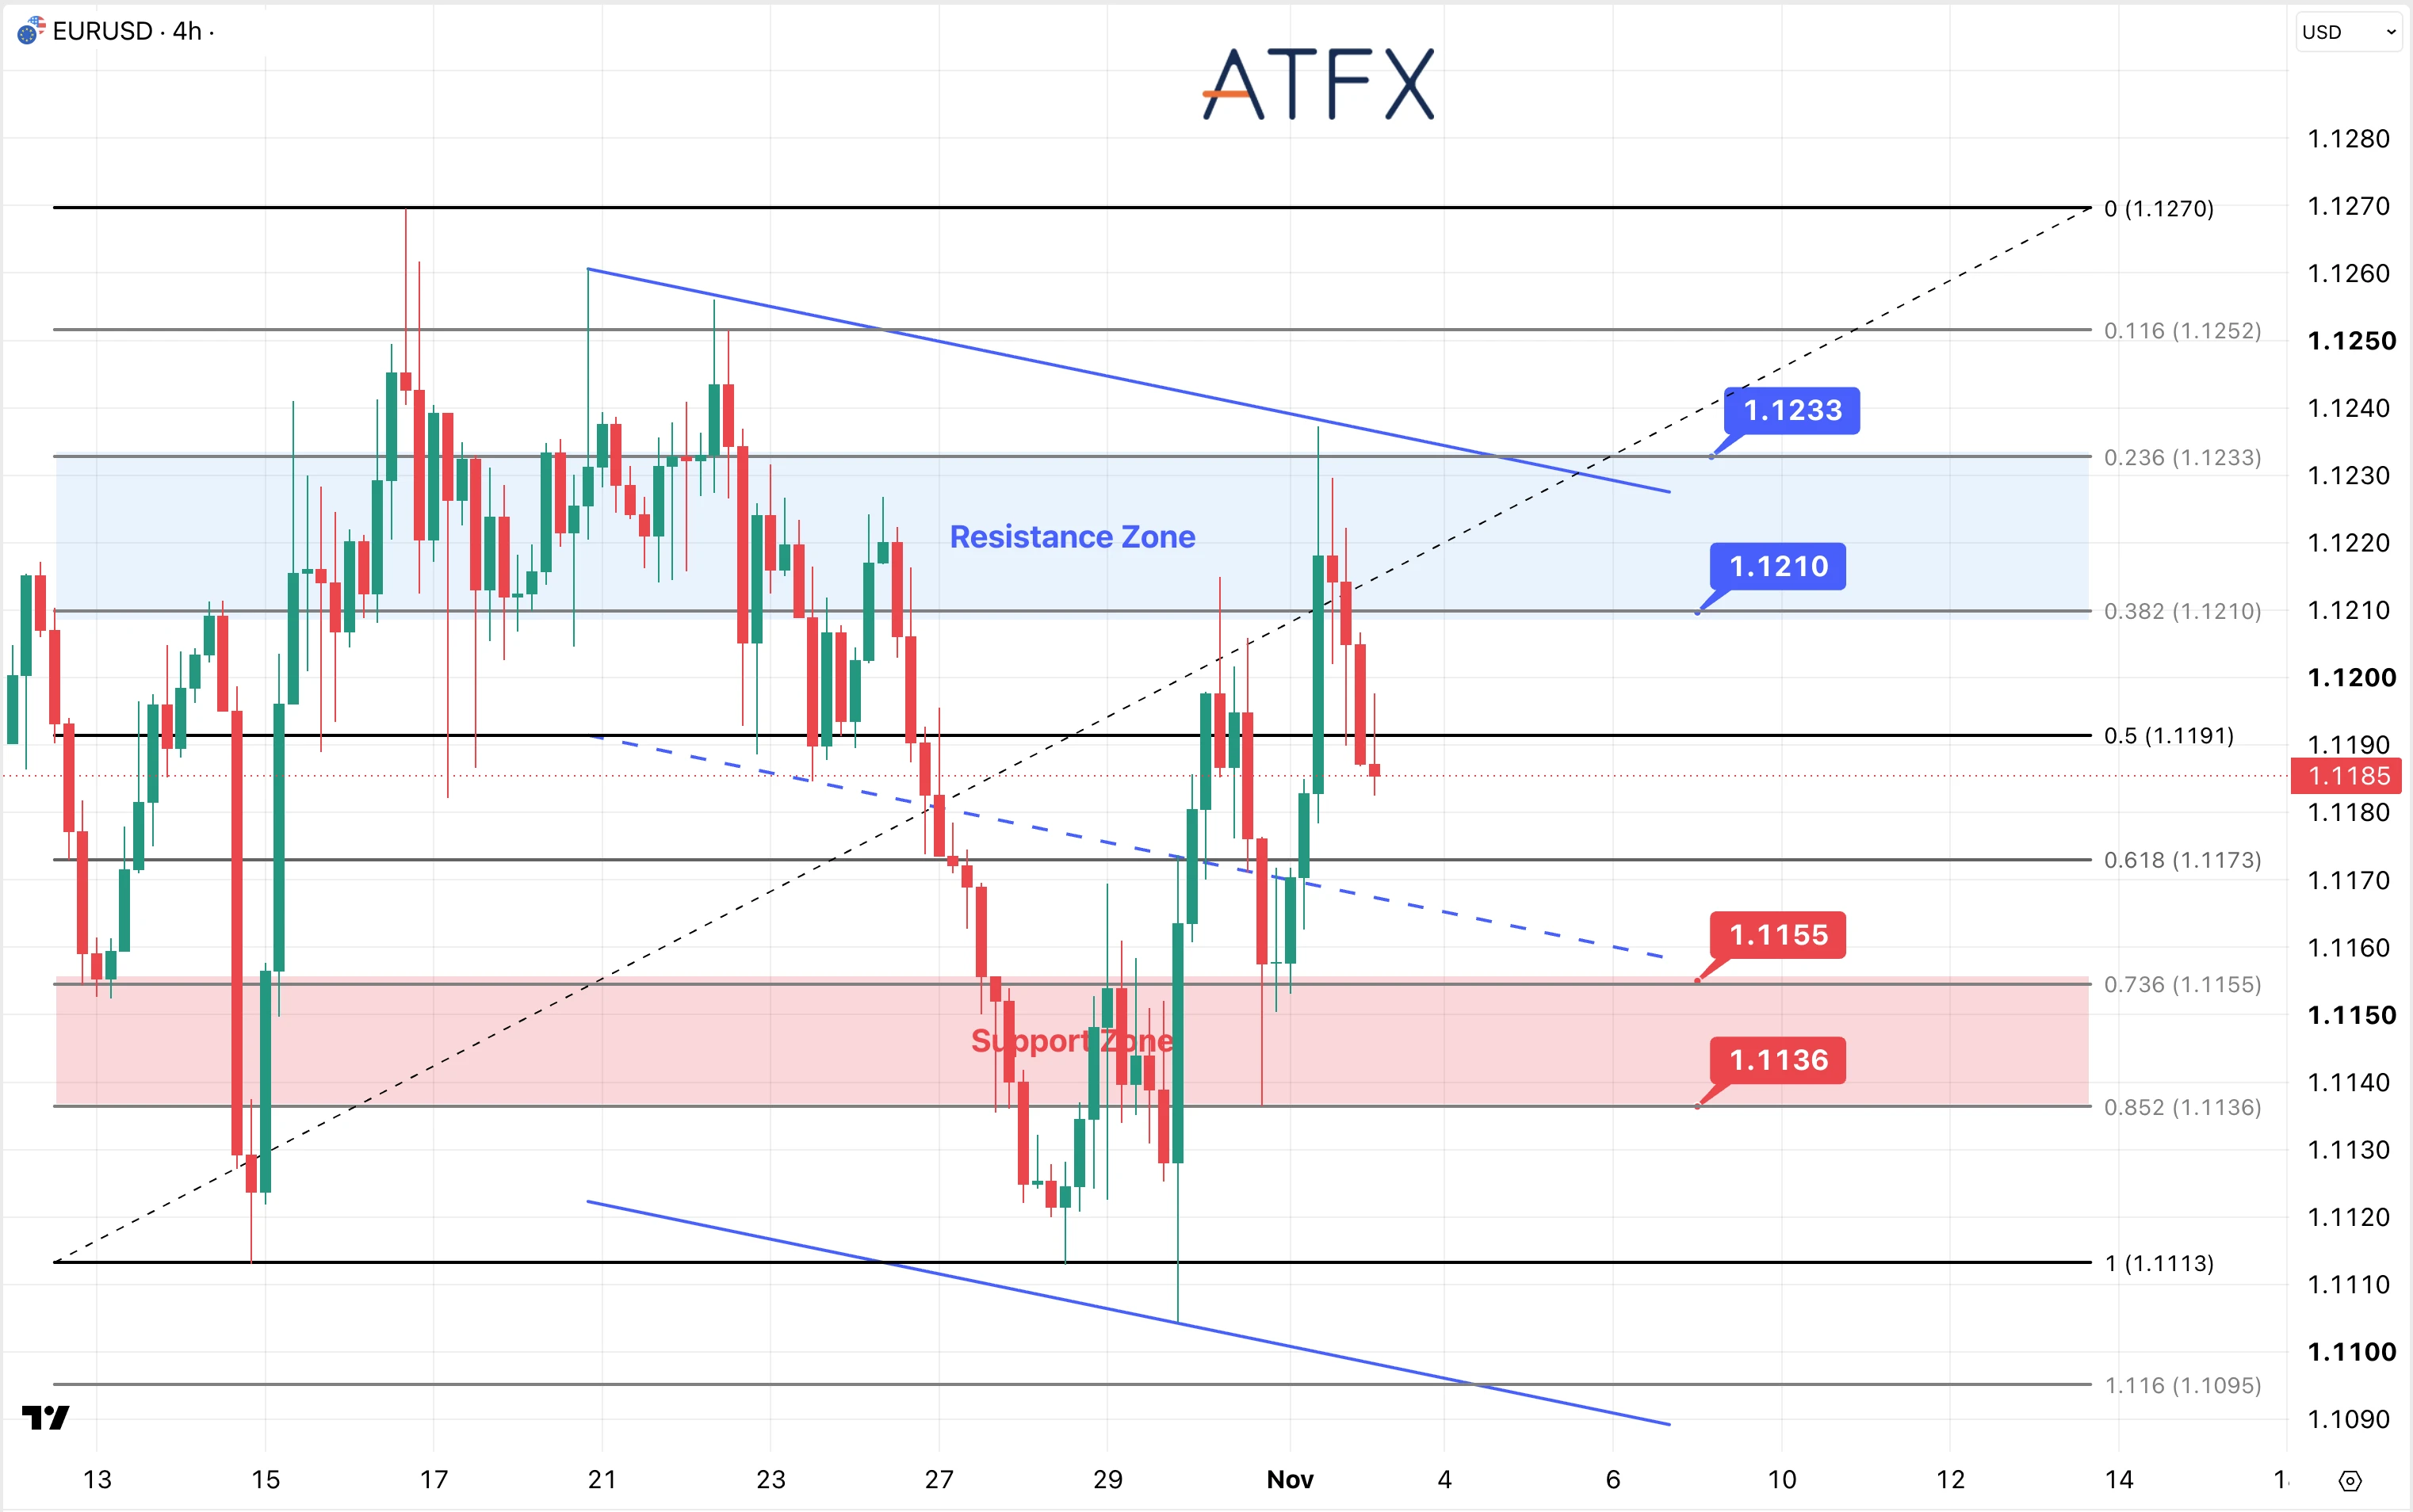
- Resistance: 1.1210/1.1233
- Support: 1.1155/1.1136
Analyst’s View: Lower oil costs eased some pressure on the Euro, but the diplomatic outlook remains uncertain. Wednesday’s inflation and services releases will test the balance between price pressures and growth. US labor data and election results could also shift dollar demand.
EUR/USD is near 1.1185 after retreating from above 1.1233. It remains below 1.1191, leaving the recovery incomplete. A sustained break beneath 1.1173 would expose 1.1155 and 1.1136; losing that support zone would return attention to the October low around 1.1113.
Bias: Neutral to Cautiously Bearish
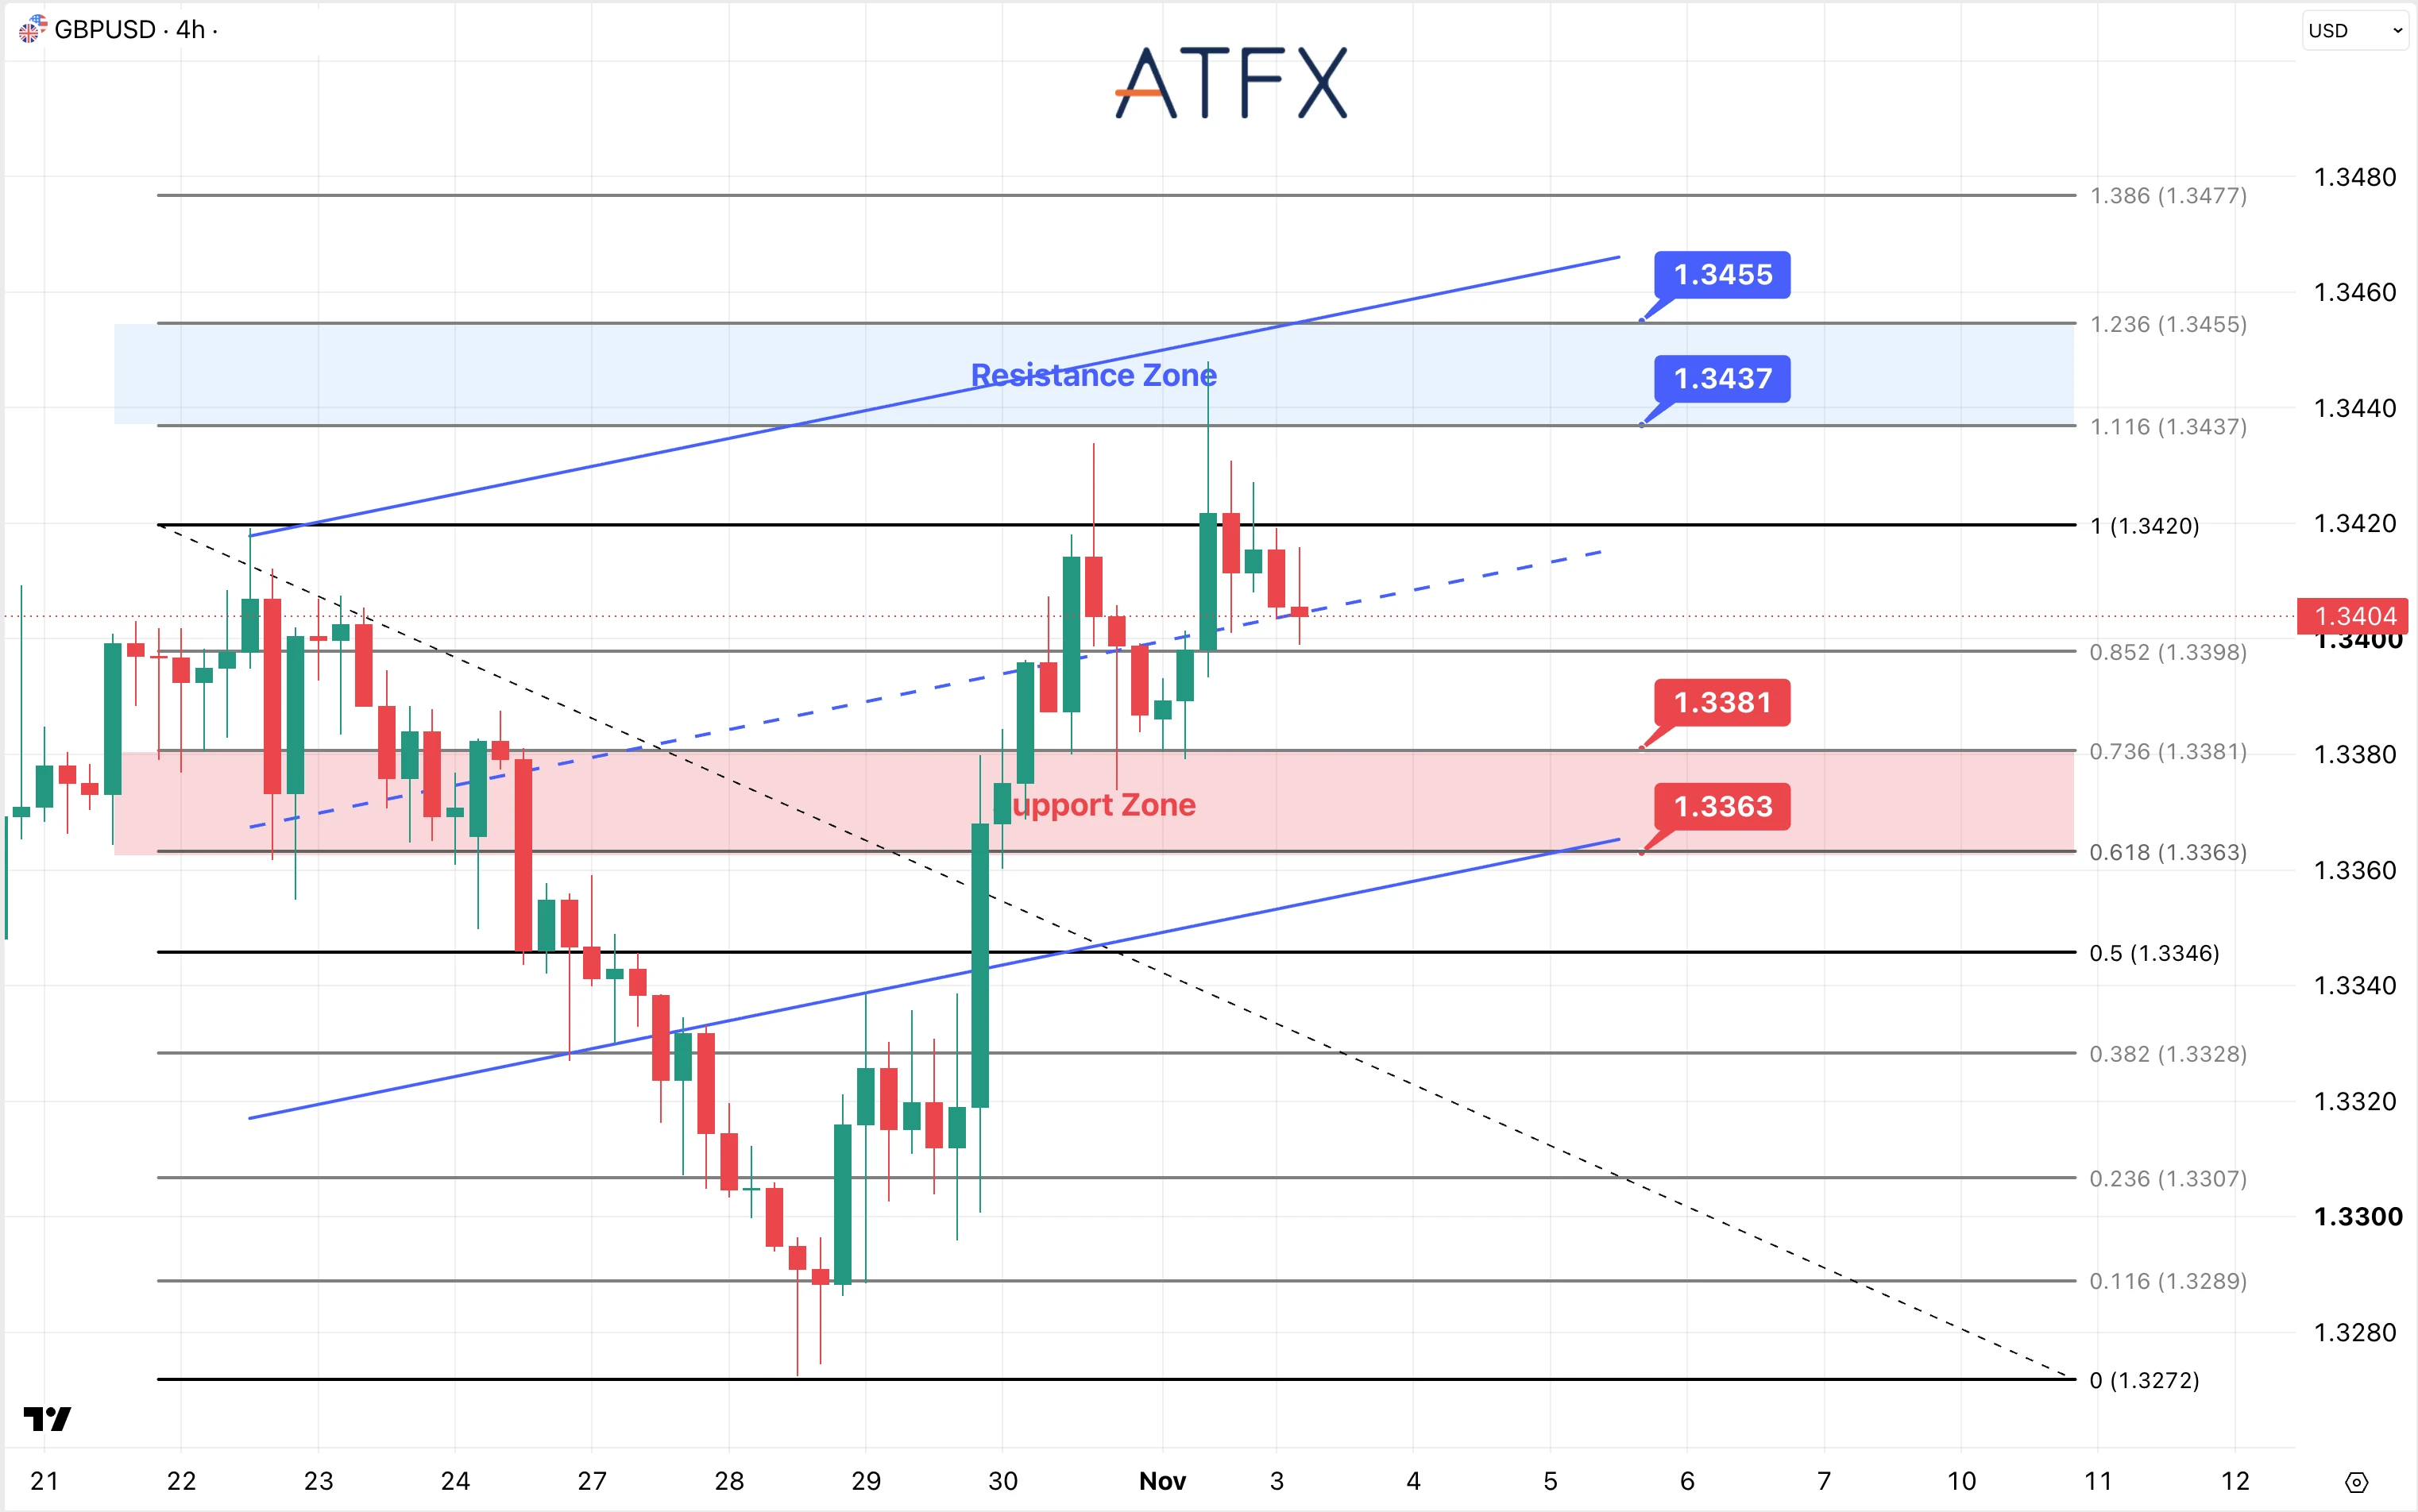
- Resistance: 1.3437/1.3455
- Support: 1.3381/1.3363
Analyst’s View: Sterling’s recovery faces Thursday’s BoE decision, with a hike to 4.00% widely expected. Guidance on further tightening will matter alongside the decision itself. Wednesday’s services survey will gauge activity, while US election developments could influence the pair through the Dollar.
GBP/USD is near 1.3404, close to the rising channel’s midline after retreating from the upper resistance area. Holding 1.3398 would preserve scope for another attempt above 1.3420 toward 1.3437 and 1.3455.
Bias: Neutral to Cautiously Bullish
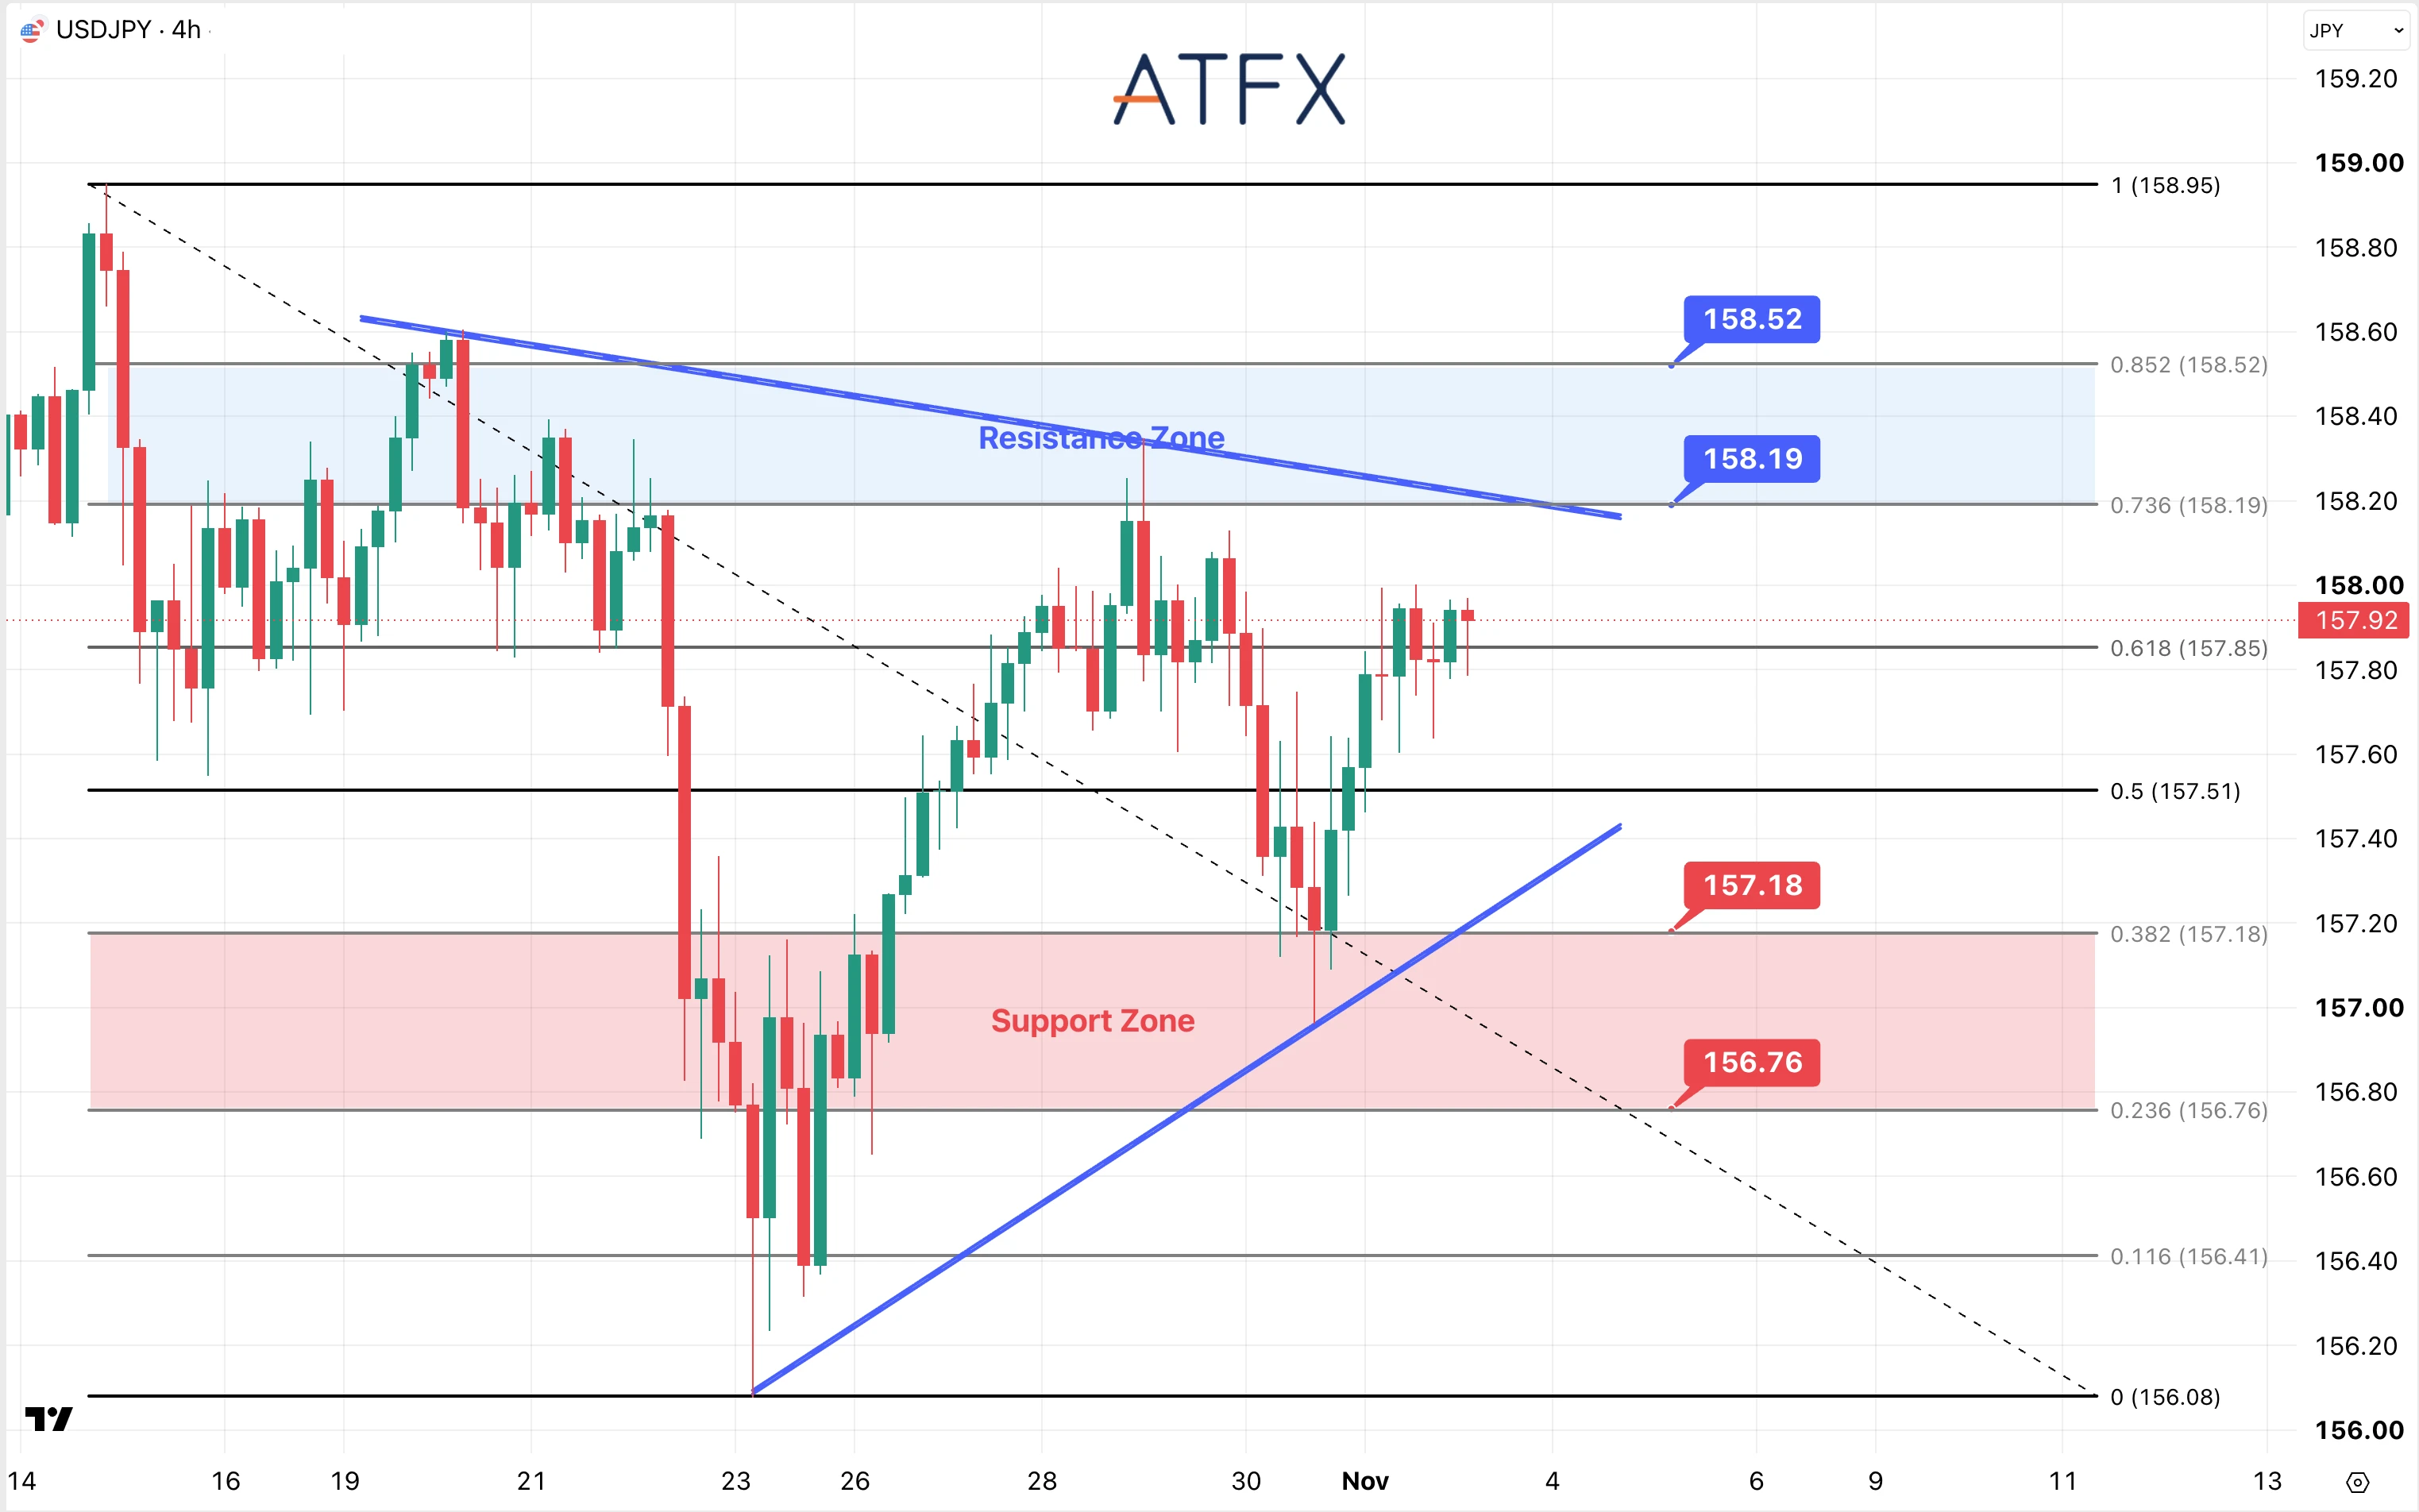
- Resistance: 158.19/158.52
- Support: 157.18/156.76
Analyst’s View: The US–Japan rate gap continues to support the Dollar after the BoJ held rates at 1.25%. US labor data will shape Fed expectations, while Japan’s inflation keeps further BoJ tightening in view. Concerns about possible Japanese intervention may limit sharp gains.
USD/JPY is near 157.92 after rebounding from 157.18 and recovering from 157.85. Price remains below 158.19, where the descending trendline adds resistance. A sustained break above that level would bring 158.52 into focus.
Bias: Neutral to Cautiously Bullish
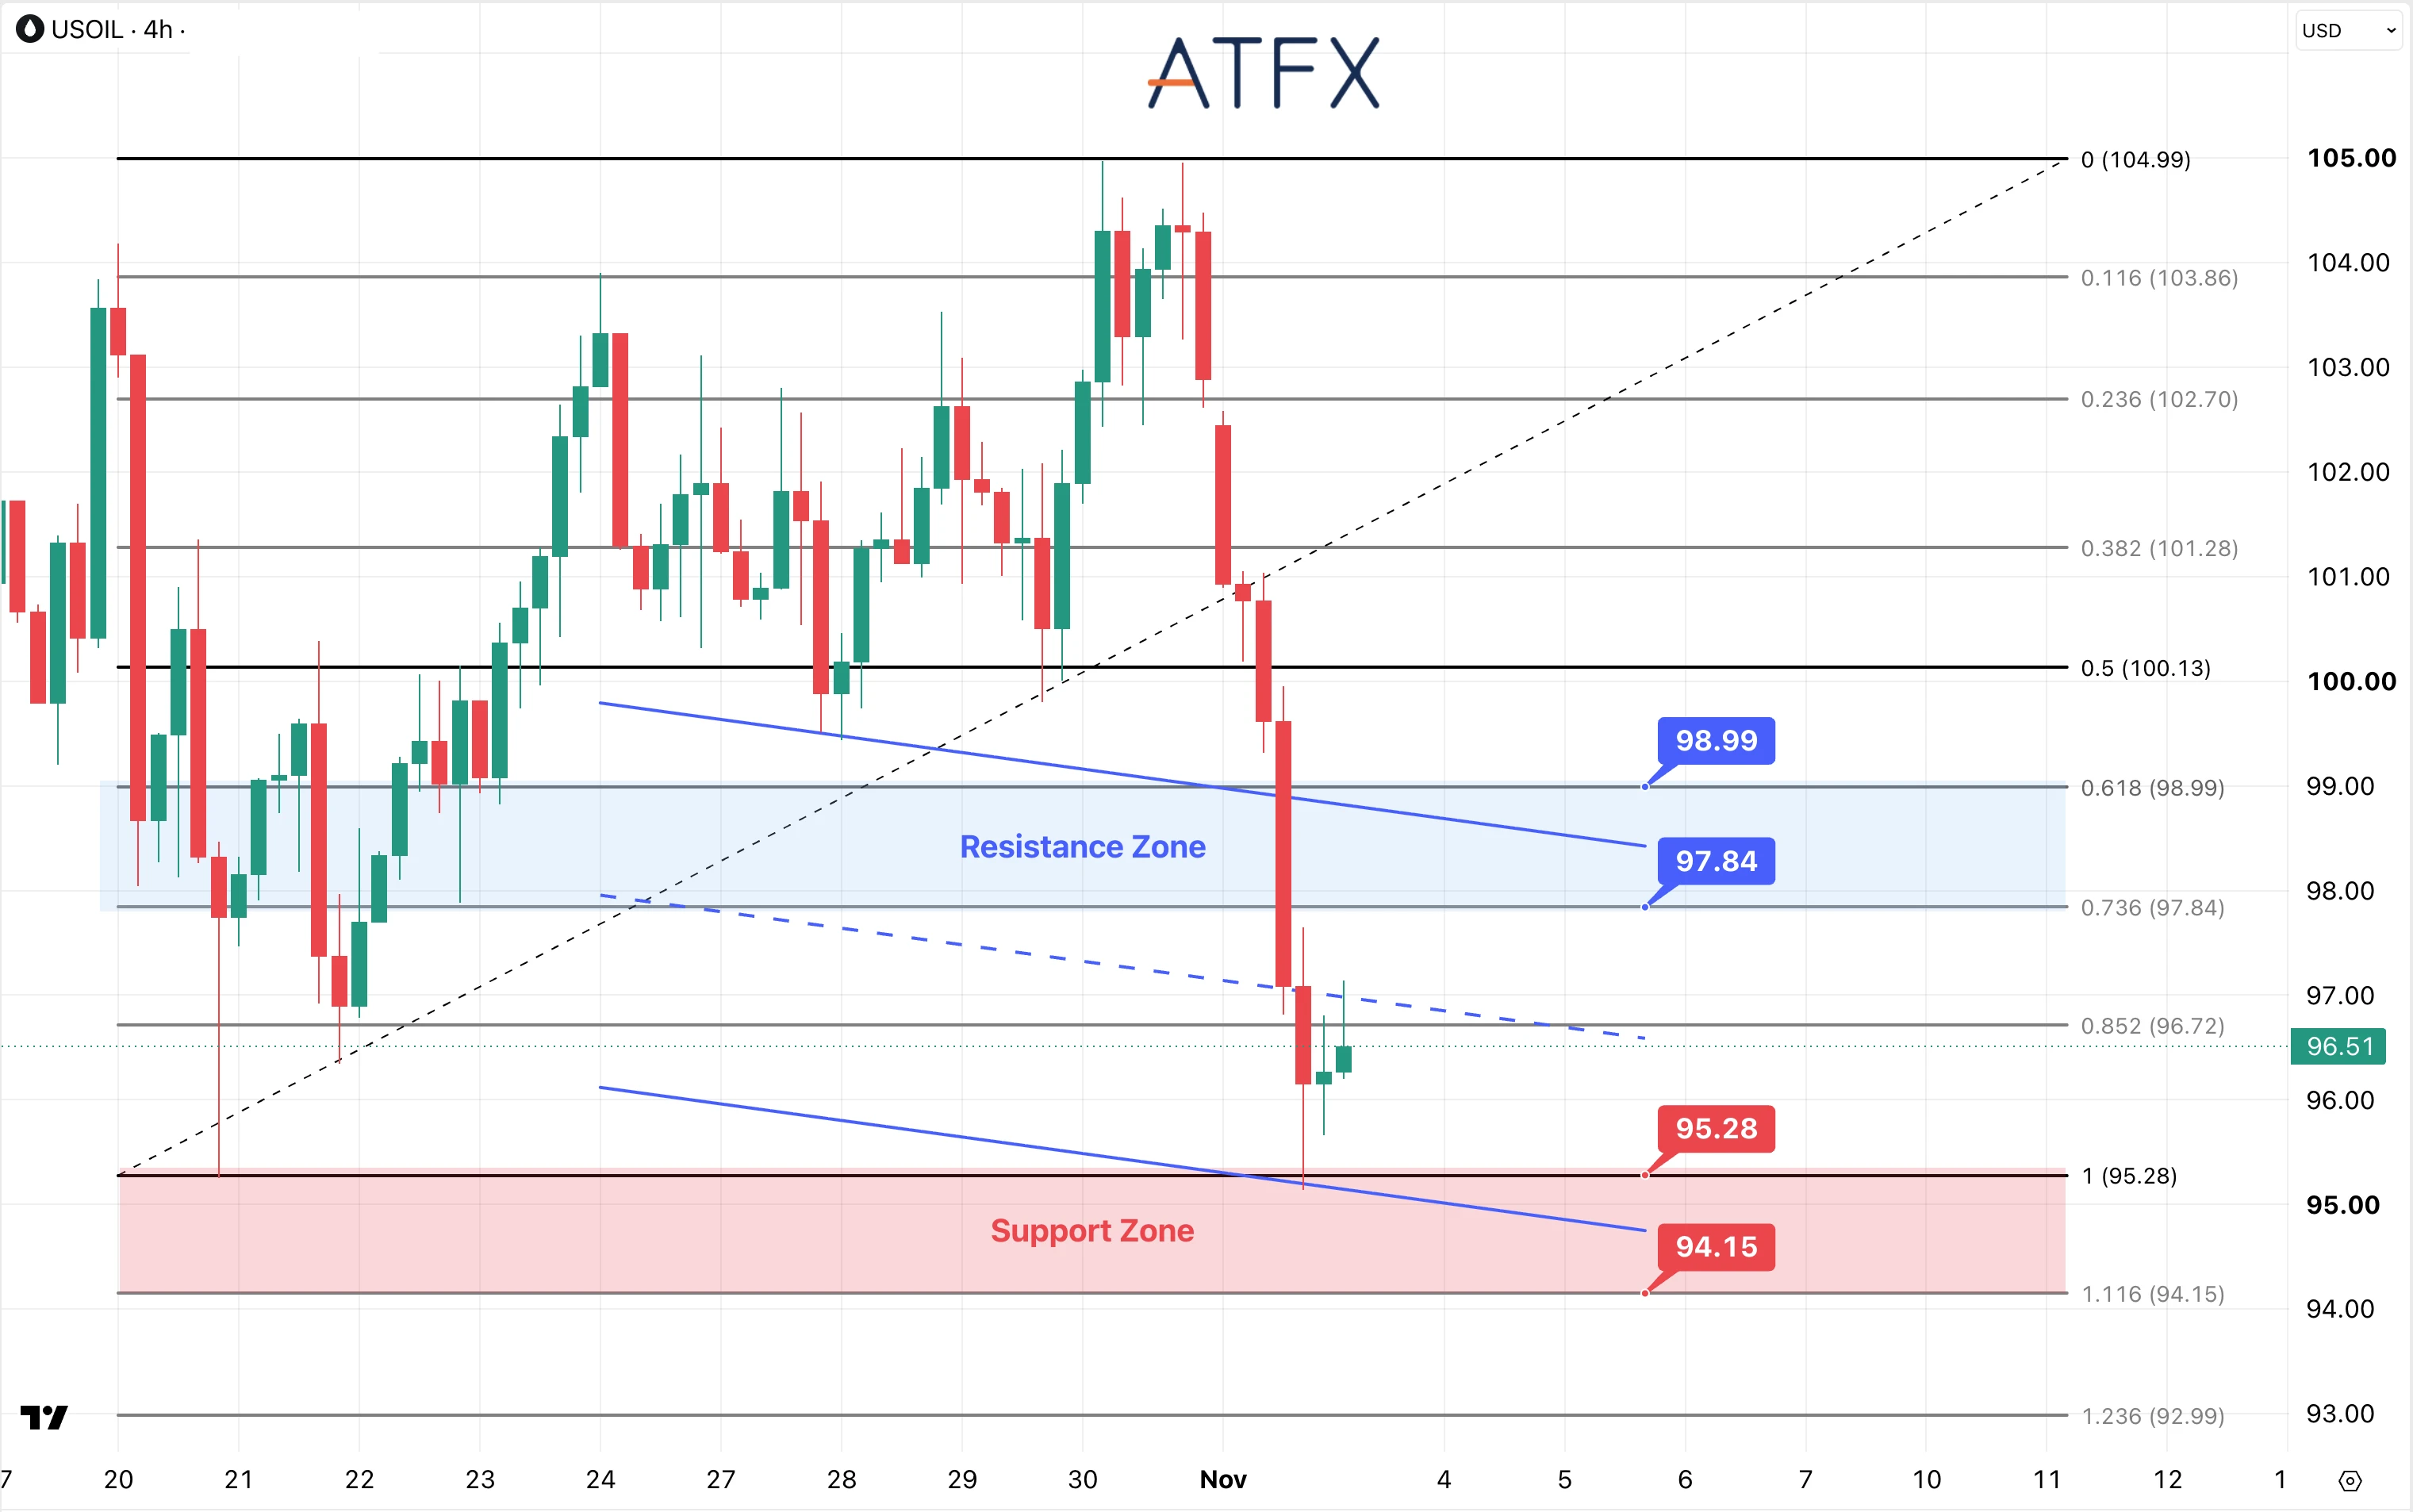
- Resistance: 97.84/98.99
- Support: 95.28/94.15
Analyst’s View: Monday’s oil decline reflected hopes for a diplomatic breakthrough, even though no agreement was reached. Reports of a US strike on Qeshm Island prompted an early Tuesday bounce. Further military activity or progress in talks could quickly shift supply expectations.
This week’s API and EIA inventory releases offer another check on US supply and demand. Middle East developments may overshadow their impact, particularly if new headlines shift expectations for exports through the Strait of Hormuz.
USOIL is near $96.51 after falling from above $104 and rebounding from around $95.28. Price remains below $96.72 and the descending channel’s midline. A sustained move below $95.28 would be $94.15, followed by $92.99. The modest bounce has not reversed the broader decline, and renewed supply disruption leaves the market vulnerable to abrupt reversals.
Bias: Cautiously Bearish
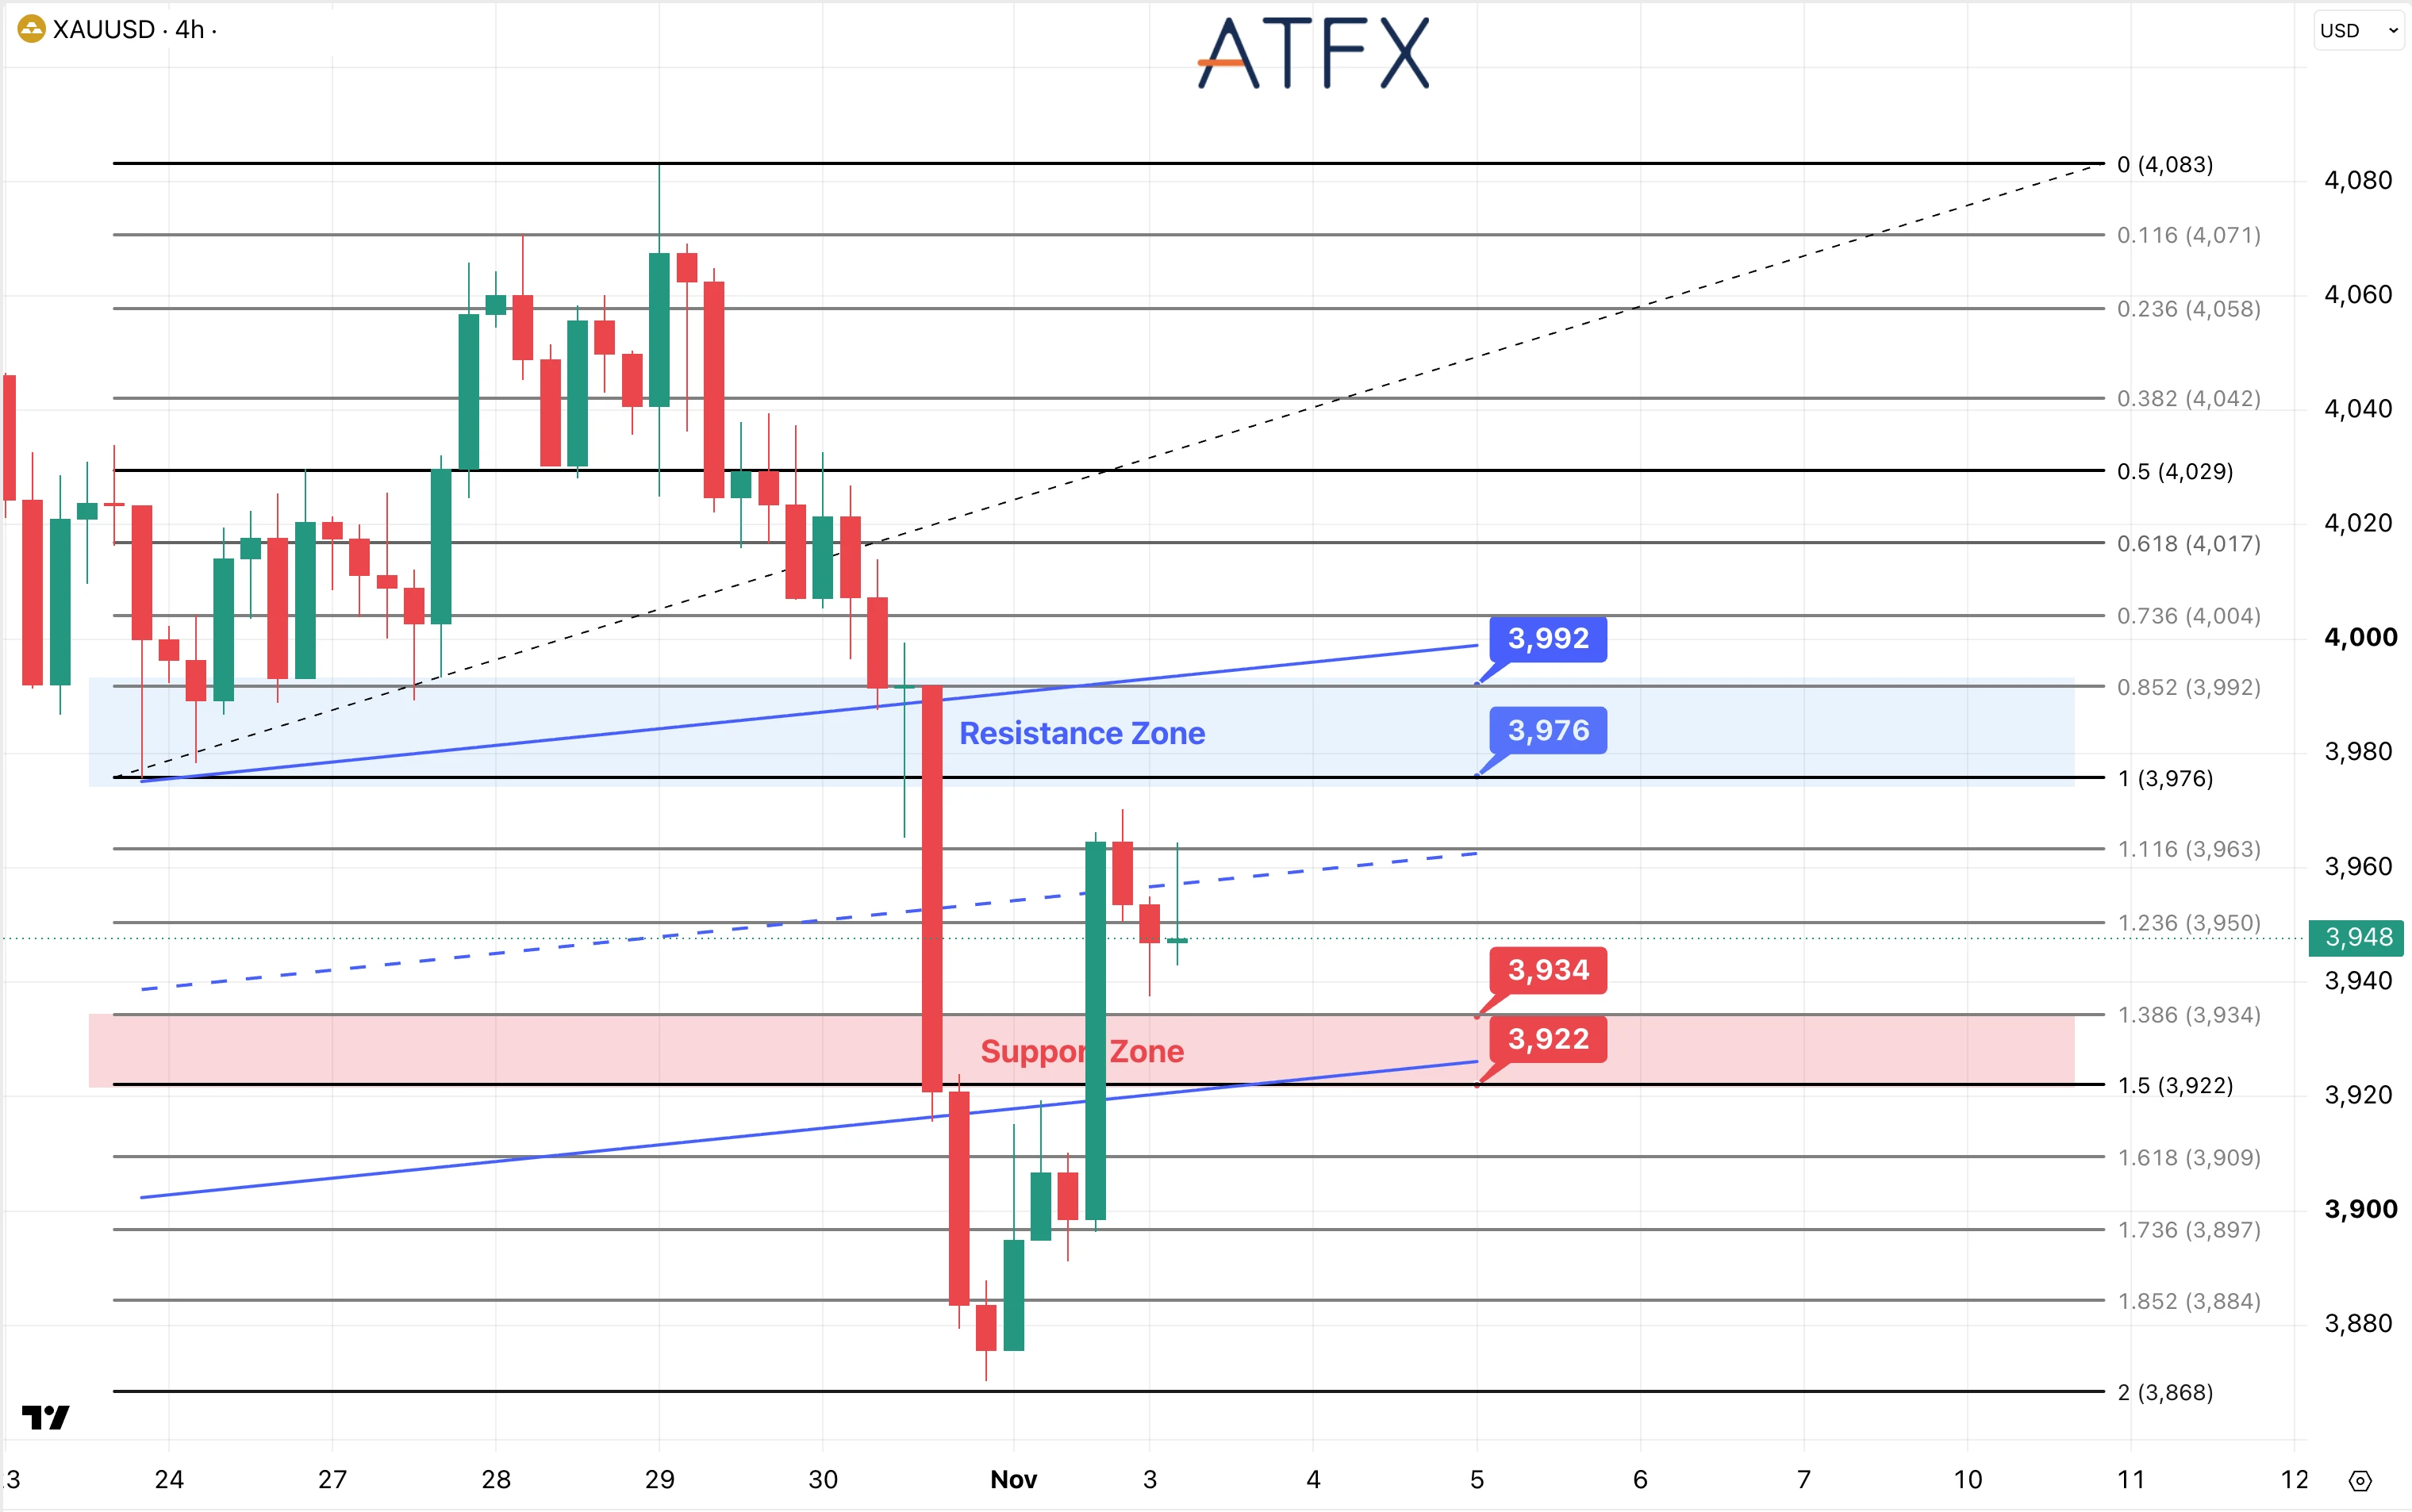
- Resistance: 3976/3992
- Support: 3934/3922
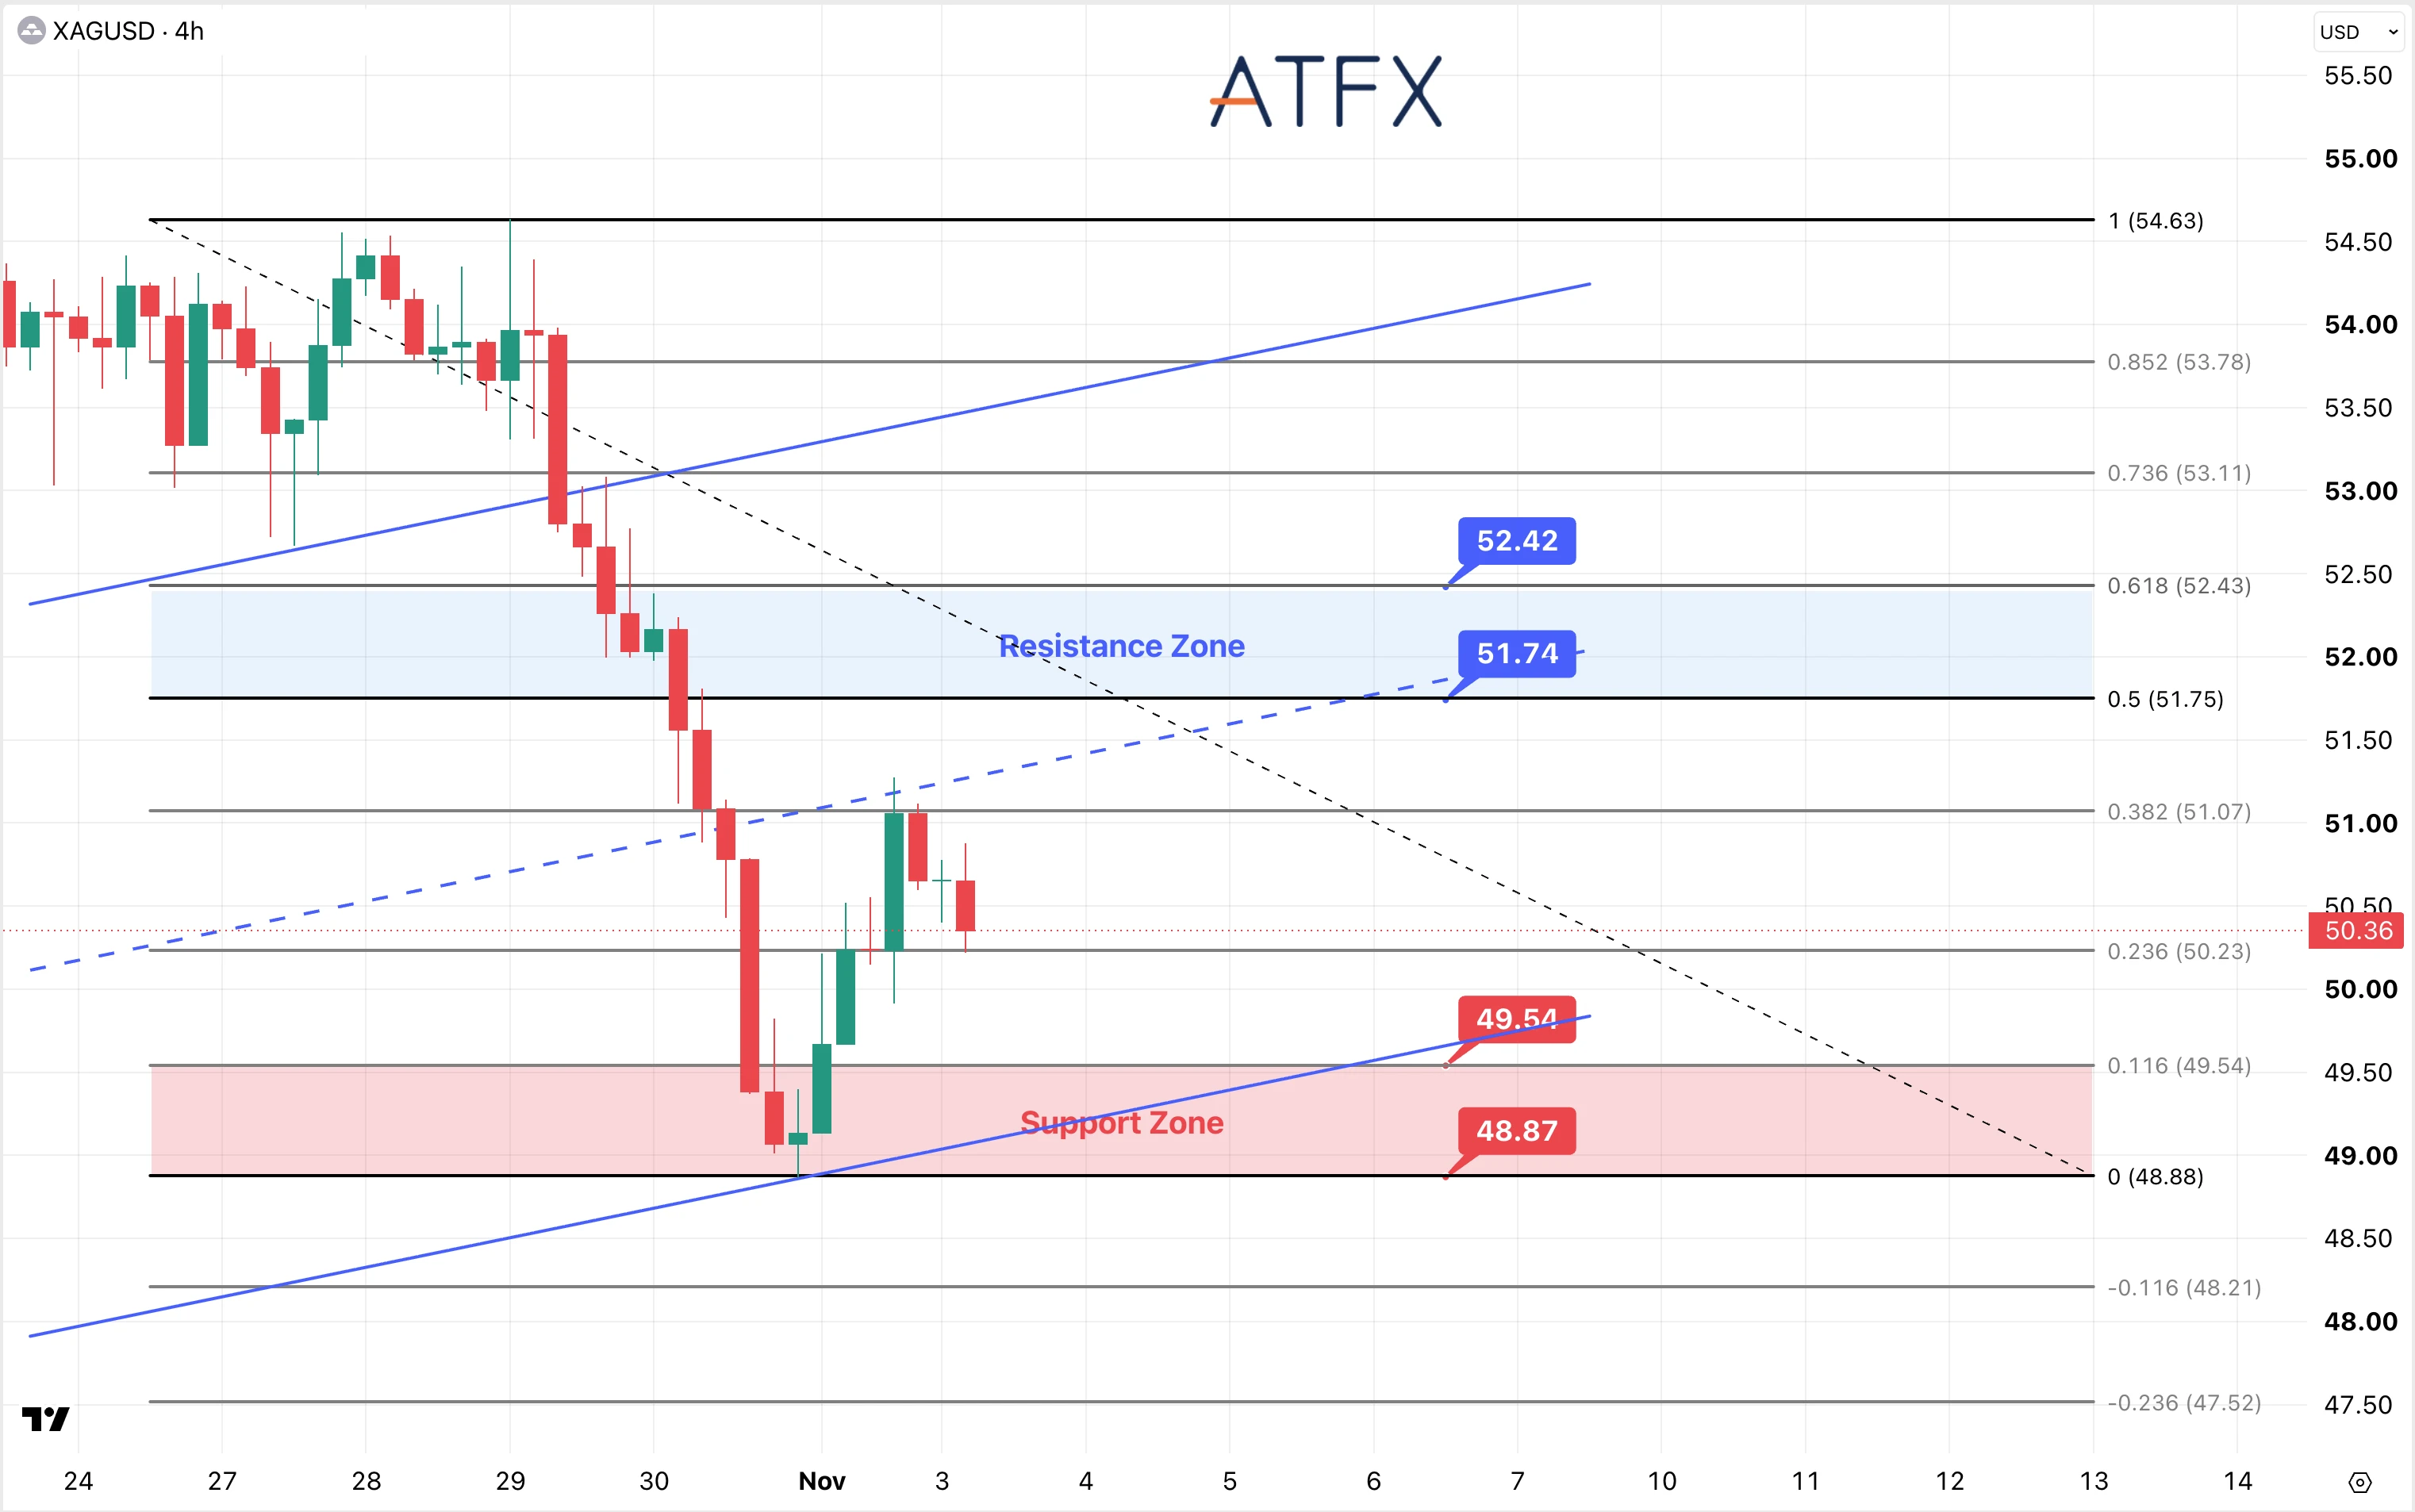
- Resistance: 51.74/52.42
- Support: 49.54/48.87
Analyst’s View: Gold rebounded as the dollar softened and the 10-year Treasury yield fell. Lower oil prices may ease inflation concerns, but the Fed could still hike rates. Election uncertainty and renewed military reports add another source of demand and volatility.
Wednesday’s ADP and ISM services data, followed by Friday’s payrolls, will help determine whether rate expectations change. Strong hiring or persistent price pressures could lift yields and make it harder for gold to extend its recovery.
Gold is near $3,948 after its rebound stalled around $3,963. Recovering $3,950 and $3,963 would improve the immediate outlook toward $3,976–$3,992. A break below $3,934 would expose $3,922 and then $3,909.
Silver is nearly $50.36 after retreating from around $51.10. Holding $50.23 would support stabilization, but $51.07 must be recovered before $51.74–$52.42 comes into view. Below $50.23, support is marked at $49.54 and $48.87.
Bias: Gold Neutral to Cautiously Bearish; Silver Cautiously Bearish
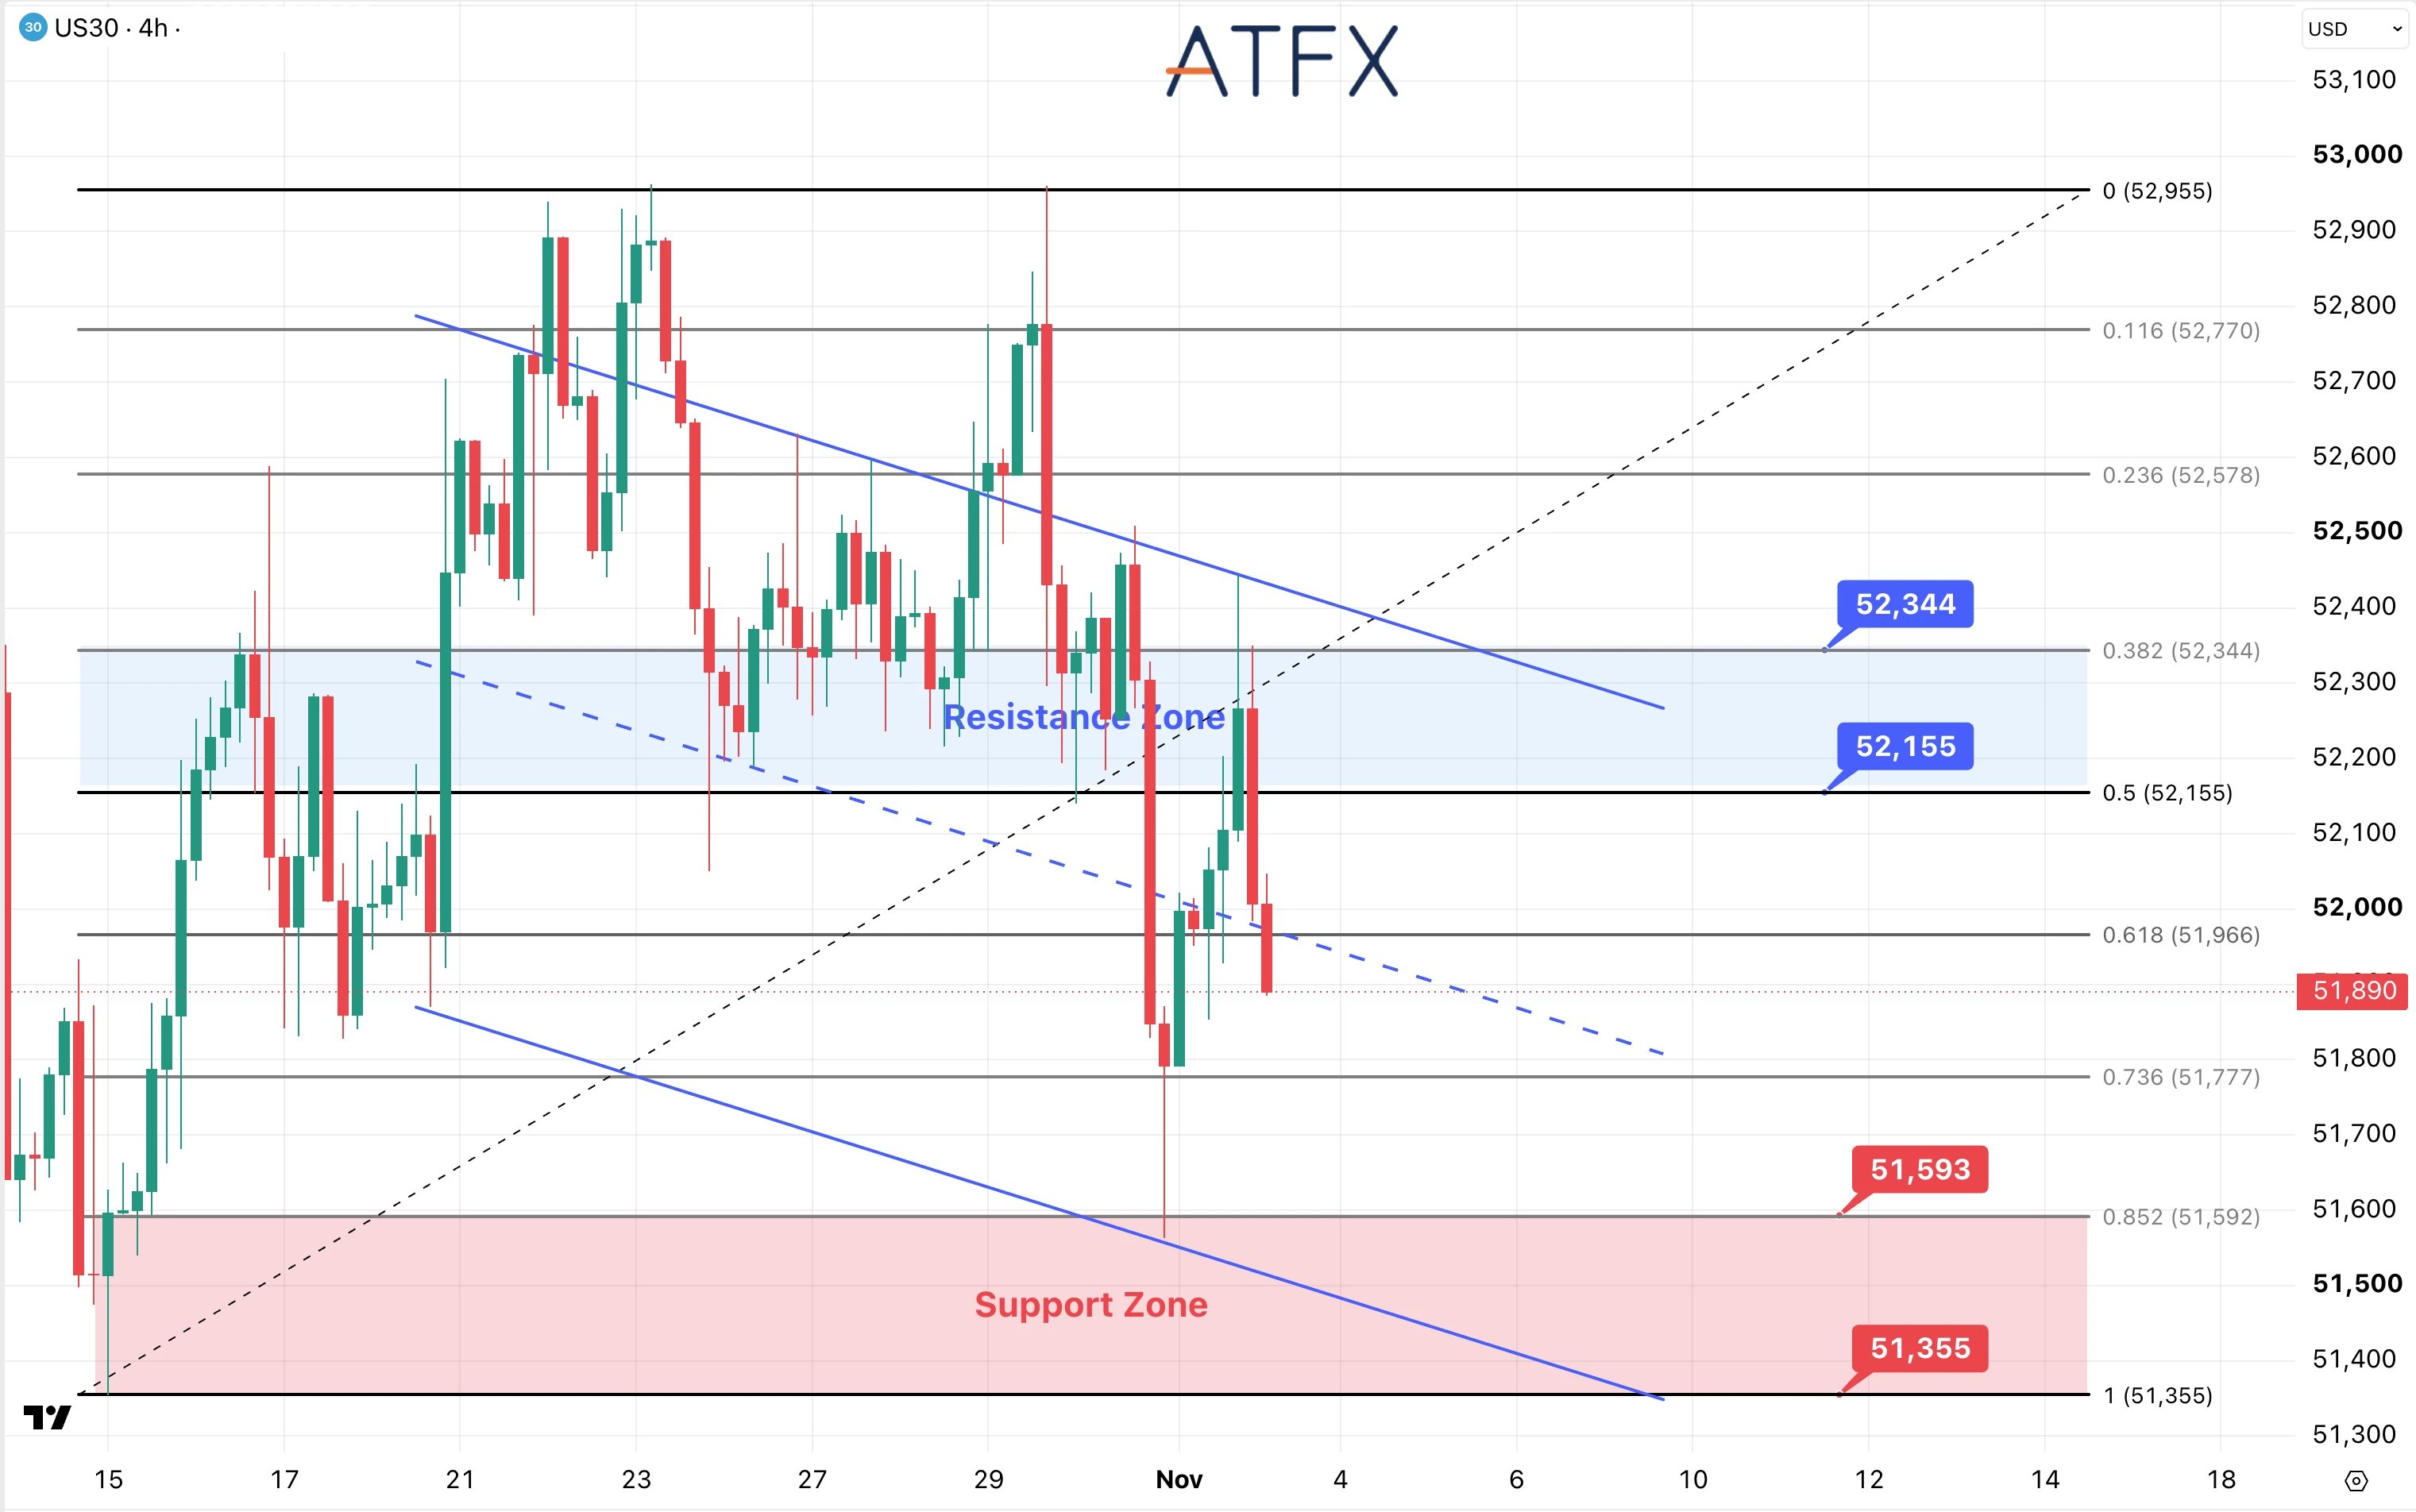
- Resistance: 52155/52344
- Support: 51593/51355
Analyst’s View: Dow rose 0.41% on Monday’s close as the technology decline had a smaller impact on its composition. ISM manufacturing at 55.5 signaled further expansion, but elevated costs remain a concern. Today’s factory orders and JOLTS data will update expectations for investment and hiring.
Election results could reshape expectations for fiscal policy and regulation. Wednesday’s Treasury financing announcement also matters for yields and corporate funding costs, following the government’s projection of $618 billion in borrowing this quarter.
DJIA is near 51,890 after a rebound failed below 52,344. Price is below 51,966 and the descending channel’s midline. Below 51,777, attention turns to 51,593 and 51,355. Holding those supports could allow another recovery attempt, but the descending channel still favors caution while price remains below the resistance zone.
Bias: Cautiously Bearish
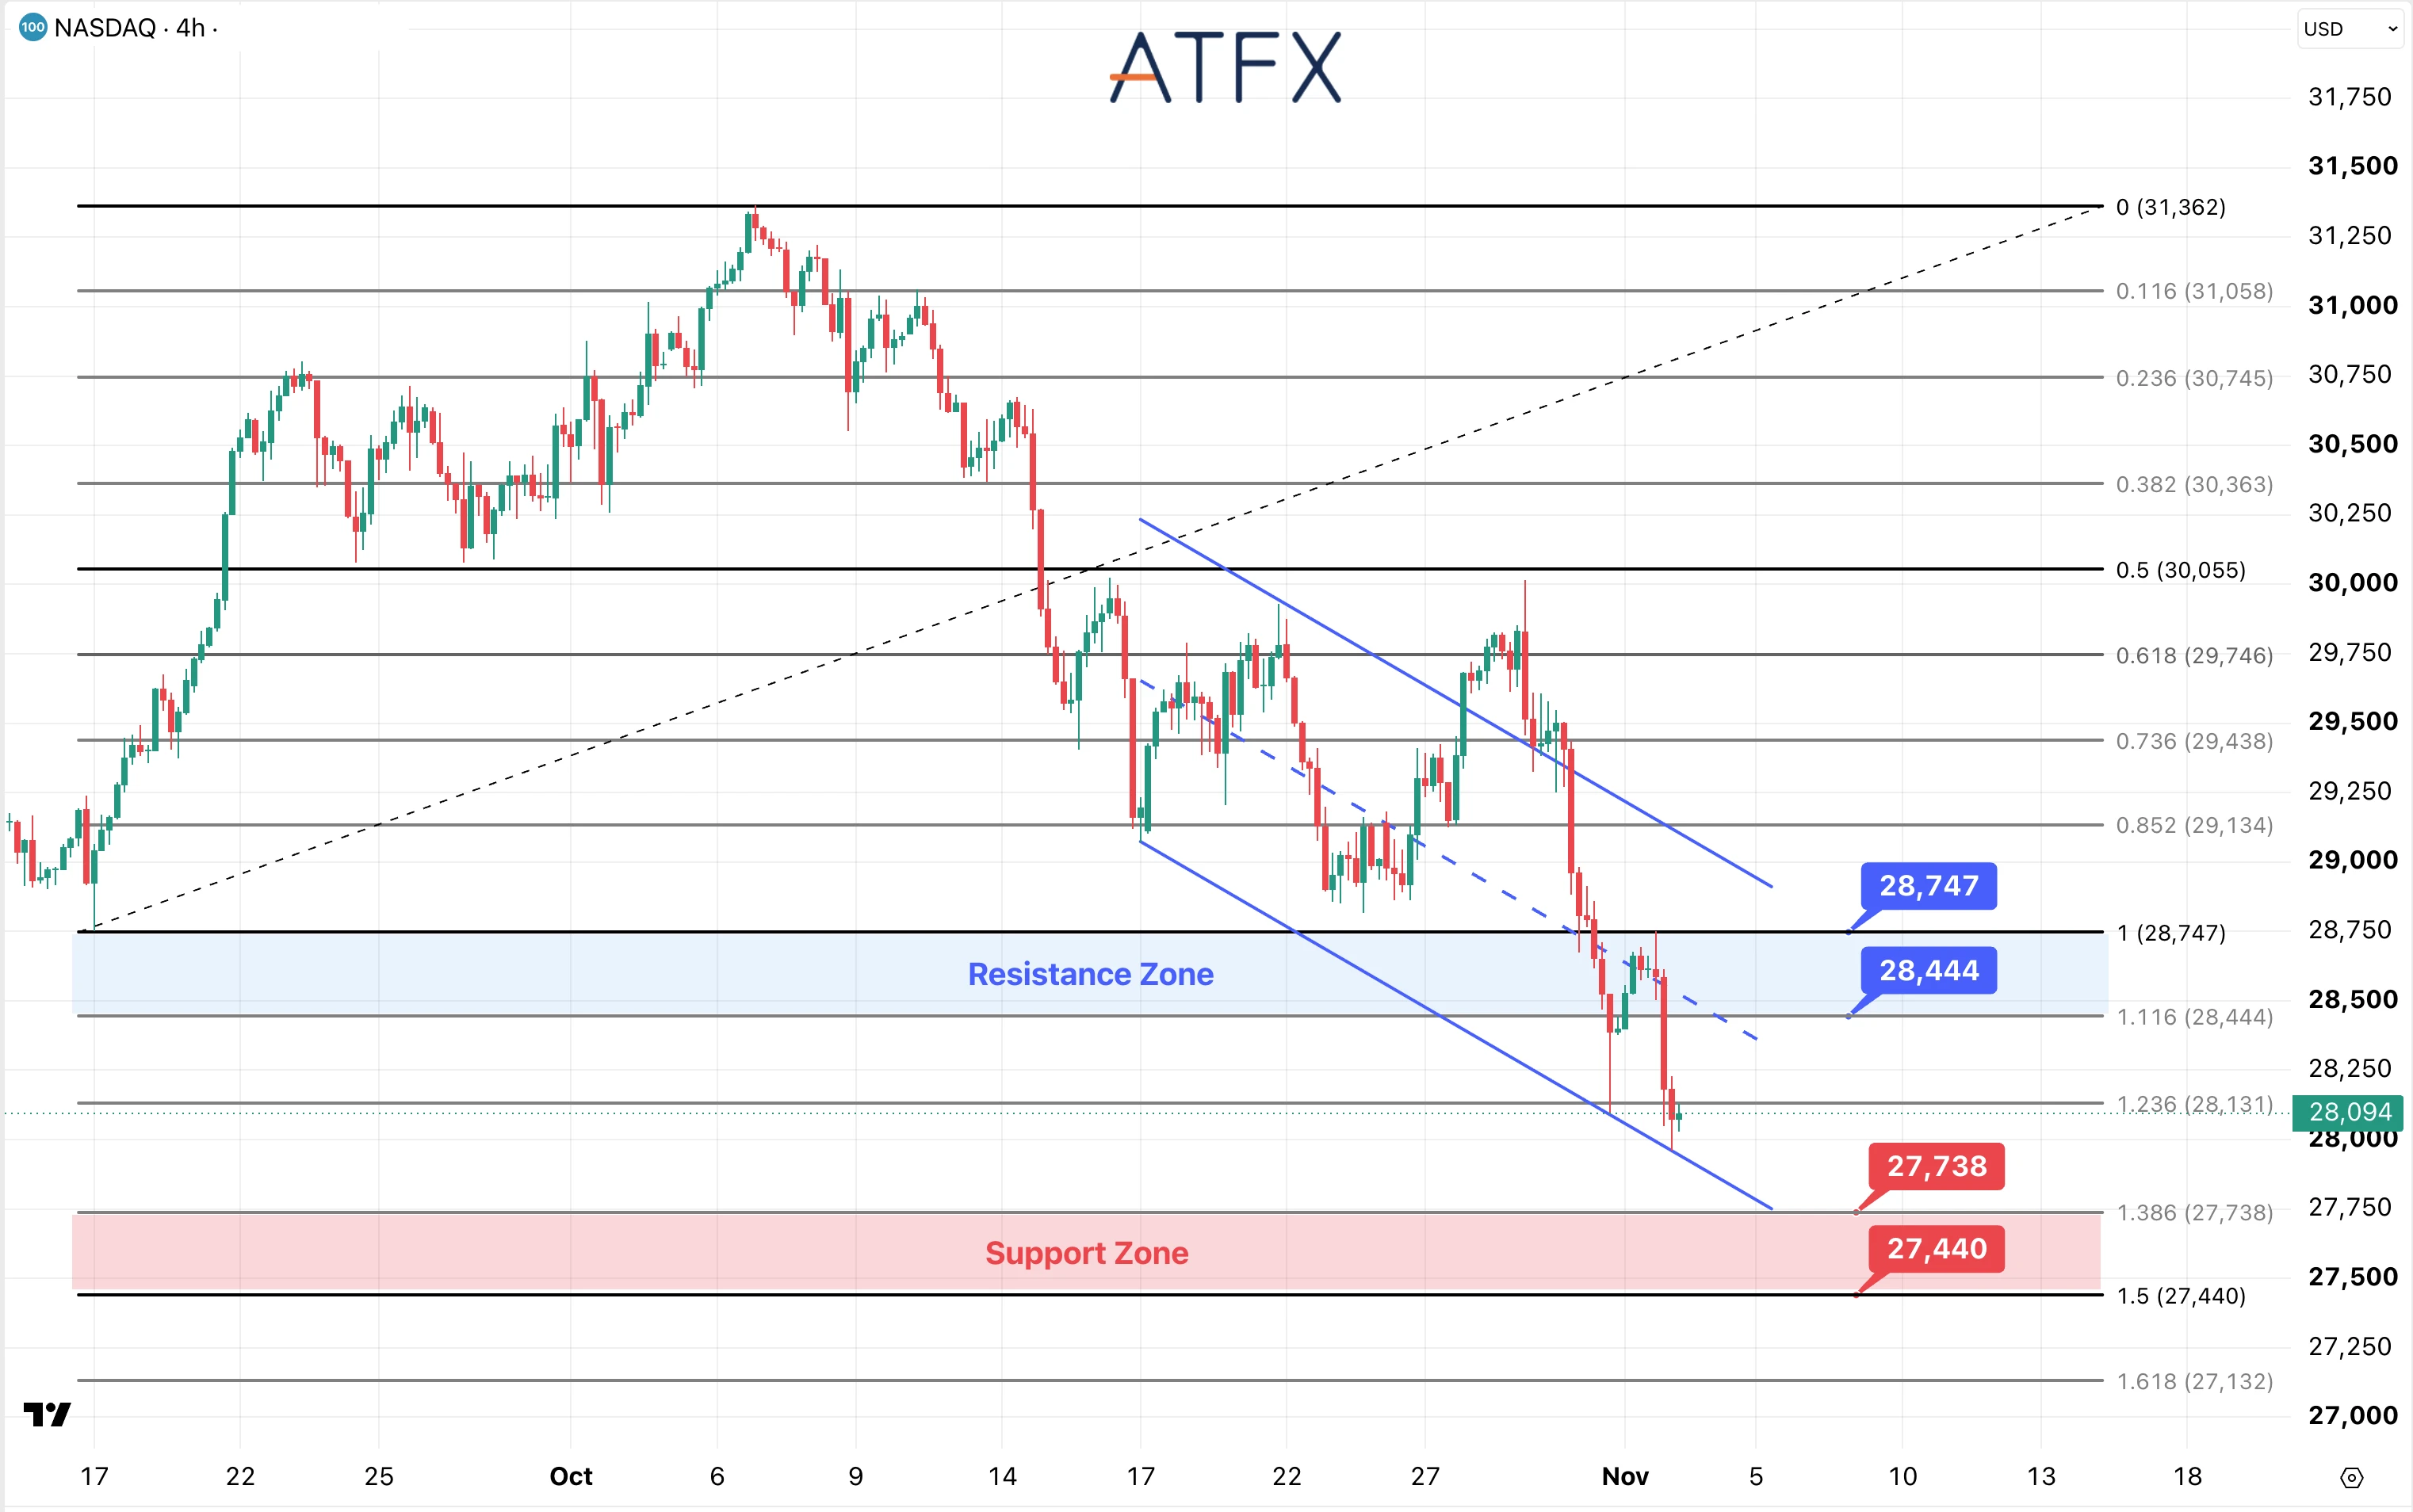
- Resistance: 28444/28747
- Support: 27738/27440
Analyst’s View: Oracle’s $20 billion financing plan and Marvell’s $115 billion Lumentum deal have renewed scrutiny of AI funding needs. Investors are weighing future returns against borrowing costs and dilution. Lower energy prices alone have not resolved those concerns.
Apple’s revenue and earnings beat expectations after Monday’s close, while Palantir raised its annual outlook. AMD reports after Tuesday’s close. Its data center demand and spending guidance will help gauge whether stronger growth can offset financing concerns.
NAS100 is near 28,094, below 28,131 and the descending channel’s midline. Failure to recover 28,131 would leave 27,738 and 27,440 in focus. Price is near the channel’s lower boundary, so a bounce is possible, but the broader structure remains weak until resistance is recovered.
Bias: Cautiously Bearish
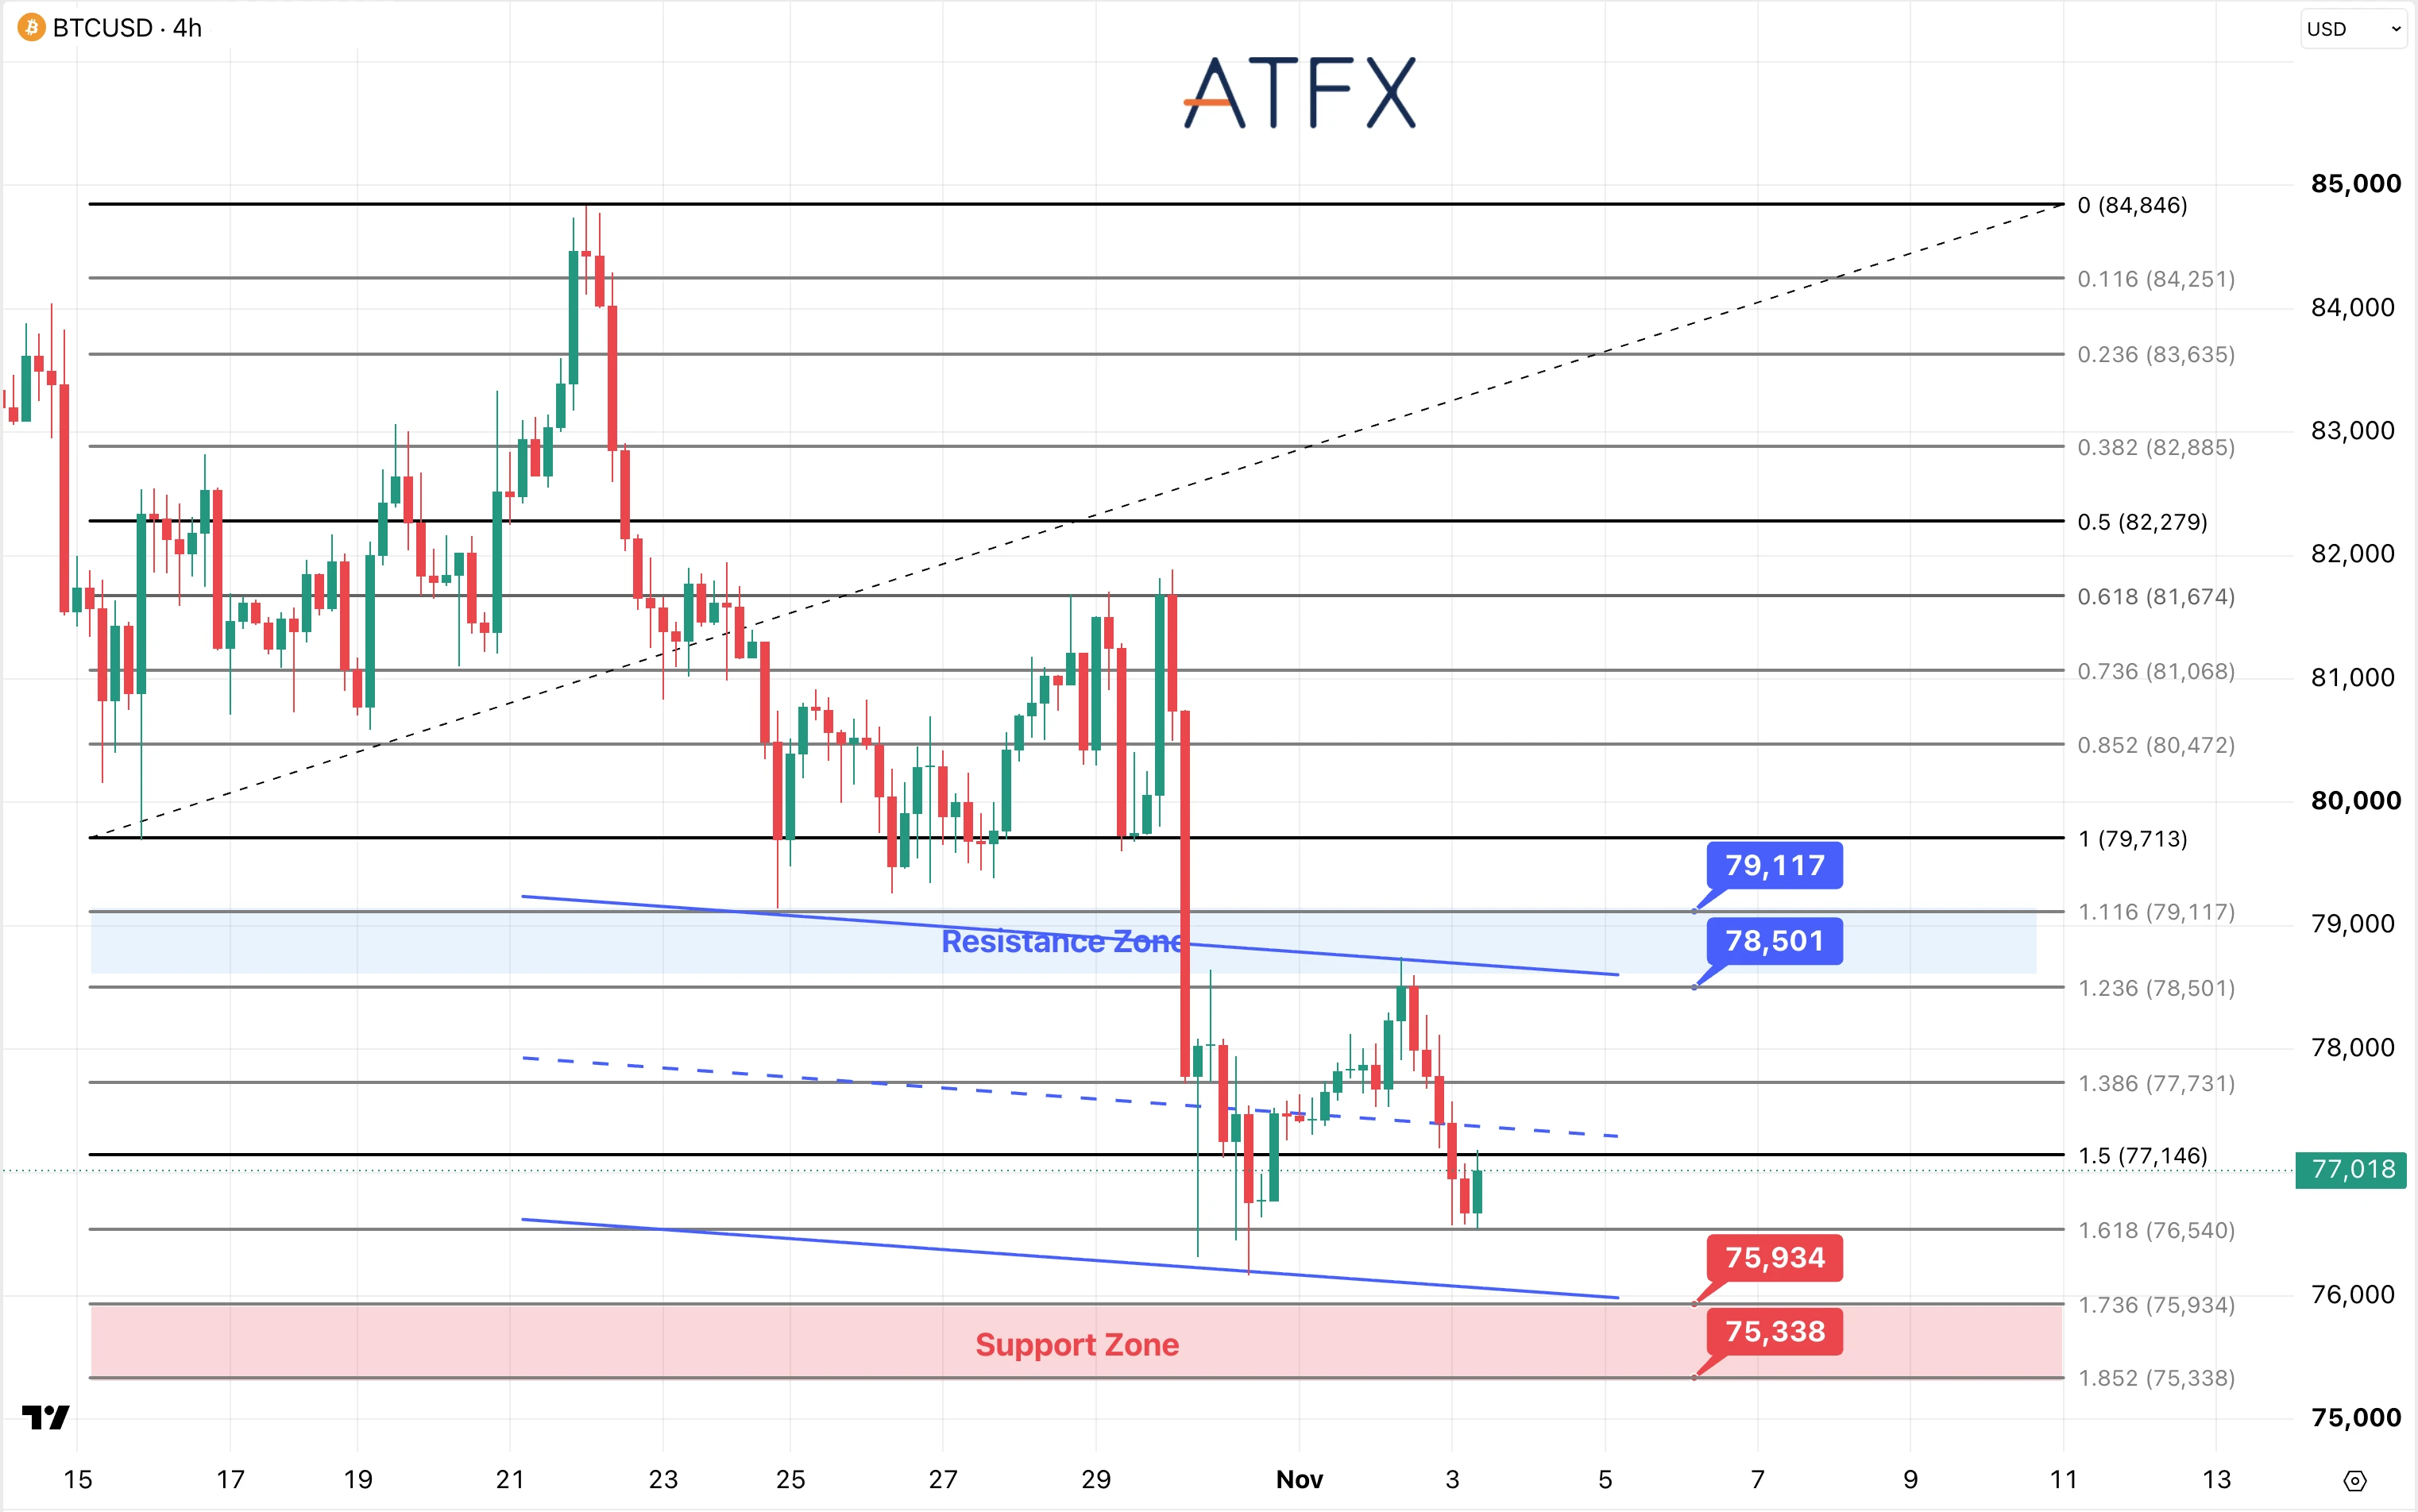
- Resistance: 78501/79117
- Support: 75934/75338
Analyst’s View: Bitcoin remains sensitive to weak technology sentiment and uncertainty about US rates. The midterms and AMD’s earnings could influence near-term risk appetite, while Friday’s payrolls will inform the Fed’s outlook. Exchange security remains a concern after last week’s disruption.
Bitcoin is near $77,018 after its recovery stalled around $78,501. It remains below $77,146 and the descending channel’s midline. If $76,540 gives way, attention shifts to $75,934 and $75,338.
Bias: Cautiously Bearish
Disclaimer: This analysis is for reference only and does not constitute investment advice.