

Key Takeaways
Today’s Focus: US ADP weekly employment at 20:15, durable goods orders at 20:30, and consumer confidence at 22:00 (GMT+8) will provide updates on private-sector hiring, durable goods orders, and household sentiment. The ADP measure reports a four-week moving average of weekly changes in private-sector employment. Durable goods orders are forecast to rise 0.4%, while consumer confidence is expected to be 80, indicating a slight easing. |
Global Market Review 27/10/2026
- Monday, October 26: Dow rose 146.42 points, or 0.28%, to 52,361.58.
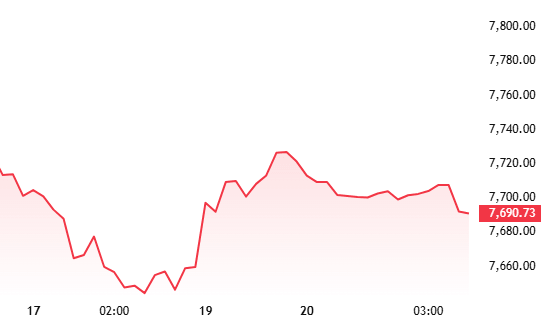
- S&P 500 gained 0.70% to 7,676.77, and Nasdaq Composite advanced 0.82% to 26,169.38, as renewed interest in AI shares supported the market.
- The early Tuesday oil snapshot showed WTI at $101.01, down 0.74%, and Brent at $114.79, down 0.88%.
- The Treasury snapshot showed the 2-year yield near 4.71% and the 10-year near 4.99%.
- Gold’s four-hour chart was near $4,008, following Monday’s recovery above $4,000.
Economic Calendar
Key Events on October 27 (GMT+8)
| Time (GMT+8) | Event | Importance |
|---|---|---|
| 20:00 | US Building Permits MoM Final SEP | ** |
| 20:15 | US ADP Weekly Employment Change | *** |
| 20:30 | US Durable Goods Orders MoM SEP | *** |
| 22:00 | US CB Consumer Confidence OCT | ** |
| 22:00 | US New Home Sales SEP | ** |
| 22:00 | US Richmond Fed Manufacturing Index OCT | ** |
Key Events on October 28 (GMT+8)
- Upcoming earnings: Microsoft and Alphabet report after the US close on October 28, corresponding to early October 29 in GMT+8.
| Time (GMT+8) | Event | Importance |
|---|---|---|
| 01:00 | ECB President Lagarde Speech | *** |
| 04:30 | US API Crude Oil Stock Change | *** |
| 08:30 | AU CPI YoY SEP | ** |
| 09:00 | RBNZ Interest Rate Decision | *** |
| 15:00 | Germany GfK Consumer Confidence NOV | ** |
| 21:45 | BoC Interest Rate Decision | *** |
| 22:30 | US EIA Crude Oil Stocks Change | ** |
Markets Analysis 27/10/2026
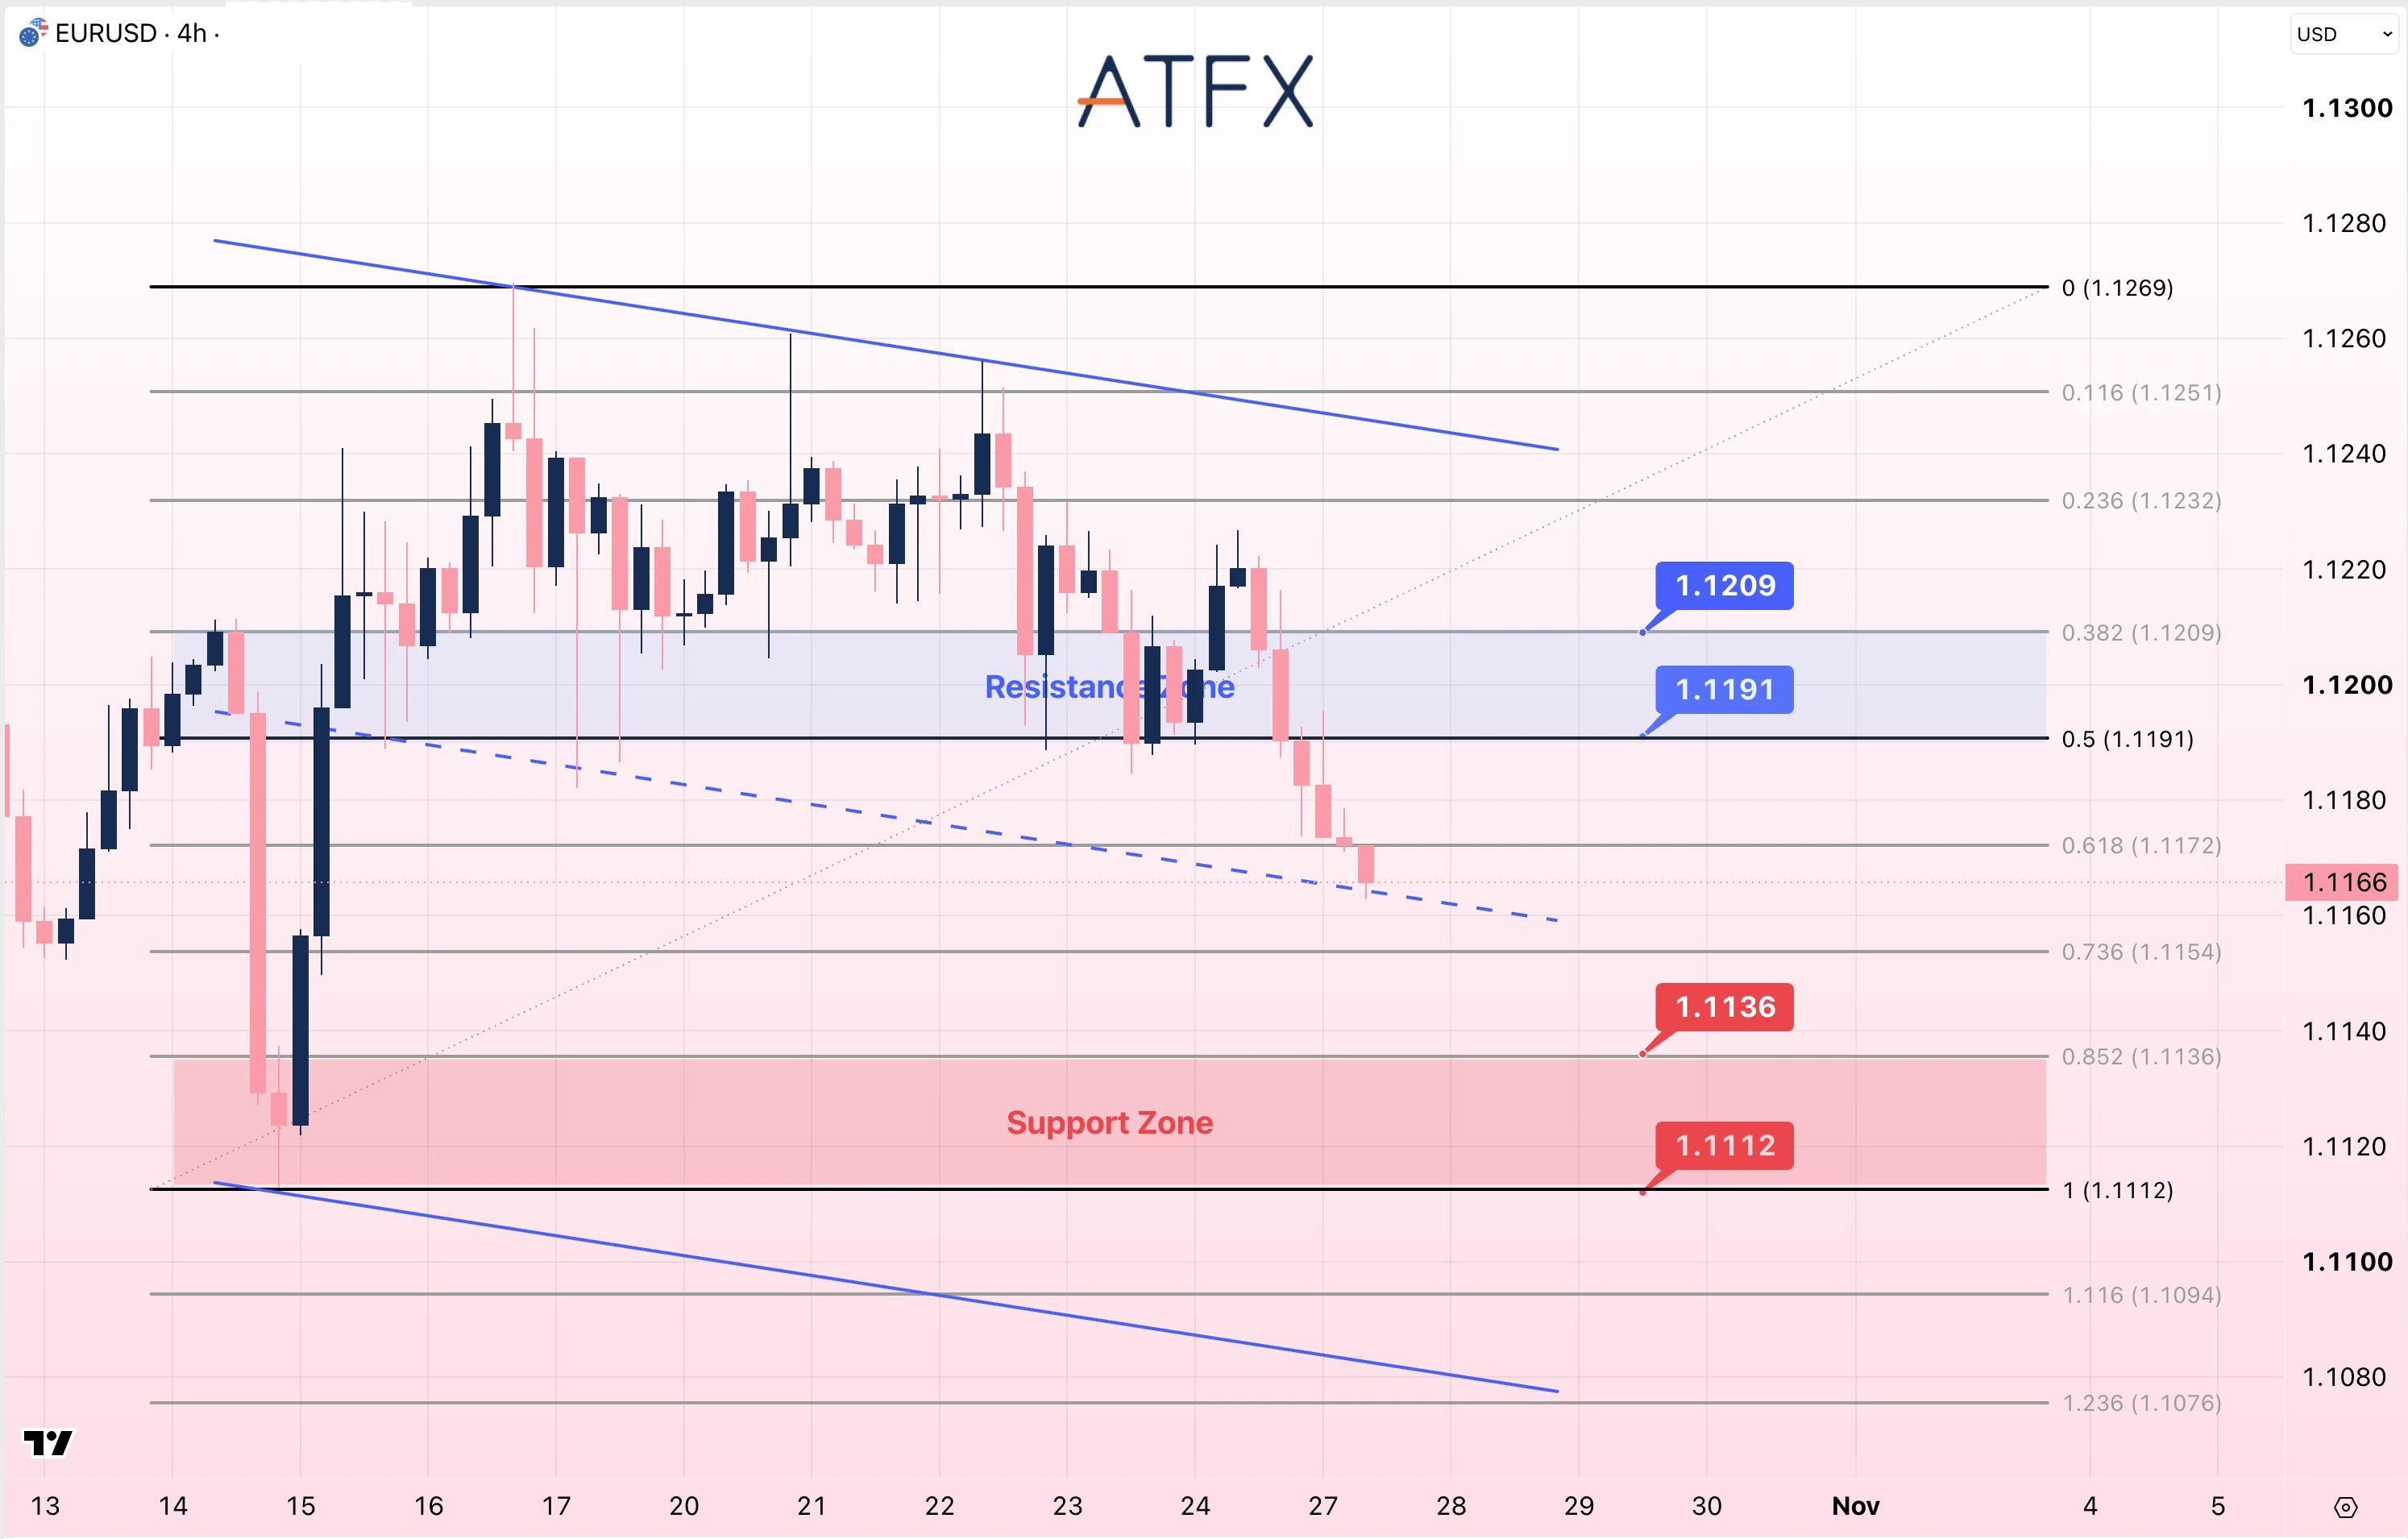
- Resistance: 1.1191/1.1209
- Support: 1.1136/1.1112
Analyst’s View: Moody’s decision to leave France’s rating unchanged has provided some relief for French bonds, though fiscal uncertainty remains a constraint on the Euro. With the Fed and ECB both expected to hold this week, attention is on whether their guidance shifts expectations for December and the relative interest-rate outlook.
EUR/USD is near 1.1166 after falling from the 1.1220 area. Price is near the descending channel’s midline but remains below the 1.1172 Fibonacci level. A move below 1.1154 would bring the marked supports at 1.1136 and 1.1112 into focus.
Bias: Cautiously Bearish
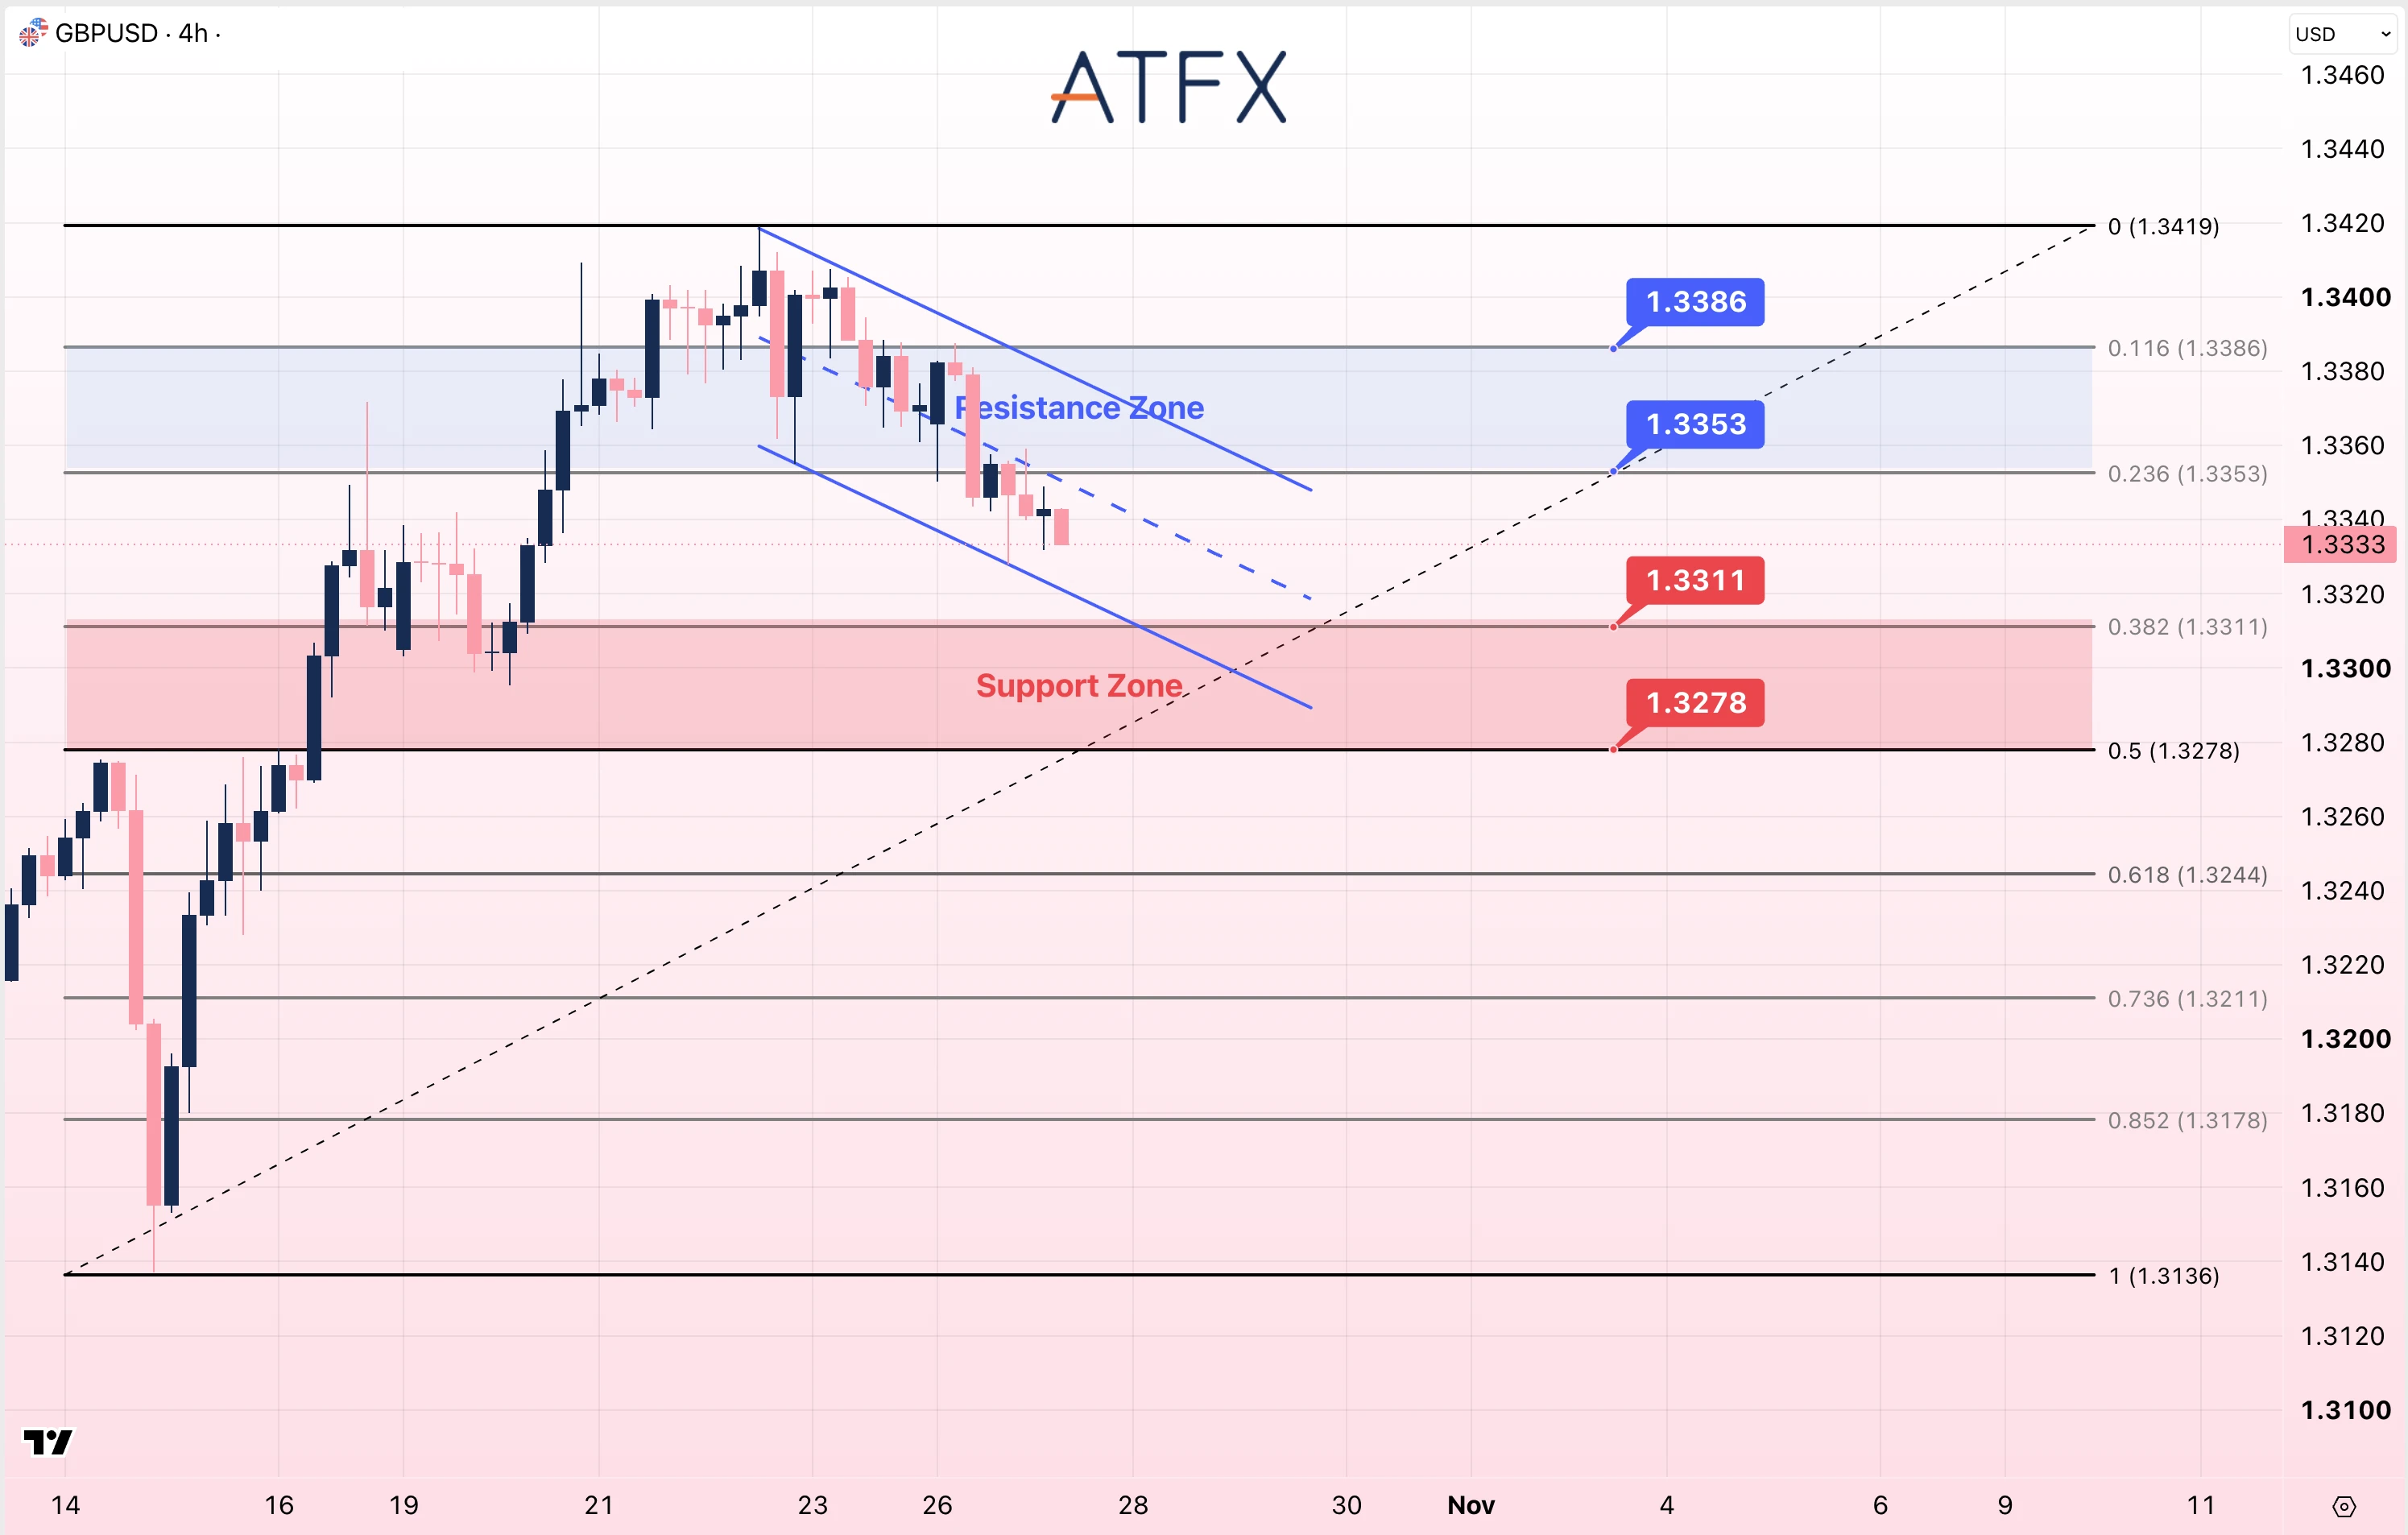
- Resistance: 1.3353/1.3386
- Support: 1.3311/1.3278
Analyst’s View: The Oct 28 UK Budget adds uncertainty ahead of the Fed, with investors weighing whether fiscal plans back growth while keeping debt sustainable. UK inflation at 3.5% supports expectations for a BoE hike in November, though the market reaction will also hinge on Dollar moves and how the Budget is received.
GBP/USD hovers near 1.3333, after slipping from 1.3419 and drifting within the lower half of its descending channel. Support sits at 1.3311, then 1.3278. A rebound above 1.3353 would strengthen the outlook toward 1.3386; staying below keeps the pullback intact.
Bias: Cautiously Bearish
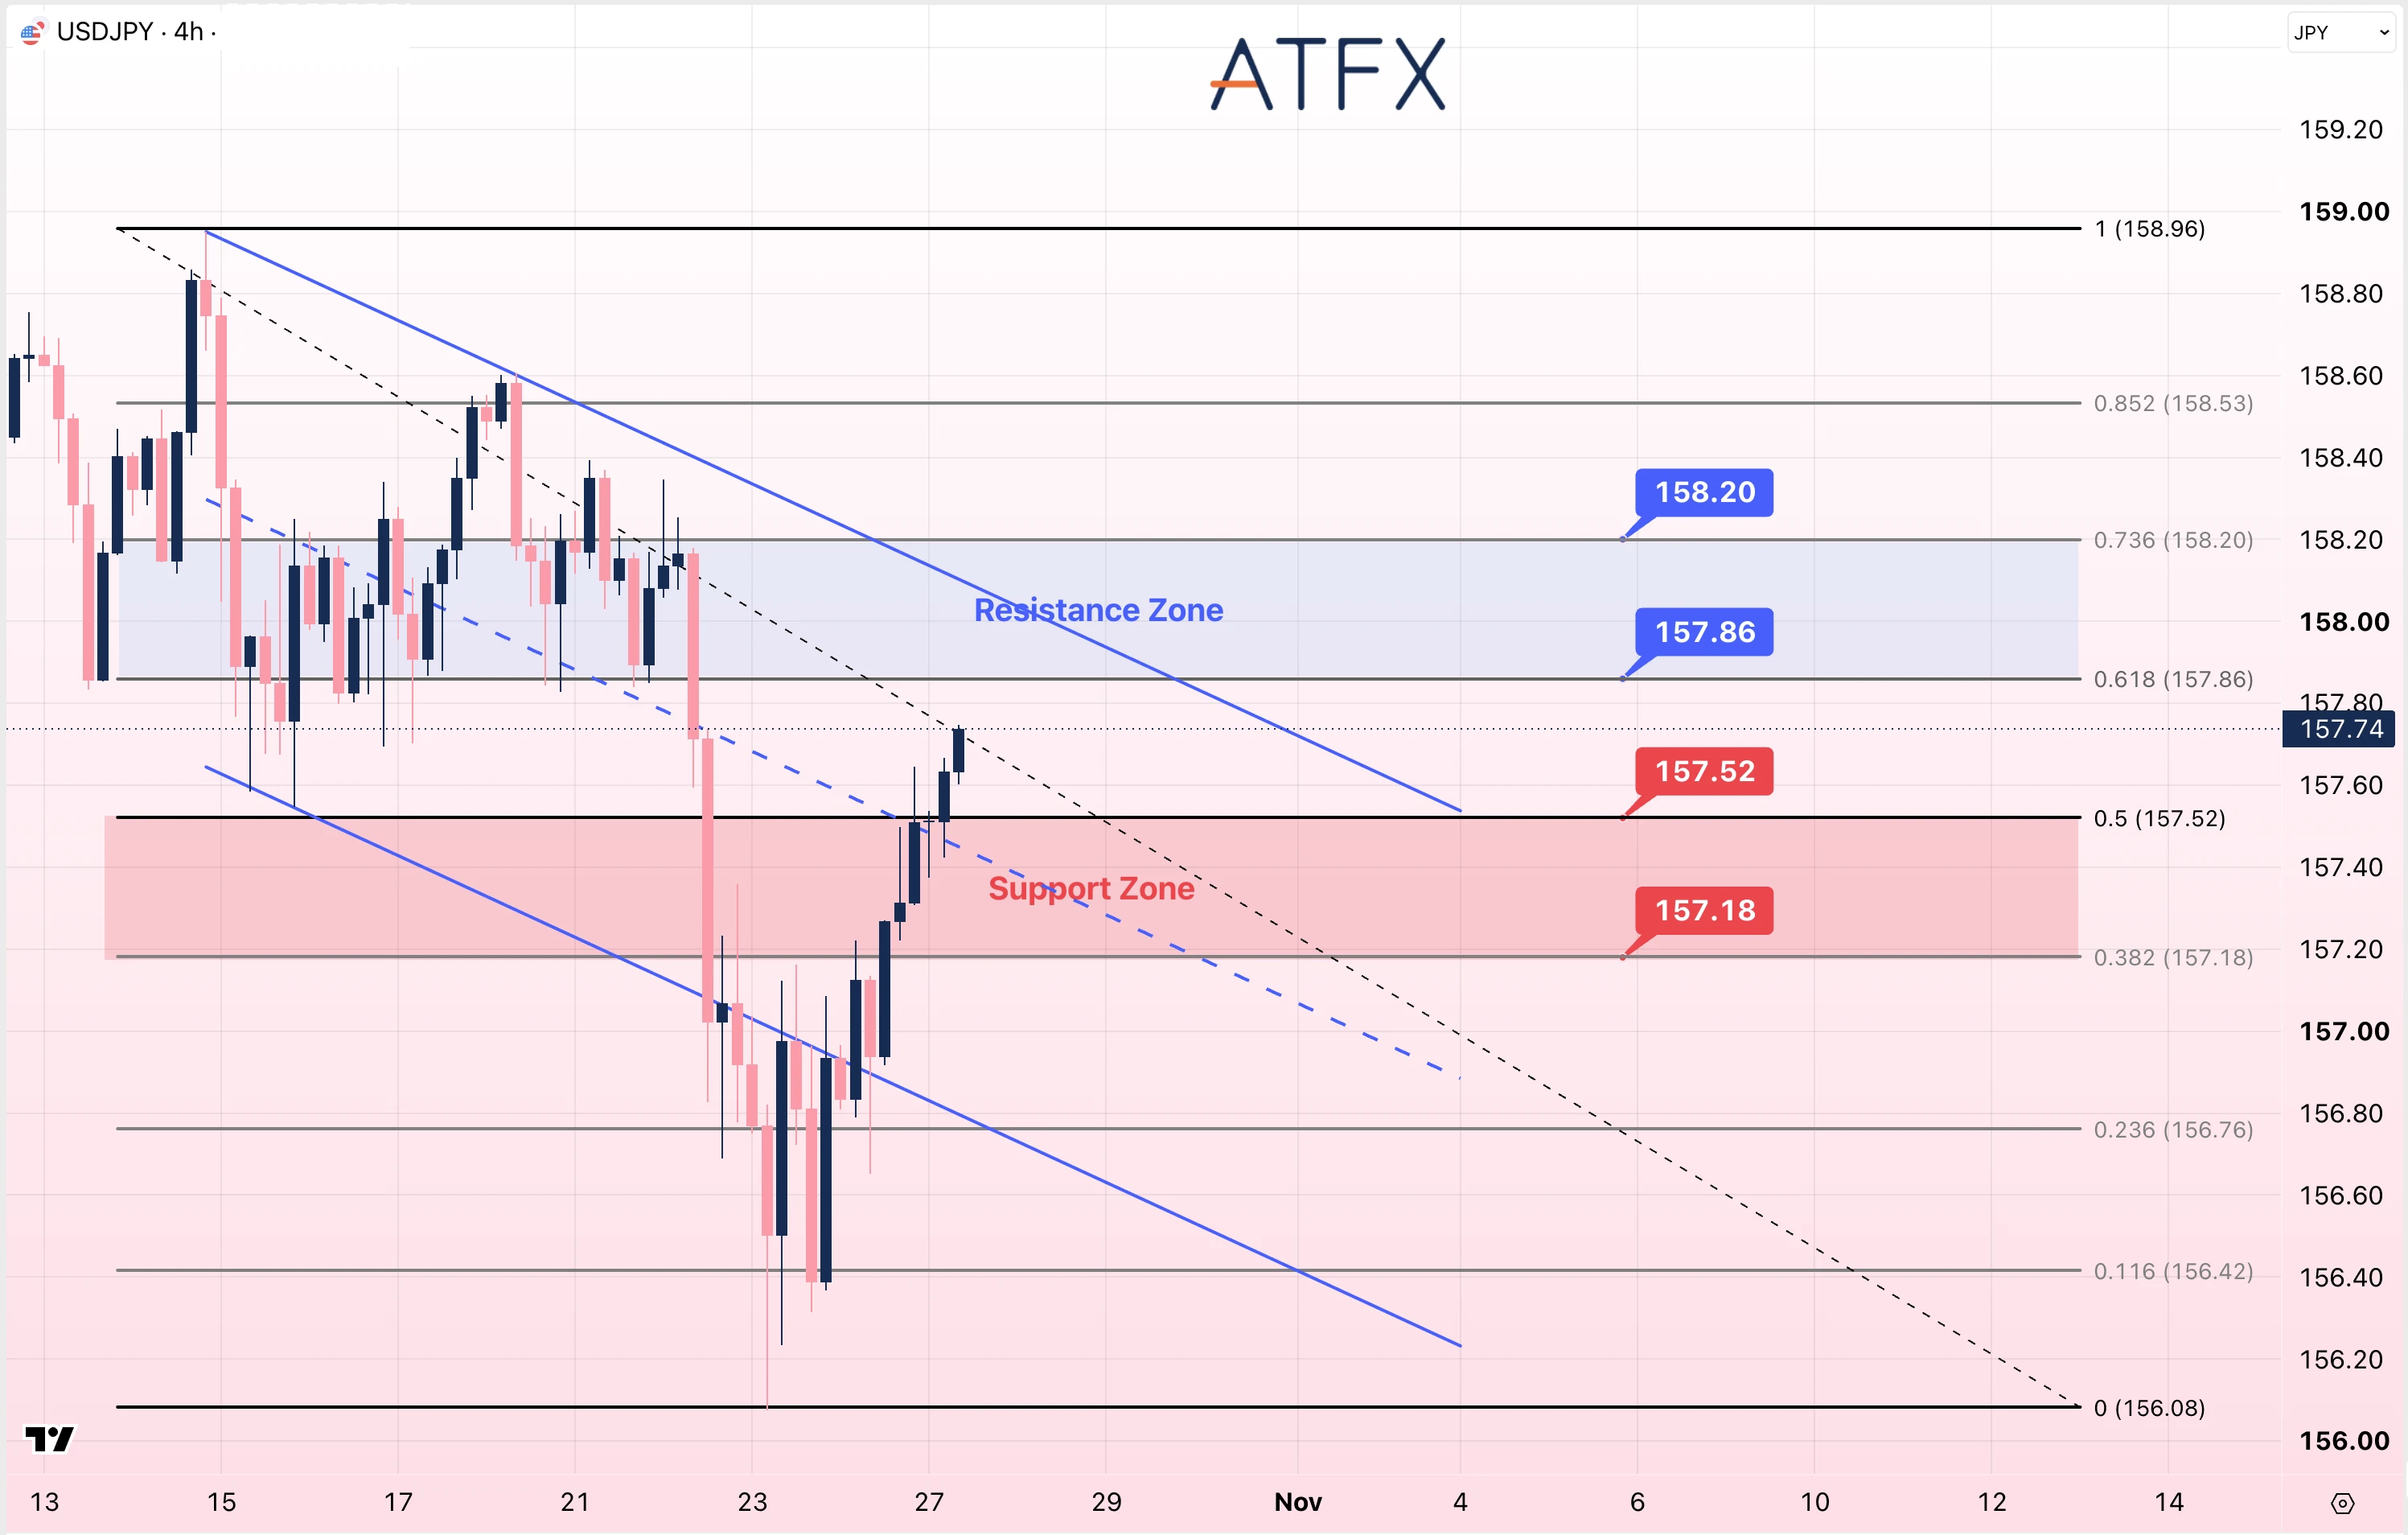
- Resistance: 157.86/158.20
- Support: 157.52/157.18
Analyst’s View: The yen has given back some recent gains as traders line up for the Fed and Friday’s BoJ decision. The still-wide US–Japan rate gap keeps the dollar supported, while Japan’s core inflation staying above 2% keeps BoJ tightening in the spotlight. With expectations largely for a hold, the real focus is likely on updated forecasts and December guidance.
USD/JPY is near 157.74 after rebounding from the 156.40 area and trading above the descending channel’s midline. A break above 157.86 would set up a test of 158.20. Holding above 157.52 would support the rebound.
Bias: Neutral to Cautiously Bullish
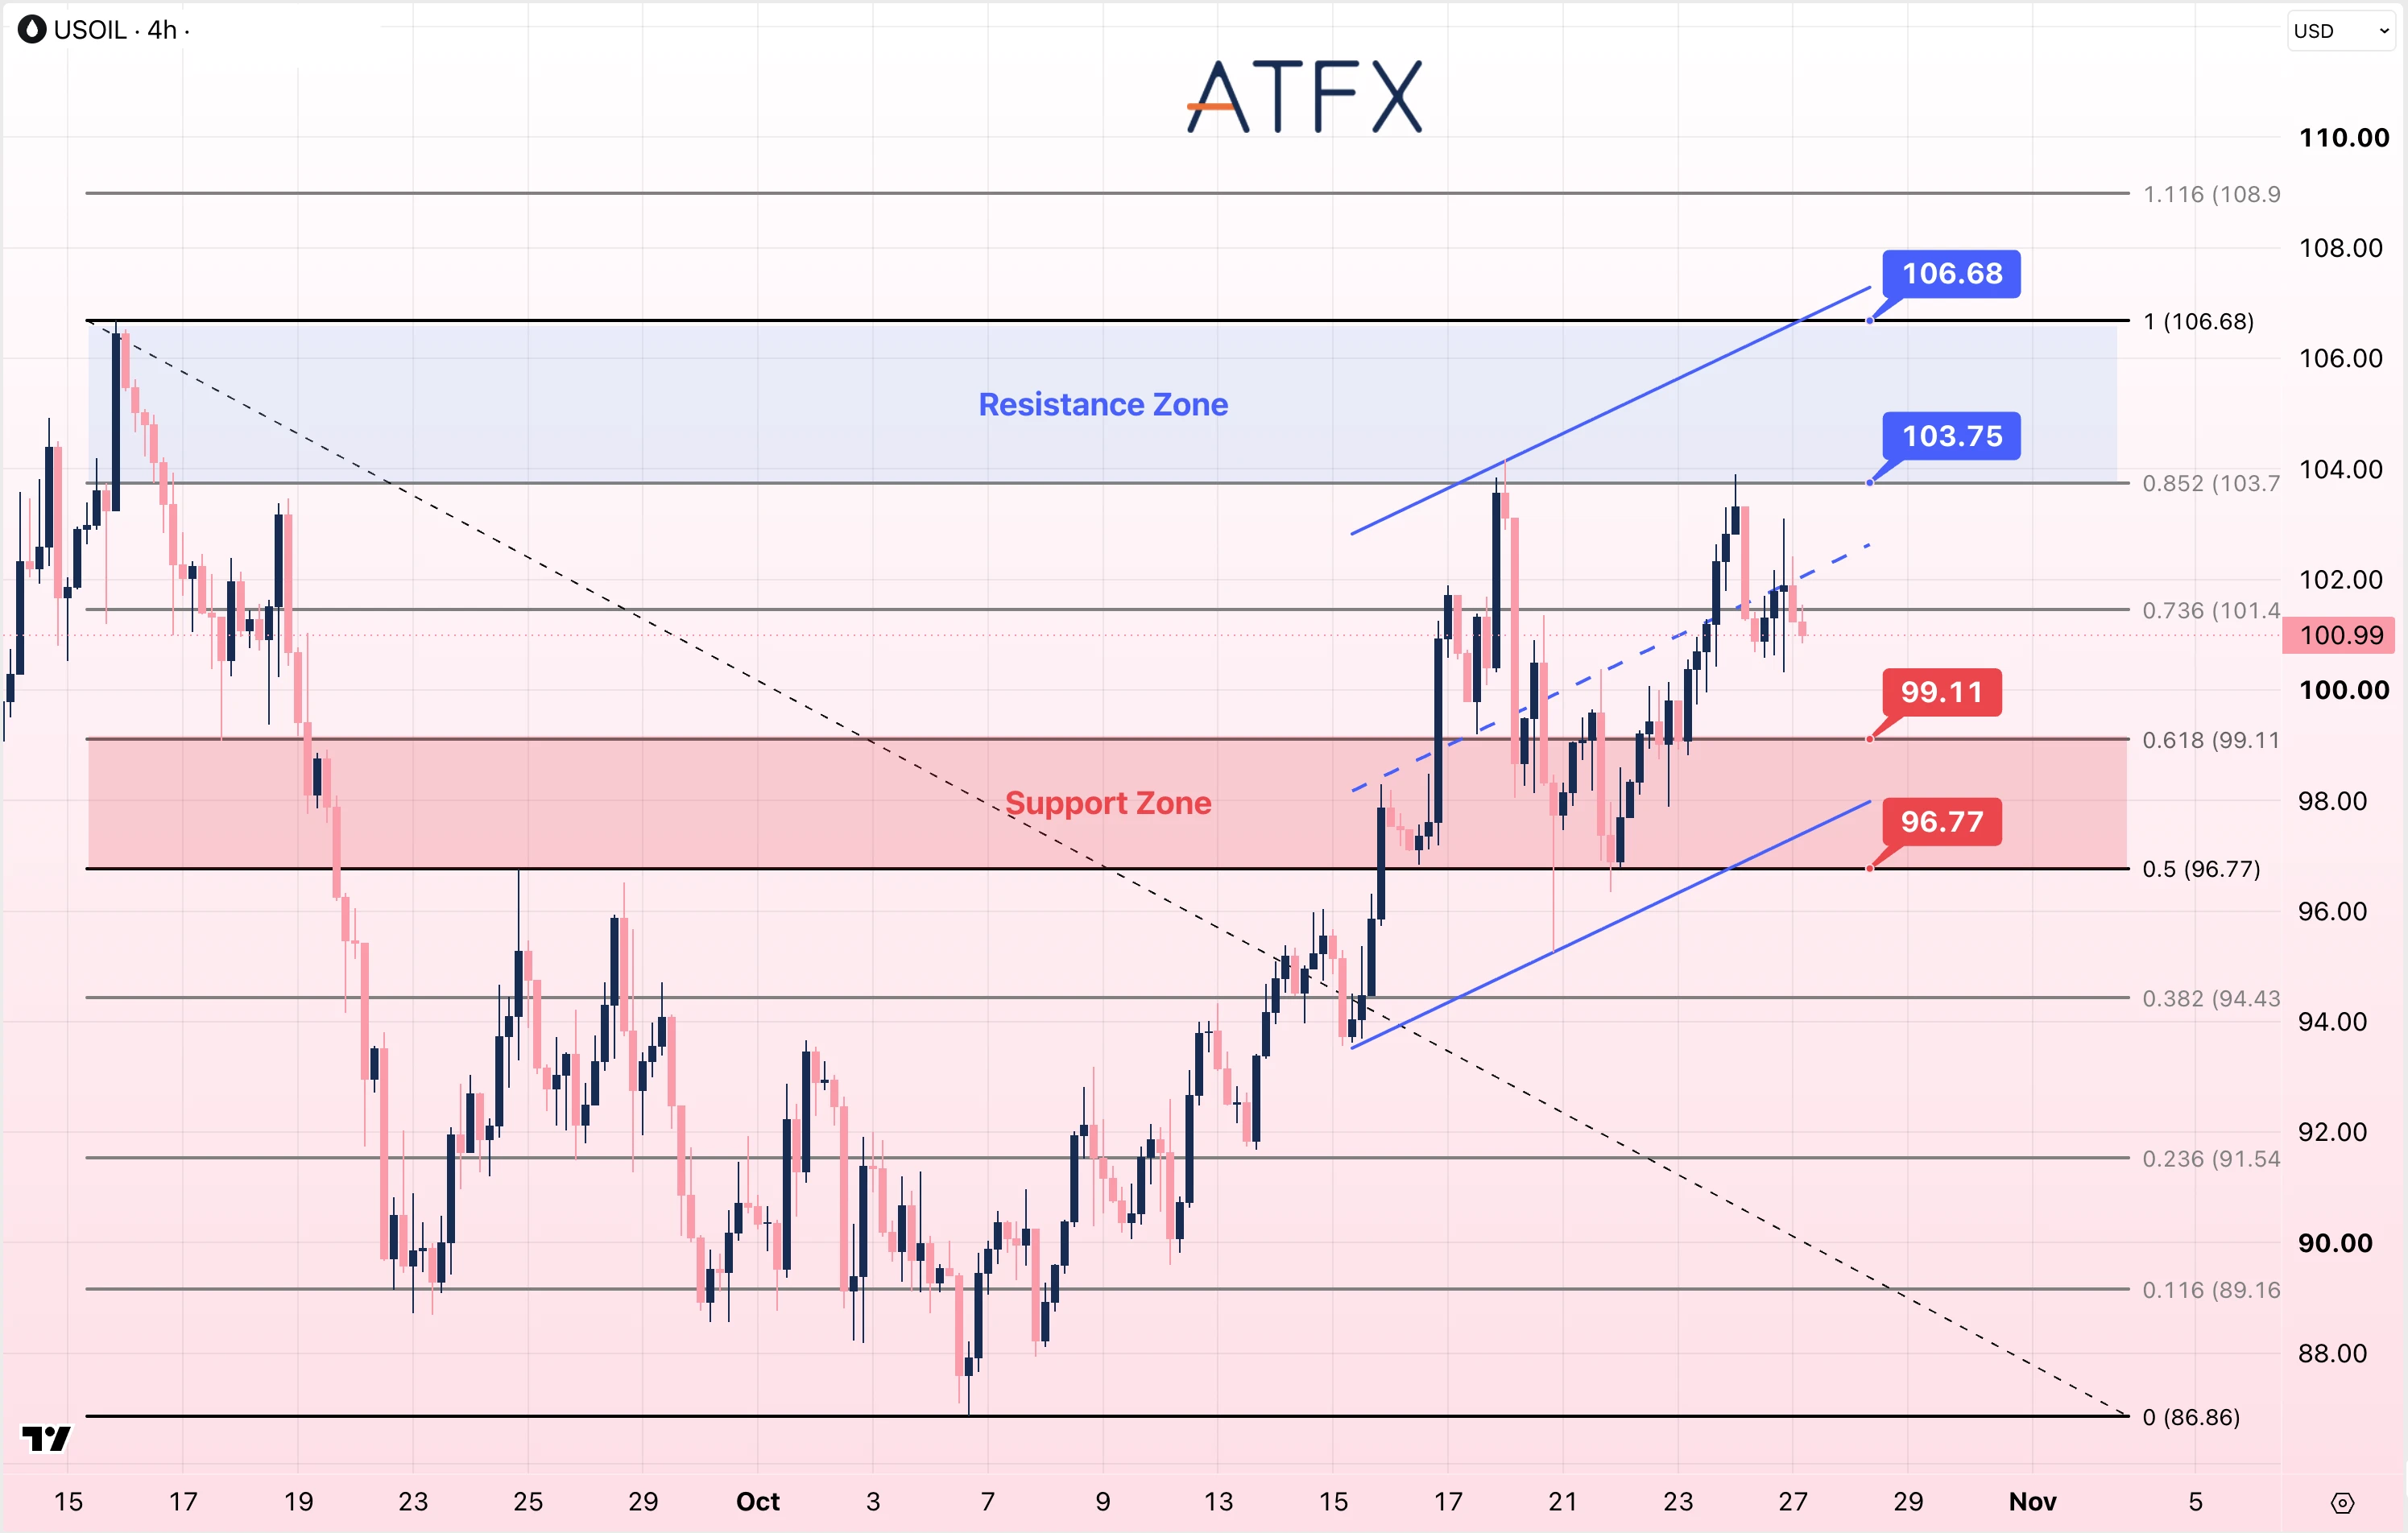
- Resistance: 103.75/106.68
- Support: 99.11/96.77
Analyst’s View: Iran-related regional talks have eased fears of a wider conflict, allowing oil to continue its pullback. However, threats to Saudi infrastructure mean supply risk remains. The upcoming API and EIA inventory reports will be a key near-term check on demand and supply, though any renewed escalation could quickly flip the market’s outlook.
USOIL is nearly $100.99, below the $101.45 Fibonacci level and the rising channel’s midline, after retreating from $103.75. A failure to reclaim $101.45 would leave $99.11 and then $96.77 in focus.
Bias: Neutral to Cautiously Bearish
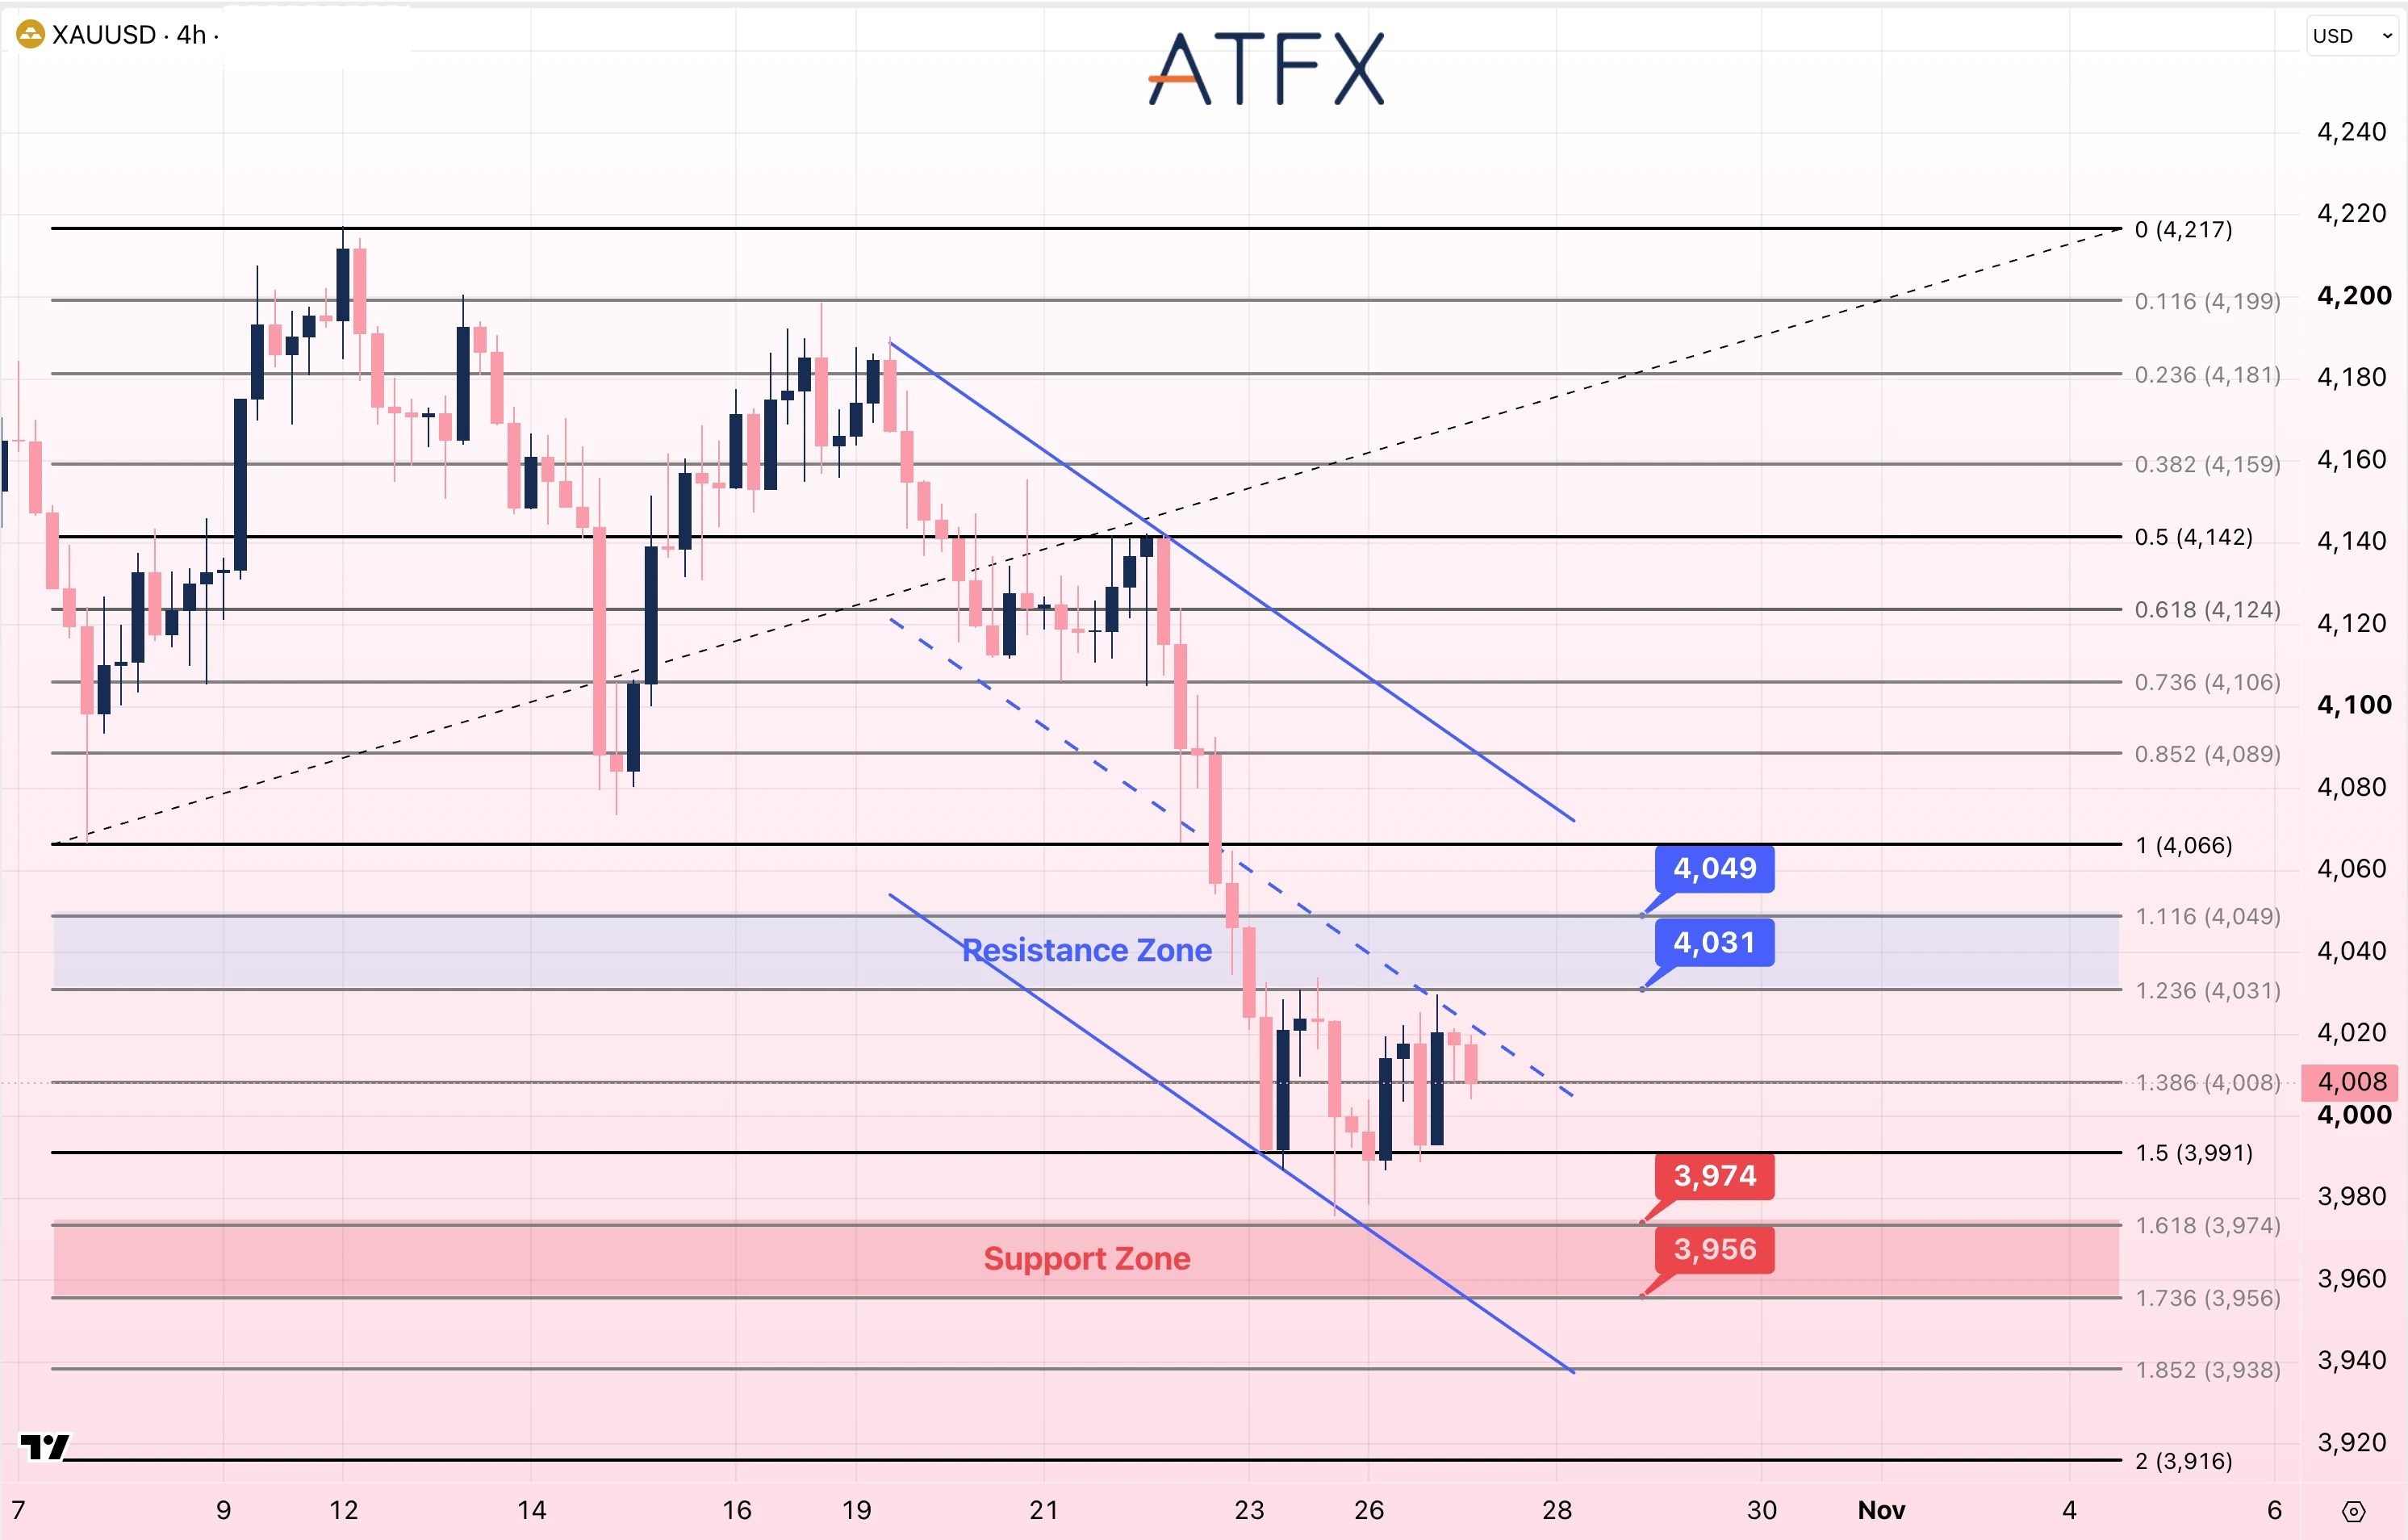
- Resistance: 4031/4049
- Support: 3974/3956
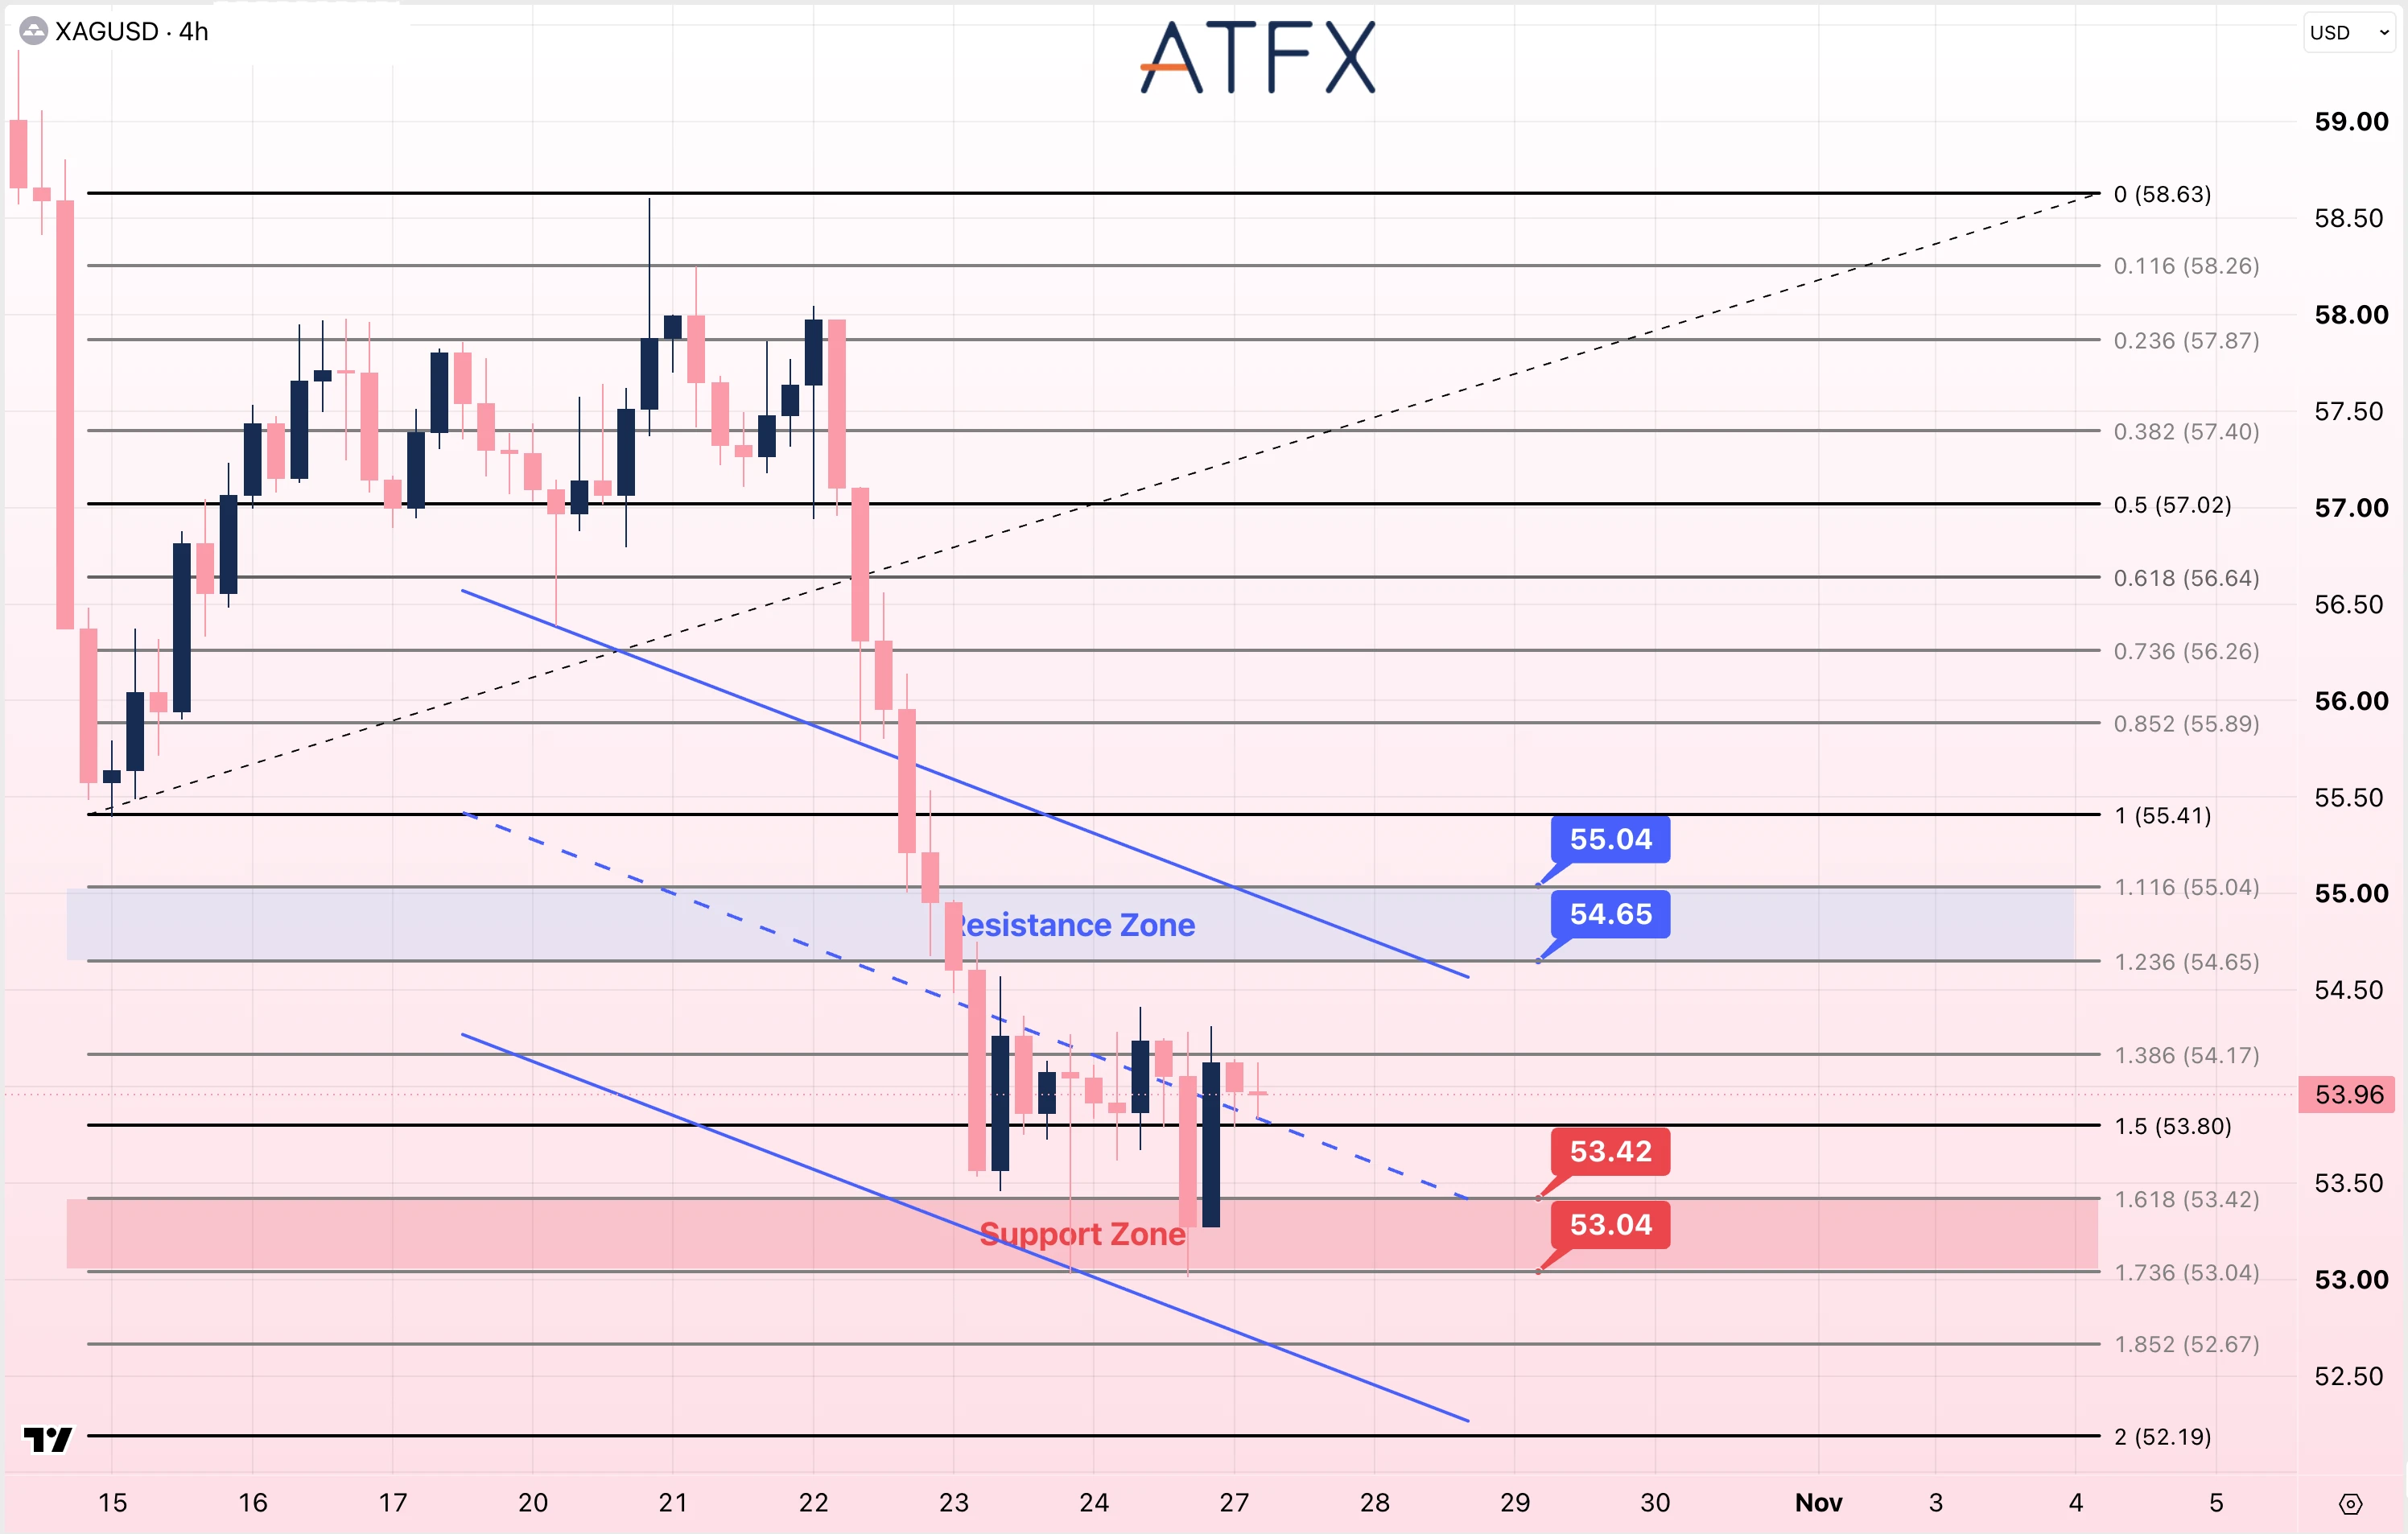
- Resistance: 54.65/55.04
- Support: 53.42/53.04
Analyst’s View: Gold bounced back above $4,000 on Monday as easing oil prices helped cool near-term inflation worries. Still, energy costs remain high, and investors are watching for signs that the Fed could tighten further. The key will be the policy statement and Chair Warsh’s guidance, which could show whether the rebound can become more durable.
Gold: Around $4,008, stuck in the lower part of a descending channel and below $4,031–$4,049. Reclaiming that range would improve the outlook. If $4,000 and $3,991 break, focus shifts to $3,974 and $3,956. Silver: Near $53.96, below $54.17 and still trending lower. A recovery above $54.17 targets $54.65 and $55.04. Below $53.80, support sits at $53.42 and $53.04.
Bias: Gold Neutral to Cautiously Bearish; Silver Cautiously Bearish
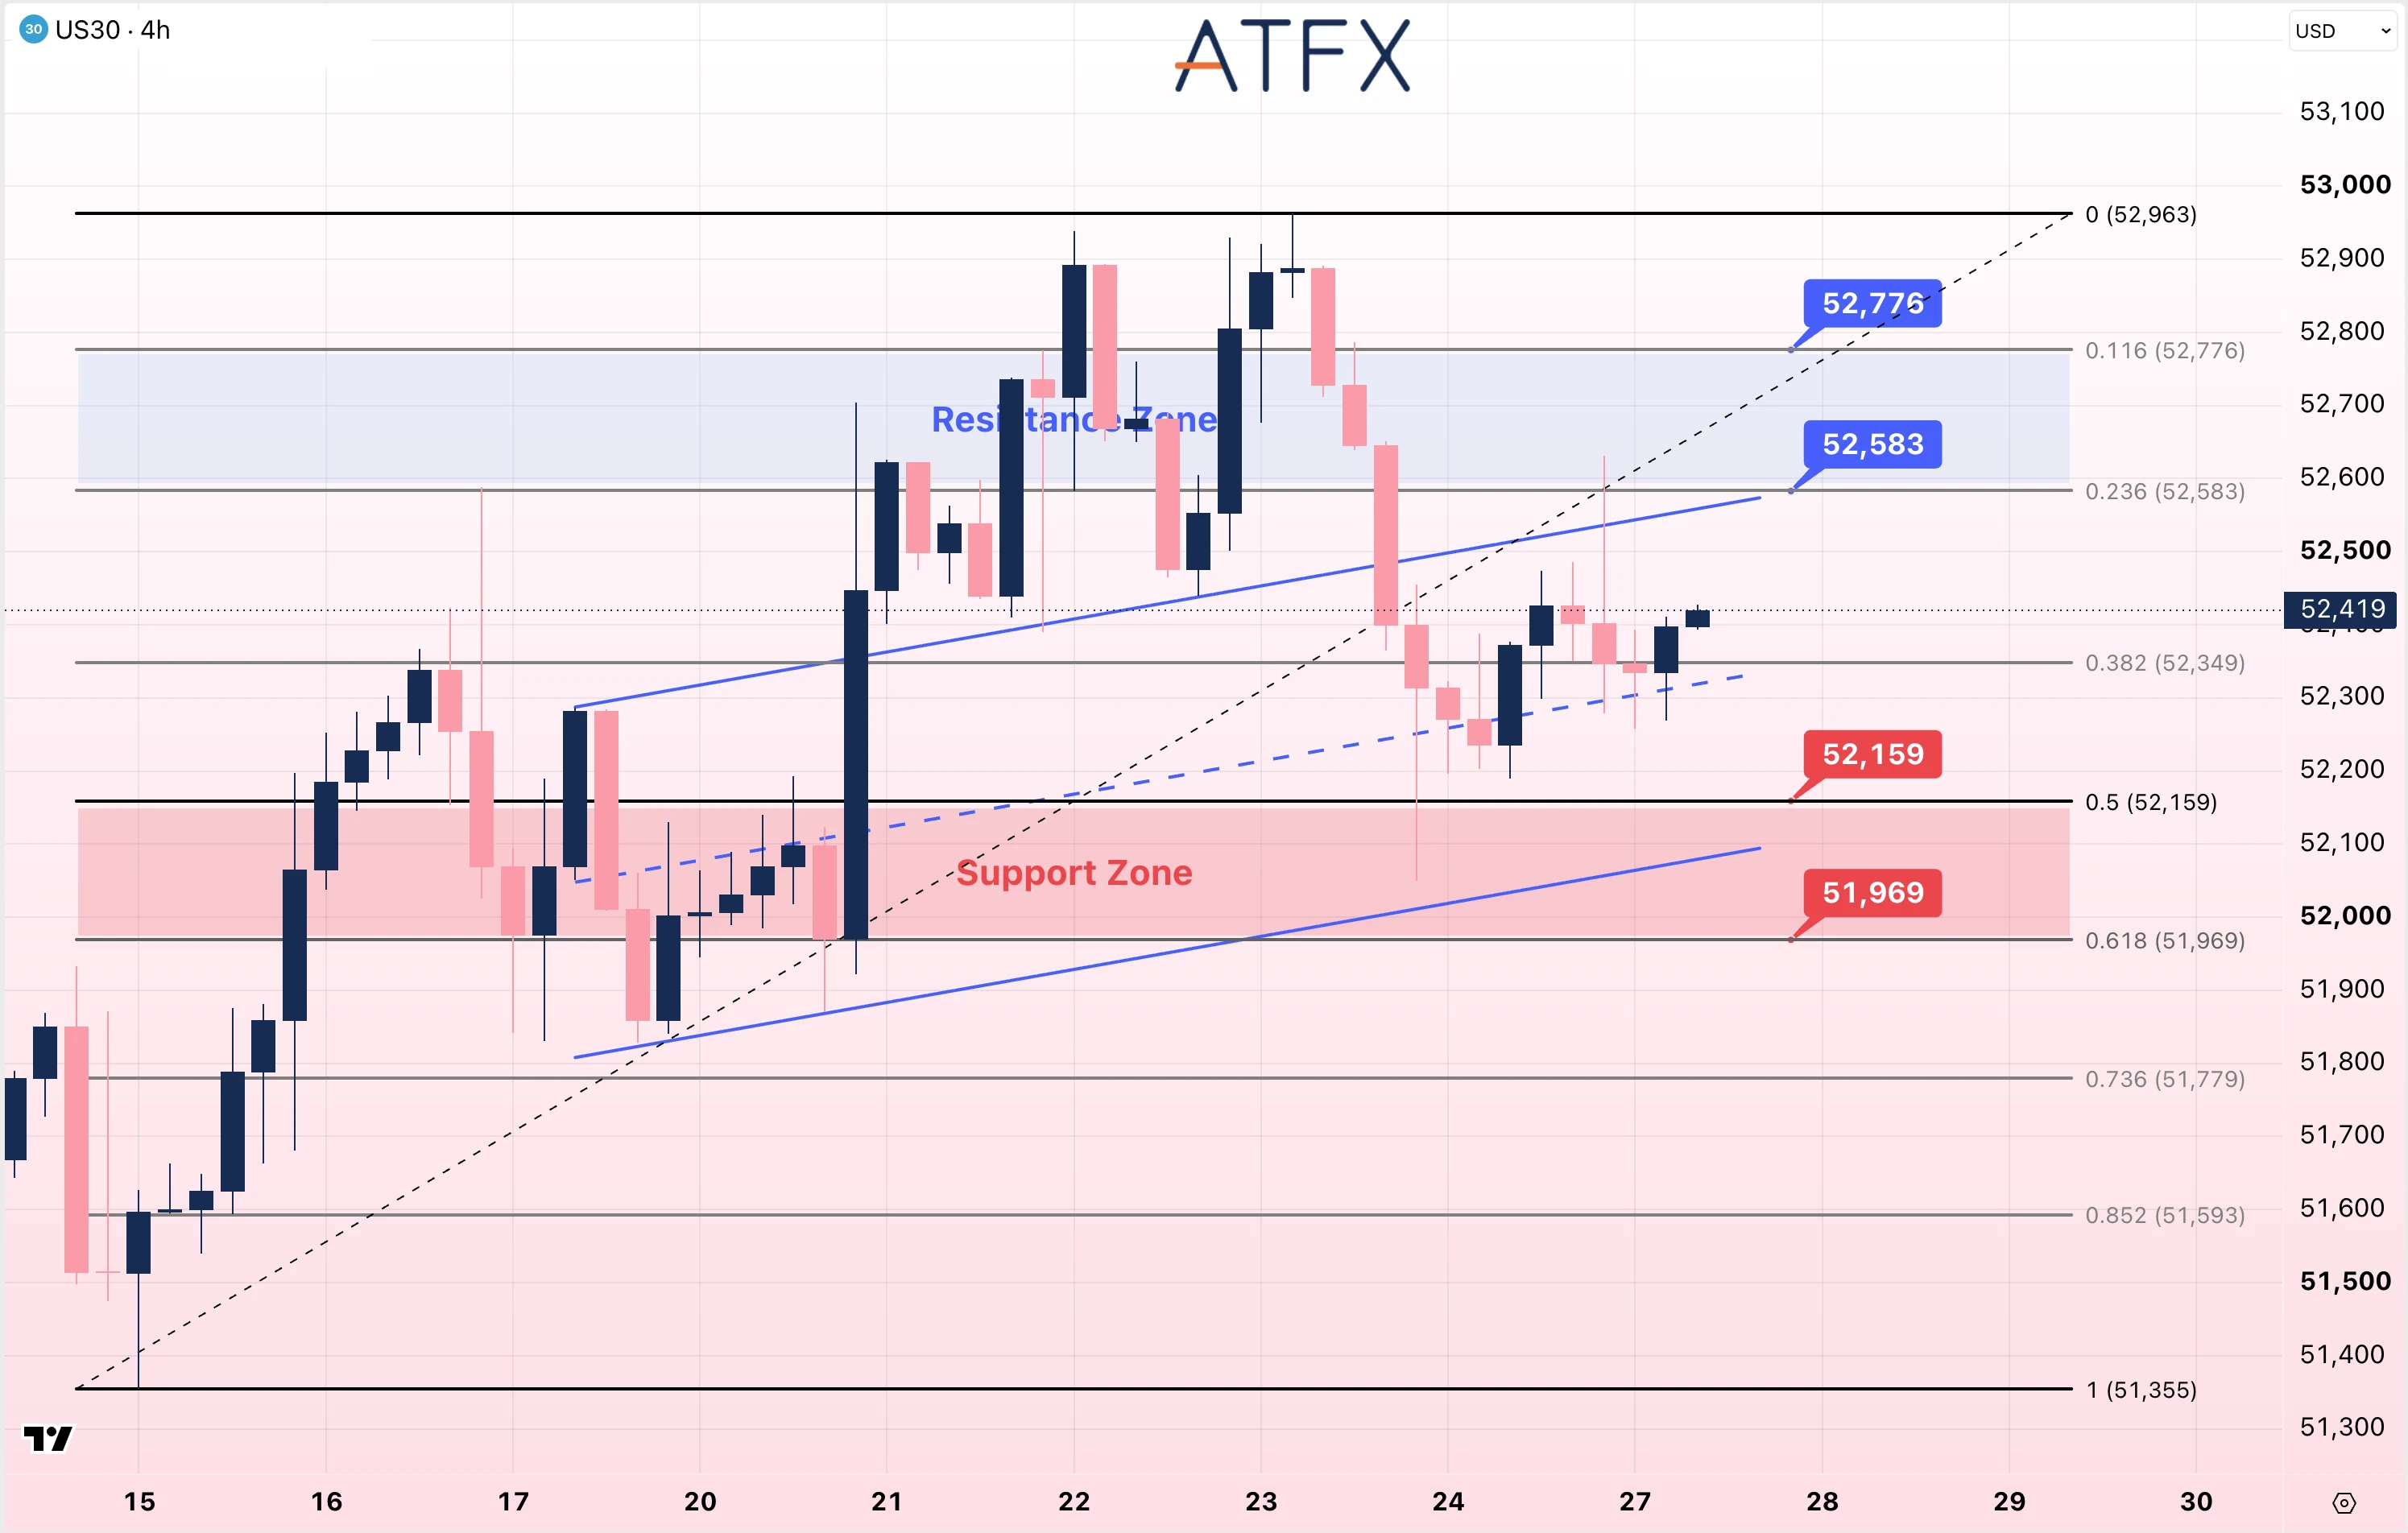
- Resistance: 52583/52776
- Support: 52159/51969
Analyst’s View: Monday’s gains came on a rebound in tech sentiment and an easing in oil prices, lifting risk appetite. Today, US data will offer another read on business activity and household confidence. Still, the Fed decision and company guidance will be crucial in judging how borrowing costs and energy expenses may filter through to the broader earnings outlook.
US30 is near 52,419, above 52,349 and the rising channel’s midline, following its rebound from the 52,200 area. Holding above 52,349 would leave room to test 52,583 and 52,776.
Bias: Neutral to Cautiously Bullish
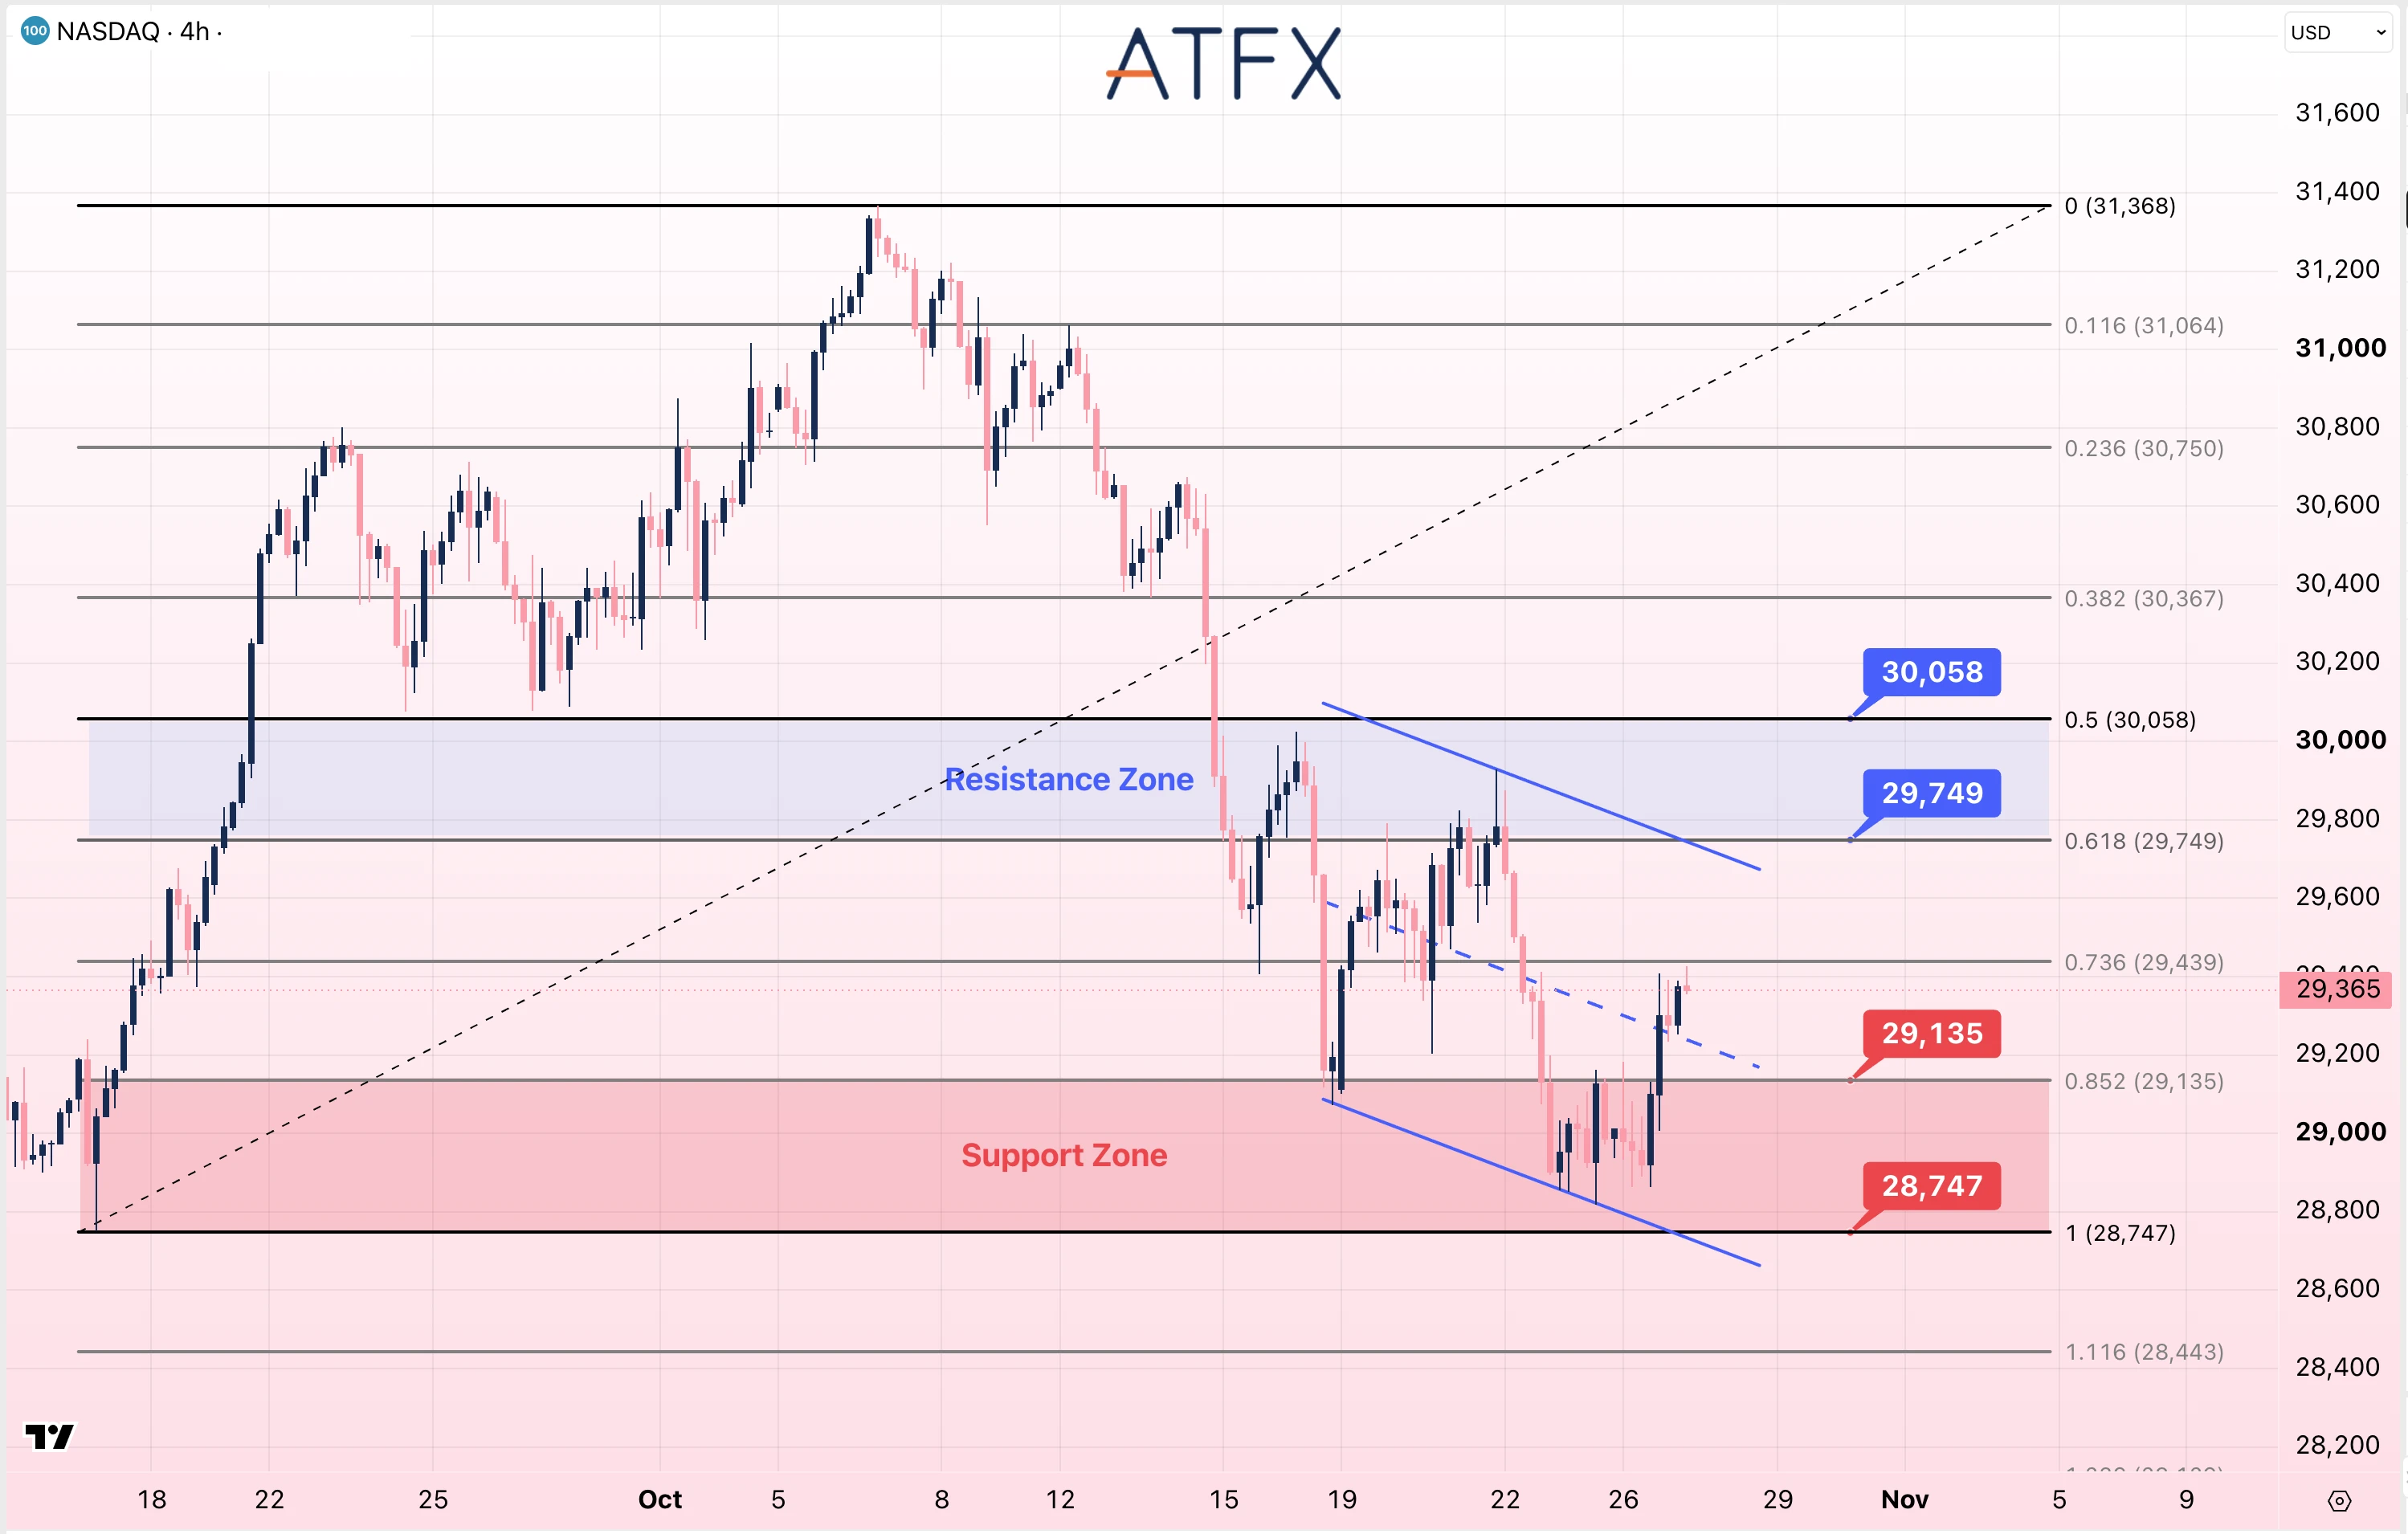
- Resistance: 29749/30058
- Support: 29135/28747
Analyst’s View: Anthropic’s IPO has boosted AI sentiment, but this week’s Microsoft and Alphabet earnings will show whether spending is translating into real revenue and cash flow. Fed guidance will also shape financing costs and valuations. Investors will weigh the rebound against the sector’s commercial progress and funding needs.
NAS100 is near 29,365 after rebounding above 29,135 and the descending channel’s midline. The next intermediate hurdle is 29,439, with marked resistance at 29,749 and 30,058. Holding above 29,135 would support the recovery.
Bias: Neutral to Cautiously Bullish
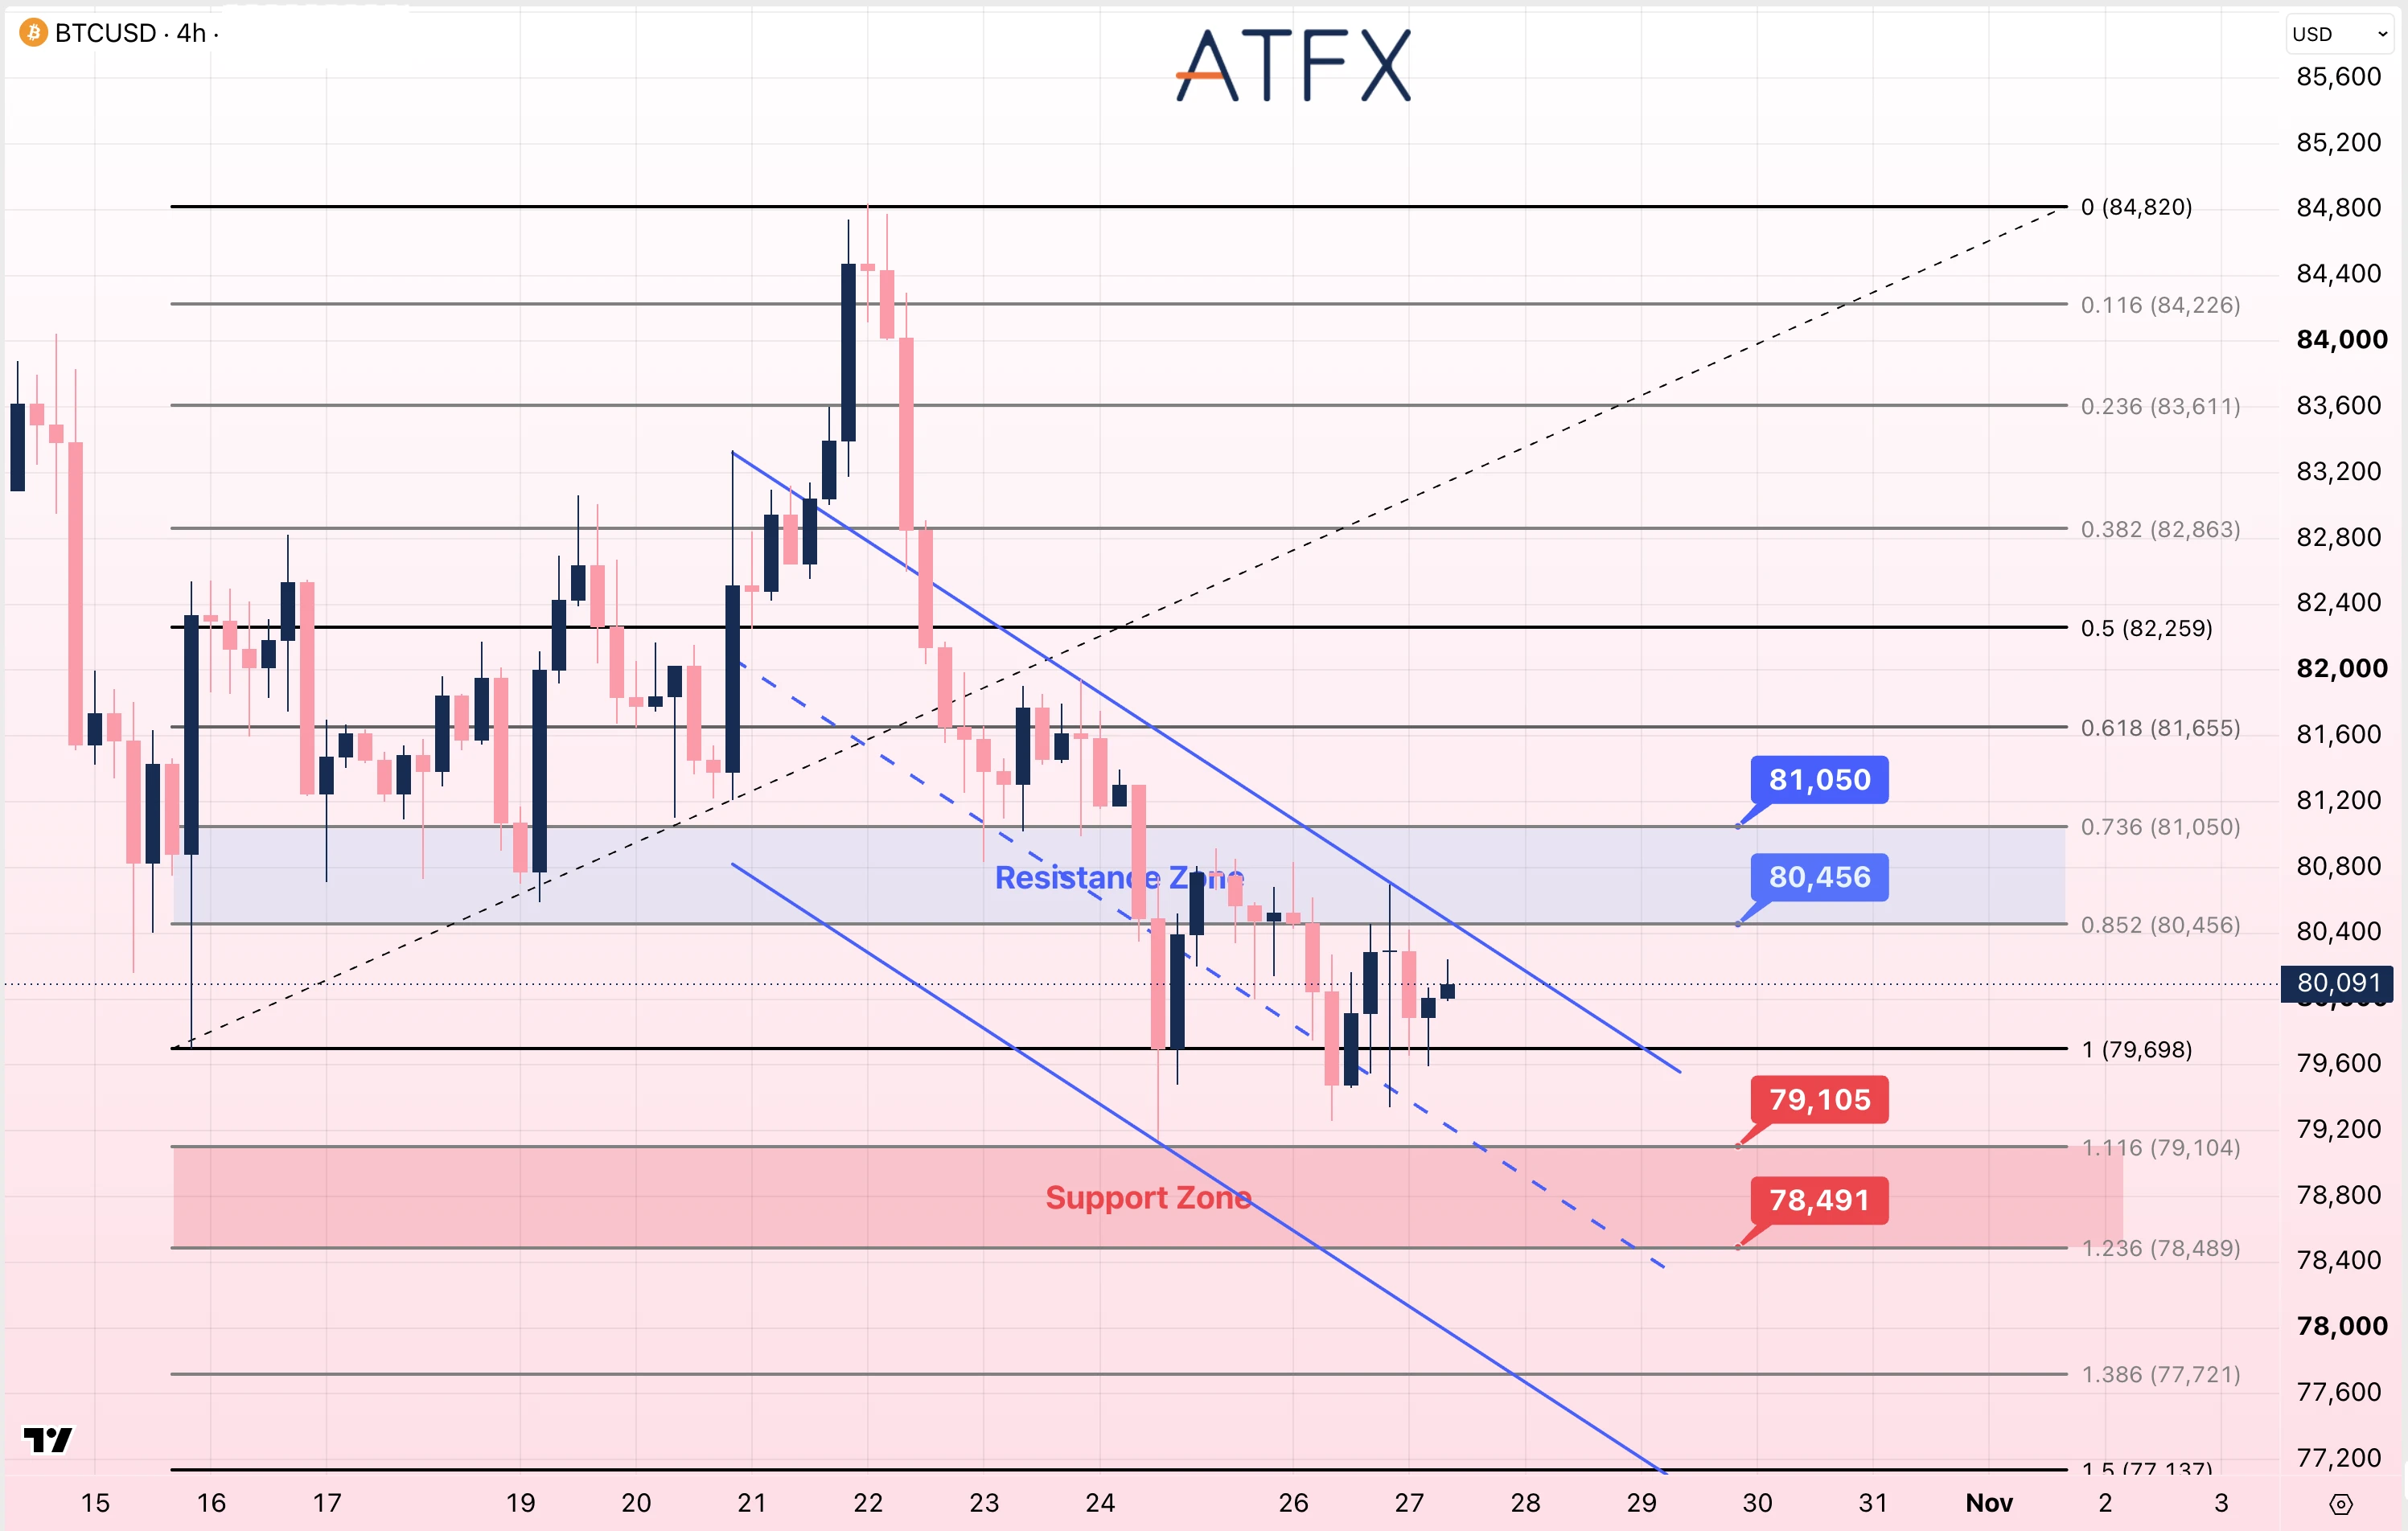
- Resistance: 80456/81050
- Support: 79105/78491
Analyst’s View: Bitcoin is holding near $80,000 as investors await central bank guidance and major tech earnings, but fears of further tightening are weighing on risk appetite. A stronger turn in tech sentiment could help crypto, while a more restrictive policy outlook and weaker tech sentiment could renew pressure.
Bitcoin is near $80,091, trading within a descending channel, above the $79,698 Fibonacci level but below the $80,456–$81,050 resistance zone. Clearing that zone would improve the short-term outlook. A loss of $79,698 would refocus attention on the key support levels at $79,105 and $78,491.
Bias: Neutral to Cautiously Bearish
Sources: Fed calendar | BoC calendar | Microsoft earnings | US market close | Gold update | Bitcoin update
Disclaimer: This analysis is for reference only and does not constitute investment advice.